Georgia’s seriously late credit-card share was 18.1%, ranking 3rd highest among the 50 states and D.C.
Each state is shaded by how distressed its households are, from green (least) to red (most), with data through September 2026. Georgia scores 80 out of 100.
In early 2025, 18.1% of Georgia card borrowers were seriously behind, ranking 3rd highest nationally. Debts in collections add to the strain, although household income is near the U.S. figure and unemployment is below it. Dougherty, Hancock, Talbot, Bibb and Terrell are Georgia’s most distressed counties. Oconee and Forsyth have the lowest scores.
- Score
- 80/100
- Data through
- September 2026
- Edition
- October 2026
Next edition expected March 2027
How Georgia ranks among the states
Georgia ranks 11th among the 50 states and D.C. on financial distress, though its households don’t borrow unusually much. Georgians carried $62,070 of household debt per person with a credit report at the end of 2025, close to the U.S. figure of $63,200 (Federal Reserve Bank of New York). Repayment is where the state stands out. In early 2025, 18.1% of Georgia’s credit card borrowers were 90 or more days behind, the 3rd highest share of any state. The share with a debt in collections was 19.7%, also the 3rd highest (Federal Reserve Bank of Philadelphia). Jobs aren’t the strain: unemployment is below the nation’s (see jobs).
What drives the score
Each of the four parts is built from one to three measures; each measure is ranked against the other states on a scale of 0 to 100, and a part with more than one averages them. Georgia’s four parts average 69. Its score, 80, is the share of the other states and D.C. whose own average is lower, so it isn’t the average of the parts.
- Collections and bankruptcy94In early 2025, 19.7% of Georgians had a debt in collections. In 2025 the state had 282.6 bankruptcy filings for every 100,000 residents, the 5th highest rate.
- Late payments93In early 2025, 18.1% of card borrowers and 12.4% of car-loan borrowers were 90 or more days behind, against 13.5% and 8.5% for the U.S.
- Renters’ housing costs66In 2024, 26.6% of renter households paid half or more of their income for housing, tied for 9th highest of the 50 states and D.C.
- Jobs23Unemployment averaged 3.3% from June to August 2026, against 4.1% for the U.S.
Beside its neighbors
Florida, South Carolina and Alabama are more distressed than Georgia. Tennessee and North Carolina are less distressed, and North Carolina is the least distressed of the five.
- Georgia 80
- Florida 96
- South Carolina 84
- Alabama 82
- Tennessee 52
- North Carolina 44
State Distress Index score, 0 to 100. Florida, the one neighbor ahead of Georgia, had a lower typical household income in 2024: $77,687 against $79,912. Housing was costlier for its renters. Half or more of income went to housing for 32.1% of Florida renter households, against 26.6% of Georgia’s (Census Bureau).
Which way it’s heading
At its worst
Ranked first of the 50 states and D.C. for six straight quarters, from the start of 2012 through mid-2013, with a score of 100.
Its least distressed point
Ranked 16th, with a score of 70, in the third quarter of 2021. Every quarter it spent outside the top seven fell between the spring of 2020 and mid-2022. By the third quarter of 2023 it was 3rd again, and it held that place through early 2025.
What moved it
On the way to that low, the jobs part dropped from 52 at the end of 2019 to 26 in the third quarter of 2021, and late payments eased from 84 to 81. Coming back, late payments rose to 91 and renters’ housing costs from 60 to 89 by early 2025, while jobs climbed back to 55 by mid-2023 and then eased to 28. Today, with newer figures, Georgia ranks 11th. The renters’ part is down to 66 and jobs to 23, and eight states have moved ahead of it.
Georgia was among the seven most distressed states in 67 of 75 quarters from mid-2006 to early 2025
State Distress Index score, 0 to 100, each quarter, third quarter of 2006 to first quarter of 2025.
Is Georgia a poor state?
No. On the Census Bureau’s income and poverty figures, Georgia sits close to the nation as a whole. Its typical household earned $79,912 in 2024, the 25th highest of the 50 states and D.C. That was a little below the national figure of $81,604. The poverty rate was 12.8%, the 15th highest among states, against 12.1% nationwide (Small Area Income and Poverty Estimates). Income per person, a different measure that divides all income by every resident, children included, ranks lower: $63,006, the 10th lowest (Bureau of Economic Analysis, 2024).
Median household income
$79,912
U.S. $81,604
25th highest of the 50 states and D.C., 2024
Residents in poverty
12.8%
U.S. 12.1%
15th highest of the 50 states and D.C., 2024
Children in poverty
16.9%
U.S. 15.5%
15th highest of the 50 states and D.C., 2024
Georgia’s poverty rate fell from 19.2% in 2011 and 2012 to 12.8% in 2024, above the U.S. rate in every estimate
Share of residents in poverty, Georgia and the United States, 1989 to 2024. The Census Bureau made no state estimates for 1990 to 1992 or 1994.
Where Georgia stands out: health insurance and credit scores
Two other measures put Georgia near the top. In 2020 to 2024, 12.4% of Georgians had no health insurance, the 3rd highest share, against 8.4% nationwide (Census Bureau). In early 2025, 19.8% of Georgians with a credit report had a score under 620, also the 3rd highest share (Federal Reserve Bank of Philadelphia). Wages, on the other hand, make up more of Georgians’ income than in most states. We don’t measure what causes poverty or late bills, so we don’t name a cause.
| Measure | Ga. | U.S. | Rank |
|---|---|---|---|
| Residents without health insurance 3rd highest | 12.4% U.S. 8.4% | 8.4% | 3rd highest |
| People with a credit score under 620 3rd highest | 19.8% U.S. 13.8% | 13.8% | 3rd highest |
| Income from wages 5th highest | 52.8% U.S. 49.7% | 49.7% | 5th highest |
| Adults without a high school diploma 11th highest | 10.8% U.S. 10.4% | 10.4% | 11th highest |
Ranks among the 50 states and D.C. Health insurance and schooling: Census Bureau, American Community Survey, 2020 to 2024. Credit scores: Federal Reserve Bank of Philadelphia, early 2025, with the U.S. number our population-weighted average of the states. Wages as a share of all personal income: Bureau of Economic Analysis, 2024.
Fewer Georgians get SNAP food help than a year ago
In June 2026, 1,354,676 Georgians got SNAP food benefits, 12.1% of residents. That is above the 10.7% share nationwide and below the state’s poverty rate (U.S. Department of Agriculture). The number getting help was down 7.8% from June 2025. The count has fallen every month since September 2025, when 1,494,293 people got benefits. It fell by 52,933 through February 2026, then by 86,684 from February to June.
Georgia began applying the federal budget law’s stricter work rule to applications and renewals after Nov. 1, 2025 (see what changed). But our figures can’t show how much of the drop it explains, and USDA says its latest months may still be revised. Fewer people getting help isn’t the same as fewer people in need.
To apply for SNAP or Medicaid in Georgia: Georgia Gateway →
Poorest counties in Georgia, and the most distressed
By the Census Bureau’s poverty rate, Georgia’s poorest county is Calhoun, in the southwest, where 36.8% of residents lived in poverty in 2024; it also has the lowest typical household income, $39,818 (Small Area Income and Poverty Estimates). Our County Distress Index, a score of household financial distress for each U.S. county, puts Dougherty County, home to Albany, first in Georgia and 3rd of 3,144 nationwide. Hancock, Talbot, Bibb and Terrell complete the state’s top five. Oconee County, next to Athens, is the least distressed in the state, 36th lowest in the country.
15 of the nation’s 100 most distressed counties are in Georgia; only one, Clayton, is in metro Atlanta
County Distress Index score, 0 to 100, data through August 2026, for each of Georgia’s 159 counties.
Loading the county map…
The county map could not be loaded. Every county is in the lists on this page.
Most distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 1 | Dougherty | 99 | 23.6% |
| 2 | Hancock | 99 | 30.7% |
| 3 | Talbot | 99 | 22.0% |
| 4 | Bibb | 99 | 23.4% |
| 5 | Terrell | 99 | 27.3% |
| 6 | Richmond | 98 | 19.0% |
| 7 | Early | 98 | 26.7% |
| 8 | Clayton | 98 | 17.4% |
| 9 | Brooks | 98 | 19.4% |
| 10 | Mitchell | 98 | 23.0% |
Least distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 155 | Bryan | 29 | 7.5% |
| 156 | Dawson | 28 | 8.0% |
| 157 | Cherokee | 19 | 6.8% |
| 158 | Forsyth | 4 | 4.5% |
| 159 | Oconee | 1 | 5.7% |
Rank in Georgia, 1 = most distressed. Ranks come from unrounded scores, which is why the top five all show 99 but hold different places. The poverty column is the share of each county’s residents counted as poor in 2024 (Census Bureau).
Every county, by score
Of Georgia’s 159 counties, 88 score 80 or more, and 35.6% of Georgians live in them. The 11 counties of the Atlanta Regional Commission’s region hold 46.1% of the state’s people, but only four of them score 80 or more: Clayton, Rockdale, Douglas and DeKalb. Counting from the most distressed, Fulton County, home to Atlanta, is 123rd, Gwinnett 121st and Cobb 142nd. Muscogee County (Columbus) is 22nd and Chatham (Savannah) 89th.
88 score 80–100
Dougherty, Hancock, Talbot, Bibb, Terrell, Richmond, Early, Clayton, Brooks, Mitchell, Twiggs, Burke, Sumter, Randolph, Worth, Wilkinson, Ben Hill, Crisp, Quitman, McDuffie, Ware, Muscogee, Baldwin, Spalding, Macon, Washington, Decatur, Taliaferro, Taylor, Turner, Screven, Seminole, Jefferson, Baker, Miller, Clay, Upson, Stewart, Liberty, Charlton, Warren, Lowndes, Newton, Evans, Telfair, Clinch, Chattooga, Rockdale, Cook, Marion, McIntosh, Laurens, Wilkes, Coffee, Lanier, Wayne, Emanuel, Calhoun, Grady, Atkinson, Stephens, Meriwether, Dodge, Toombs, Troup, Colquitt, Jenkins, Webster, Treutlen, Dooly, Carroll, Polk, Thomas, Candler, Peach, Heard, Pulaski, Jeff Davis, Elbert, Douglas, DeKalb, Johnson, Bulloch, Floyd, Bacon, Tattnall, Bleckley, Wilcox
18 score 70–79
Chatham, Tift, Berrien, Crawford, Henry, Clarke, Appling, Brantley, Murray, Walker, Wheeler, Jasper, Irwin, Franklin, Montgomery, Glynn, Long, Pierce
28 score 50–69
Whitfield, Walton, Schley, Chattahoochee, Putnam, Gordon, Madison, Butts, Lamar, Echols, Bartow, Camden, Haralson, Lincoln, Gwinnett, Glascock, Fulton, Houston, Hart, Barrow, Oglethorpe, Jones, Paulding, Catoosa, Morgan, Hall, Towns, Fannin
Georgia’s poorest counties aren’t its most distressed
Census poverty is one ingredient of our county score. It sits in one of five equal parts, beside child poverty, income, health insurance and disability; the other four parts weigh late payments, collections and bankruptcy, jobs and housing costs. In Georgia the two lists split. Calhoun, the poorest county, ranks 58th of 159 on distress, and Wheeler and Johnson, the next two poorest, rank 99th and 82nd; all three score better on jobs than on the other parts. Hancock is the only county in Georgia’s top ten for both poverty and distress. Going the other way, Dougherty is tied for 25th on poverty, Bibb tied for 28th and Richmond tied for 65th, yet all three are among the six most distressed, with late payments and collections both scoring 90 or more.
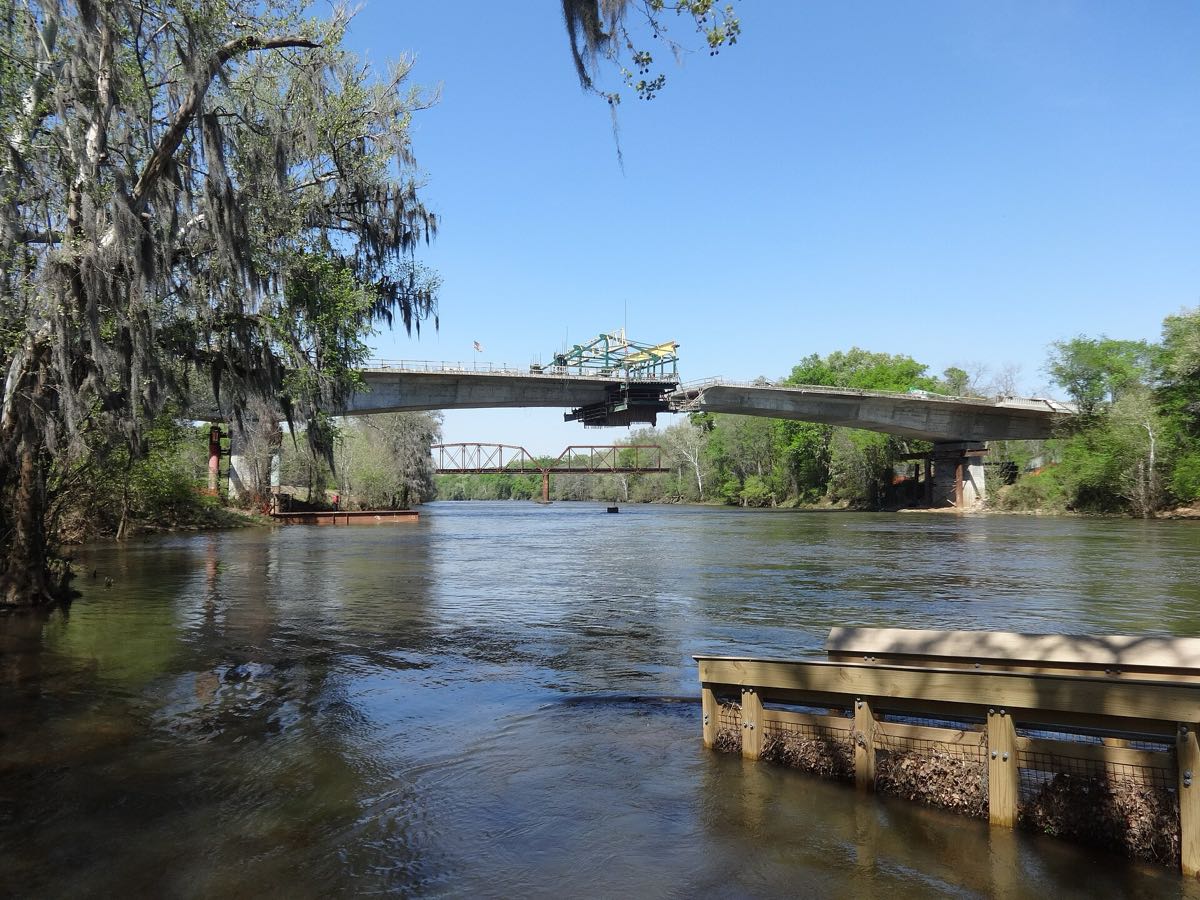
The Flint River at Albany, seen from Riverfront Park in 2015 while a new bridge was being built. Dougherty County, which includes Albany, counted 85,790 residents in the 2020 Census, down from more than 100,000 in 1980, its largest count. It is the 3rd most distressed of the 3,144 U.S. counties on our County Distress Index.
Source: U.S. Census Bureau, decennial census counts. Photo: Michael Rivera, Wikimedia Commons, CC BY-SA 4.0.

Is Georgia expensive to live in?
On rent, Georgia is close to average. The median rent was $1,393 a month from 2020 to 2024, the 21st highest of the 50 states and D.C., against $1,413 nationwide. It took 20.9% of the typical household’s income, about the same as the U.S. share of 20.8% (Census Bureau; our calculation). Many renters still struggle: in 2024, 26.6% of renter households paid half or more of their income for rent and utilities. We don’t measure the prices of food, gas or other goods, and we don’t track Atlanta’s housing market on its own, so we can’t rank Georgia’s overall cost of living.
Median rent, a month
$1,393
U.S. $1,413
2020 to 2024; 21st highest of the 50 states and D.C.
Rent as a share of the typical household’s income
20.9%
U.S. 20.8%
Our calculation from Census Bureau figures: rent, 2020 to 2024; income, 2024
Yearly cost of basics, one adult
$50,351
MIT Living Wage Calculator, 2025 dollars; 22nd highest of the 50 states and D.C.
More Georgia renters spend half or more of their income on housing than before the pandemic: 26.6% in 2024, up from 22.9% in 2019
Share of renter households paying half or more of their income for rent and utilities, Georgia and the United States, 2005 to 2024. The Census Bureau published no one-year figure for 2020.
What a Georgia household needs to get by
MIT’s Living Wage Calculator sets the yearly cost of basic needs in Georgia, before taxes, at $50,351 for a single adult with no children and $107,290 for two working parents with two children (2025 dollars). Both cover necessities only. For comparison, the typical Georgia household of any kind earned $79,912 in 2024.
Looking for Georgia’s minimum wage? The U.S. Department of Labor keeps a table of state minimum wages →
Owners and renters paying 30% or more for housing
| Measure | Ga. | U.S. | Rank |
|---|---|---|---|
| Renters spending 30% or more of income on housing 13th highest | 48.4% U.S. 47.6% | 47.6% | 13th highest |
| Homeowners spending 30% or more of income on housing 23rd highest | 20.7% U.S. 22.5% | 22.5% | 23rd highest |
| Homes lived in by their owners 13th lowest | 65.7% U.S. 65.2% | 65.2% | 13th lowest |
Ranks among the 50 states and D.C. Source: Census Bureau, American Community Survey, 2020 to 2024. Rent and housing costs in every state →
How many Georgians are behind on bills?
In early 2025, 23.0% of Georgians had at least one debt 90 or more days late, the 4th highest share of the 50 states and D.C., against 17.2% for the U.S. (Federal Reserve Bank of Philadelphia). For the national figure, we average the states, weighting each by population. These are household debts, such as credit cards, car loans and mortgages, not the state government’s debt.
Georgia’s place among the 50 states and D.C., 1 = highest share: cards 3rd, collections 3rd, car loans 4th, mortgages tied for 6th. Each U.S. number is our average of the states, weighted by population.
Late card payments have climbed: 12.9% of Georgia card borrowers were 90 or more days behind at the end of 2019, against 18.1% in early 2025. Collections moved the other way, from 27.5% to 19.7%, but that doesn’t mean fewer Georgians were unable to pay.
Starting in 2022, Equifax, Experian and TransUnion stopped putting many medical debts on credit reports. Nationwide, the share of people with a medical collection on their record fell from about 14% in March 2022 to about 5% in June 2023 (Consumer Financial Protection Bureau, April 2024). Georgia’s collections share dropped from 24.2% to 17.9% over about the same stretch and has risen since.
Mortgage trouble and thin equity
In September 2025, 2.2% of Georgia mortgages were 30 to 89 days late, tied for 7th highest of the 50 states and D.C., against 1.6% nationwide (Consumer Financial Protection Bureau). That is an early stage of falling behind. In the second quarter of 2026, 6.7% of mortgages had less than 10% equity, against 4.7% nationwide (Federal Housing Finance Agency). Equity is the home’s value minus what’s still owed; with little of it, a sale may not cover the loan.
| Measure | Ga. | U.S. | Rank |
|---|---|---|---|
| Mortgages with less than 10% equity 9th highest | 6.7% U.S. 4.7% | 4.7% | 9th highest |
| Mortgages owing more than the home is worth Tied for 7th highest | 0.4% U.S. 0.3% | 0.3% | Tied for 7th highest |
Second quarter of 2026. Ranks among the 50 states and D.C. Source: Federal Housing Finance Agency, National Mortgage Database.
Behind in dollars, not people
The New York Fed tracks money rather than people: how much of what’s owed is 90 or more days late. By that count, Georgia had the 3rd highest share of car-loan balances seriously behind at the end of 2025 and the 5th highest share of card balances. For all three loan types, a larger share was late than at the end of 2019.
| Loan type | Ga. | U.S. | Ga. 2019 | U.S. 2019 |
|---|---|---|---|---|
| Credit card | 13.9% End of 2025 U.S. 12.4% Ga. 2019 8.3% · U.S. 2019 8.1% | 12.4% | 8.3% | 8.1% |
| Auto loan | 7.0% End of 2025 U.S. 5.2% Ga. 2019 6.3% · U.S. 2019 4.9% | 5.2% | 6.3% | 4.9% |
| Mortgage | 1.3% End of 2025 U.S. 0.9% Ga. 2019 1.0% · U.S. 2019 1.0% | 0.9% | 1.0% | 1.0% |
Percent of each loan type’s balances 90 or more days past due, at the end of 2025 and of 2019 (Federal Reserve Bank of New York, Consumer Credit Panel / Equifax). It measures dollars rather than borrowers, so it isn’t comparable with the Philadelphia Fed shares above.
What Georgians owe
Debt per person with a credit report was $49,720 at the end of 2019, against $51,580 for the U.S., and has grown in both since (see the end-of-2025 figures). Card debt came to $4,610 per person with a credit report at the end of 2025, a little above the U.S. figure of $4,350 (Federal Reserve Bank of New York). Debt in every state →
What is Georgia’s unemployment rate?
It was 3.2% in August 2026, against 4.1% for the U.S., tied for 8th lowest of the 50 states and D.C., and down from 3.4% a year earlier (Bureau of Labor Statistics). For 2025 as a whole Georgia averaged 3.4%, below the U.S. average of 4.3%. Its lowest yearly rate in the available series, which start in 1990, was 3.1% in 2022; its highest was 10.4% in 2010. Jobs are the one part of Georgia’s distress score that sits low (see what drives the score).
Unemployment rate
3.2%
U.S. 4.1%
Tied for 8th lowest of the 50 states and D.C., August 2026
Unemployment rate, 2025 average
3.4%
U.S. 4.3%
Bureau of Labor Statistics, yearly average
Residents
11,302,748
2025; up 5.3% since 2020, tied for 10th highest growth of the 50 states and D.C.
Since March 2020, Georgia’s jobless rate has stayed under the U.S. rate in every month with figures
Monthly unemployment rate, seasonally adjusted, for Georgia and the United States from January 1990 to August 2026. October 2025 has no figures because of the federal shutdown.
Jobless rates peak along the Chattahoochee River
Chattahoochee County, on the Alabama line south of Columbus, had a jobless rate of 7.3% in August 2026. That unadjusted rate was Georgia’s highest and tied for 41st highest of the 3,143 U.S. counties with an August rate. Quitman, Clay and Stewart counties, also on the river, came next. Oconee County, next to Athens, had the lowest rate in the state, 2.6% (Bureau of Labor Statistics).
Unemployment claims are filed with Georgia’s state labor department.
Jobless rates in selected counties
| County | Rate |
|---|---|
| Chattahoochee | 7.3% |
| Quitman | 6.4% |
| Clay | 5.9% |
| Stewart | 5.8% |
| Hancock | 5.1% |
| Dougherty (Albany) | 4.8% |
| Richmond (Augusta) | 4.6% |
| Bibb (Macon) | 4.3% |
| Fulton (Atlanta) | 3.5% |
| Chatham (Savannah) | 3.0% |
Unemployment rate, August 2026, not adjusted for seasonal swings: Georgia’s five highest, then five counties with the state’s larger cities. Source: Bureau of Labor Statistics. Unemployment in every state →
Georgia bankruptcy filings: more Chapter 13 cases than any other state
Georgians filed 31,593 bankruptcy cases in 2025, up 10.1% from 2024, the biggest yearly total since 2019 (U.S. Courts). That is 282.6 filings for every 100,000 residents, the 5th highest rate of the 50 states and D.C., against 167.1 nationwide; the rates use the Census Bureau’s 2024 population estimates. More than half the cases, 53.4%, were Chapter 13, in which people repay some or all of their debts through a court plan over three to five years instead of having them wiped out.
Georgia’s 16,859 Chapter 13 cases in 2025 were the most of any state, as they have been every year since 2013. Counted per resident, the lead narrows: Georgia is the eighth-largest state, and per resident its Chapter 13 rate, 150.8 per 100,000, ranked 5th. Chapter 13 makes up more than half of all filings in eight states, all in the South. We don’t know why it is so common in Georgia.
| Year | Filings |
|---|---|
| 2018 | 45,726 |
| 2019 | 43,663 |
| 2020 | 27,953 |
| 2021 | 21,196 |
| 2022 | 23,716 |
| 2023 | 27,833 |
| 2024 | 28,683 |
| 2025 | 31,593 |
Bankruptcy cases filed in Georgia’s three federal court districts each calendar year. Source: Administrative Office of the U.S. Courts, Table F-2. Bankruptcy filings in every state →
How does foreclosure work in Georgia?
In Georgia, a lender can usually foreclose without going to court. Georgia home loans are usually secured by a security deed (a deed to secure debt; Official Code of Georgia Annotated, or O.C.G.A., § 44-14-160 and following), which lets the lender sell the home at auction if the loan goes unpaid. For a home you live in, federal rules generally bar the lender from starting until the loan is more than 120 days behind. The lender must mail you written notice at least 30 days before the sale and advertise it in the county’s legal newspaper for four weeks. Sales are held at the county courthouse on the first Tuesday of the month (O.C.G.A. § 44-14-162 and § 44-14-162.2). Once the home is sold, there is no right to buy it back, and Georgia has no statewide foreclosure mediation program.
- Goes through a court
- Usually not
- Written notice before the sale
- At least 30 days
- Newspaper ads before the sale
- 4 weeks
- Sale day
- First Tuesday
- Right to buy the home back after the sale
- No
- Lender can sue for the balance left after the sale
- After court confirmation
- Statewide foreclosure mediation
- No
What the law says. To collect a leftover balance, the lender must ask a Superior Court judge to confirm the sale within 30 days. Sources: O.C.G.A. § 44-14-161, § 44-14-162 and § 44-14-162.2; federal rule 12 CFR 1024.41. How foreclosure works in Georgia →
Georgia’s share of the federal Homeowner Assistance Fund, $354.2 million, had helped 11,984 households with mortgage and other housing costs through the first quarter of 2026 (U.S. Treasury). The state’s program, Georgia Mortgage Assistance, stopped taking new applications on March 1, 2026 (Georgia Department of Community Affairs).
What changed in Georgia in the past year
-
Oct. 14, 2026
Hurricane Helene farm aid: awards go out
The Georgia Department of Agriculture sent award notices from a $531.2 million federal block grant, agreed between the state and USDA, for farm, ranch and timber losses from Hurricane Helene. Notices went out for every kind of loss except timber, which is still under review. Applications opened March 16 and have closed. The money goes to producers, not to households. Eligible counties include Dougherty, Bibb, Hancock and Richmond. The first three are among the state’s five most distressed, and Richmond ranks 6th.
Georgia Department of Agriculture, Hurricane Helene Block Grant and award decisions
-
Oct. 6, 2026
The state gas tax is suspended again
Gov. Brian Kemp suspended Georgia’s motor fuel excise tax from Sept. 29 and on Oct. 6 extended the suspension through Nov. 5. The tax was also off this spring: a law signed March 20 suspended it for 60 days (it was 33.3 cents a gallon on gasoline), and a second order from the governor kept it off through June 3.
Georgia Department of Revenue, motor fuel tax suspension FAQ; Office of the Governor, March 20, 2026 and May 15, 2026
-
Oct. 1, 2026
SNAP time limits now reach adults through age 64
The federal budget law’s stricter SNAP work rule covers adults 18 through 64 who are able to work, aren’t pregnant and have no child under 14 in the household: they must work or train 80 hours a month, or lose benefits after three months in a three-year period. Georgia began applying it to applications and renewals after Nov. 1, 2025, and to people aged 60 to 64 on Oct. 1, 2026. The current three-year period ends Nov. 30, 2026 (see the SNAP numbers).
Georgia Division of Family and Children Services, able-bodied adults without dependents
-
May 28, 2026
Regulators approve a Georgia Power fuel and storm deal
The Public Service Commission unanimously approved a deal between Georgia Power and commission staff on fuel costs and storm repairs, mostly from Hurricane Helene. Georgia Power estimates that a home using 1,000 kilowatt-hours a month will pay $4.03 a month less, against the $1.32 saving it estimated when it first filed; the commission says savings will vary with usage. A freeze on Georgia Power’s base rates runs through 2028.
-
May 2026
A lower income tax and a one-time refund
House Bill 463, signed May 11, cut Georgia’s income tax rate to 4.99% for 2026, from 5.19%. Under House Bill 1000, signed March 20, the state is sending one-time refunds of up to $250 for single filers and $500 for married couples filing jointly; the Department of Revenue began issuing them May 4.
Office of the Governor, May 11, 2026 and March 20, 2026; Georgia Department of Revenue, May 4, 2026
-
Jan. 1, 2026
Bigger marketplace tax credits expire
The enlarged federal tax credits for marketplace health plans expired at the end of 2025. Georgia runs its own marketplace, Georgia Access, which says about 900,000 Georgians were enrolled in individual coverage as of September 2026; that is the state’s count, not a federal one (see health insurance).
Centers for Medicare & Medicaid Services, 2026 open enrollment report; Georgia Access
Georgia mortgage complaints: loan changes, collection and foreclosure come first
Since 2012, the Consumer Financial Protection Bureau has received 23,282 mortgage complaints from Georgia. The biggest group, 5,744, falls under the bureau’s older label for loan modifications, collection and foreclosure; close behind, with 5,641, are complaints about trouble during the payment process.
- Oct. 7, 2026 Mortgage Solutions of Colorado Payment process: trouble reaching the company to fix a problem with the loan Closed with explanation
- Oct. 3, 2026 Lakeview Loan Servicing Payment process: paying off the loan Closed with explanation
- Oct. 2, 2026 Mortgage Research Center Payment process Closed with explanation
- Oct. 1, 2026 Guild Mortgage Struggling to pay: trouble reaching the company about a modification, forbearance, bankruptcy or foreclosure In progress
- Oct. 1, 2026 Selene Finance Struggling to pay: trouble reaching the company about a modification, forbearance, bankruptcy or foreclosure Closed with explanation
- Sept. 30, 2026 Selene Finance Struggling to pay: applying for a modification, forbearance, short sale or deed-in-lieu Closed with explanation
- Sept. 30, 2026 Selene Finance Struggling to pay: foreclosure Closed with explanation
- Sept. 30, 2026 Rocket Mortgage Struggling to pay: an existing modification, forbearance or other relief Closed with explanation
- Sept. 30, 2026 Alliant Credit Union Payment process In progress
- Sept. 30, 2026 Select Portfolio Servicing Struggling to pay: applying for a modification, forbearance, short sale or deed-in-lieu Closed with explanation
Georgia’s ten newest complaints about paying a mortgage or getting help with one, not about getting a loan, newest first, from the Consumer Financial Protection Bureau’s public database as of Oct. 14, 2026. Complaints about credit reports are left out. Each complaint is one person’s account, which the bureau doesn’t check. Every Georgia mortgage complaint at the Consumer Financial Protection Bureau →
What to watch before the next edition
Five dates that bear on Georgia’s jobs, fuel prices, food help, power bills and health coverage, the nearest first.
-
Oct. 20, 2026
September jobless rates for every state
The Bureau of Labor Statistics publishes state unemployment rates for September on Oct. 20, for October on Nov. 20 and for November on Dec. 18. Georgia’s August rate was 3.2%.
Bureau of Labor Statistics, August 2026 state release and release schedule
-
Nov. 5, 2026
The gas tax suspension is set to end
The suspension of the state motor fuel excise tax runs through 11:59 p.m. Nov. 5 unless the governor extends it again.
Georgia Department of Revenue, motor fuel tax suspension FAQ
-
Nov. 30, 2026
The SNAP time-limit period ends
The three-year period for SNAP’s work time limit ends Nov. 30. People who lost benefits under the rule can apply again from that date, the state’s Division of Family and Children Services says.
-
December 2026
A hearing on how real-time pricing credits fuel costs
The Public Service Commission said it would finish a separate hearing by December on how Georgia Power credits revenue from its real-time pricing customers against fuel costs. A change could lower fuel costs for other customers, the commission said.
-
Jan. 1, 2027
Georgia Pathways rules change
Georgia Pathways, the state’s Medicaid coverage for adults 19 to 64 with incomes up to the federal poverty level, changes its eligibility rules under the federal budget law. Members will still need to show at least 80 hours a month of work, community service or other approved activities. Current members aren’t affected until they renew in 2027.
Georgia Pathways to Coverage, changes for 2027 and about Pathways
Where Georgia ranks highest and lowest
| Measure | Ga. | U.S. | Rank | Latest data |
|---|---|---|---|---|
| State Distress Index score 11th highest · Aug. 2026 | 80 U.S. — | — | 11th highest | Aug. 2026 |
| Card borrowers 90+ days late 3rd highest · Early 2025 | 18.1% U.S. 13.5% | 13.5% | 3rd highest | Early 2025 |
| People with a debt in collections 3rd highest · Early 2025 | 19.7% U.S. 13.2% | 13.2% | 3rd highest | Early 2025 |
| People with a credit score under 620 3rd highest · Early 2025 | 19.8% U.S. 13.8% | 13.8% | 3rd highest | Early 2025 |
| Residents without health insurance 3rd highest · 2024* | 12.4% U.S. 8.4% | 8.4% | 3rd highest | 2024* |
| Bankruptcy filings per 100,000 residents 5th highest · 2025 | 282.6 U.S. 167.1 | 167.1 | 5th highest | 2025 |
| Chapter 13 share of bankruptcies 8th highest · 2025 | 53.4% U.S. 35.9% | 35.9% | 8th highest | 2025 |
| Mortgages 30 to 89 days late Tied for 7th highest · Sept. 2025 | 2.2% U.S. 1.6% | 1.6% | Tied for 7th highest | Sept. 2025 |
| Renters paying half or more of income for housing Tied for 9th highest · 2024 | 26.6% U.S. 26.1% | 26.1% | Tied for 9th highest | 2024 |
| Residents in poverty 15th highest · 2024 | 12.8% U.S. 12.1% | 12.1% | 15th highest | 2024 |
| Household debt per person with a credit report 20th highest · End of 2025 | $62,070 U.S. $63,200 | $63,200 | 20th highest | End of 2025 |
| Residents getting SNAP Tied for 13th highest · June 2026 | 12.1% U.S. 10.7% | 10.7% | Tied for 13th highest | June 2026 |
| Median household income 25th highest · 2024 | $79,912 U.S. $81,604 | $81,604 | 25th highest | 2024 |
| Income per person 10th lowest · 2024 | $63,006 U.S. $73,204 | $73,204 | 10th lowest | 2024 |
| Unemployment rate, three-month average Tied for 11th lowest · June–August 2026 | 3.3% U.S. 4.1% | 4.1% | Tied for 11th lowest | June–August 2026 |
Ranks are among the 50 states and D.C. * Census five-year survey, 2020 to 2024. The unemployment rate is for August 2026. For card borrowers, collections and credit scores, the U.S. number is our average of the states, weighted by population. Each measure’s source is listed in Sources and method. Download this table: CSV.
Questions about Georgia
Is Georgia a poor state?
No. Its typical household earned $79,912 in 2024, the 25th highest of the 50 states and D.C., and 12.8% of Georgians lived in poverty, the 15th highest rate (U.S. Census Bureau). Where Georgia ranks near the top is falling behind on bills: in early 2025, 18.1% of its card borrowers were 90 or more days late, the 3rd highest share (Federal Reserve Bank of Philadelphia).
What is the poorest county in Georgia?
Calhoun County, in southwest Georgia. By the U.S. Census Bureau’s 2024 poverty rate, 36.8% of its residents lived in poverty, and it has the lowest typical household income, $39,818. On our County Distress Index the most distressed is Dougherty County, home to Albany, 3rd of 3,144 U.S. counties. Hancock County is the only county in Georgia’s top ten for both poverty and distress. See all 159 counties.
What is the poverty level in Georgia?
Georgia uses the 2026 federal poverty guideline for states outside Alaska and Hawaii. It is $15,960 a year for a single person and $33,000 for a family of four (U.S. Department of Health and Human Services). Georgia’s poverty rate was 12.8% in 2024 (U.S. Census Bureau).
What is Georgia’s unemployment rate?
It was 3.2% in August 2026, against 4.1% for the U.S. (U.S. Bureau of Labor Statistics). Georgia’s rate has been below the nation’s every month with figures since March 2020.
Is Georgia cheaper than Florida?
On rent, Georgia. The median rent was $1,393 a month in Georgia from 2020 to 2024, against $1,669 in Florida, and it took 20.9% of the typical Georgia household’s income, against 25.8% in Florida (U.S. Census Bureau; our calculation). We don’t measure the prices of other goods. Florida is also more distressed on our State Distress Index, scoring 96 to Georgia’s 80; see Florida’s page.
Why do so many Georgians file Chapter 13 bankruptcy?
We don’t know, and we don’t name a reason. Georgia had 16,859 Chapter 13 cases in 2025, the most of any state, and they made up 53.4% of its filings, against 35.9% nationwide (Administrative Office of the U.S. Courts). Per resident, its Chapter 13 rate ranked 5th.
Cite or reuse Georgia’s data
For grant applications, policy memos and news stories.
State Distress Index
Georgia
11thmost distressed state
of the 50 states and D.C.
More distressed than 80% of the other states and D.C.
Georgia ranks 11th of the 50 states and D.C. on American Default Research’s State Distress Index, which measures household financial distress. Georgia’s median household income, $79,912 in 2024, is near the national figure (U.S. Census Bureau). Yet in early 2025, 18.1% of Georgia credit card borrowers were 90 or more days behind and 19.7% of Georgians had a debt in collections, each the 3rd highest share of any state (Federal Reserve Bank of Philadelphia). On American Default Research’s County Distress Index, Dougherty County, home to Albany, ranks 3rd of all 3,144 U.S. counties.
Questions, interviews or a custom cut of the data: press@americandefault.org
Sources and method
We gather the data, run the numbers and research each state ourselves.
This edition: October 2026 · Next edition expected March 2027
- Late payments, collections, credit scoresFederal Reserve Bank of Philadelphia, Consumer Credit Explorerend of 2019 to early 2025
- Household debt and dollars behindFederal Reserve Bank of New York, Consumer Credit Panel / Equifaxend of 2019 and end of 2025
- Mortgages with little or no equityFederal Housing Finance Agency, National Mortgage Databasesecond quarter of 2026
- Mortgages 30 to 89 days late; mortgage complaints; medical debts on credit reportsConsumer Financial Protection Bureau: Mortgage Performance Trends; complaint database; Recent changes in medical collections on consumer credit recordsSept. 2025; Oct. 14, 2026; March 2022 to June 2023
- Bankruptcy filings and chaptersU.S. Courts, Table F-22013 to 2025
- Unemployment, state, county and nationalU.S. Bureau of Labor Statistics, Local Area Unemployment StatisticsJan. 1990 to Aug. 2026
- Poverty and income, state and countyCensus Bureau, Small Area Income and Poverty Estimates1989 to 2024
- Renters paying half or more of income for housingCensus Bureau, American Community Survey, 1-year2005 to 2024
- Health insurance, schooling, rent, housing costs and homeownershipCensus Bureau, American Community Survey, 5-year2020 to 2024
- Population, stateCensus Bureau, population estimates2020 to 2025
- Dougherty County populationCensus Bureau, Georgia county counts 1900 to 2000 and 2020 Census1980 and 2020
- Income per person and its sourcesU.S. Bureau of Economic Analysis2024
- SNAPU.S. Department of Agriculture Food and Nutrition AdministrationJune 2025 to June 2026
- Cost of basic needsMIT Living Wage Calculator2025 dollars
- Mortgage help fundU.S. Treasury, Homeowner Assistance Fund; Georgia Department of Community Affairsthrough the first quarter of 2026
- Atlanta regionAtlanta Regional CommissionOctober 2026
- Foreclosure lawOfficial Code of Georgia, Title 44, Chapter 14, Article 7; Georgia Attorney General, mortgage and foreclosure information; 12 CFR 1024.41as of 2026
- Poverty guidelineU.S. Department of Health and Human Services2026
- Housing counselorsU.S. Department of Housing and Urban DevelopmentOctober 2026
- What changed and what to watchGeorgia Department of Revenue, Office of the Governor, Georgia Division of Family and Children Services, Georgia Public Service Commission, Georgia Department of Agriculture, Centers for Medicare & Medicaid Services, Georgia Access, Georgia Pathways to Coverage, Bureau of Labor Statistics release schedule; every item links to the page we read (see what changed)Jan. 2026 to Jan. 2027
- County photoMichael Rivera, Wikimedia Commons, CC BY-SA 4.02015
The score has four equal parts: late payments; collections and bankruptcy; jobs; and renters’ housing costs. Each measure is ranked against the 50 states and D.C., and the score is the share of the other 50 that Georgia is more distressed than. The full method →
We write with AI tools, and Ross Kilburn checks and reviews every page before it's published.
Get the next Georgia edition by email
One email each time a new Georgia edition is out; the next is expected in March 2027. Unsubscribe anytime.
Thanks, that helps.