New York’s poverty rate was 14.0% in 2024 despite high income per person
Each state is shaded by how distressed its households are, from green (least) to red (most), with data through September 2026. New York scores 60 out of 100.
New York had 14.0% of residents in poverty in 2024 despite ranking among the highest-income states per person. Renters’ housing costs push up its distress score, while collections and bankruptcies are rarer than in most states. Bronx County is both the poorest and most distressed in New York; Saratoga County is the least distressed.
- Score
- 60/100
- Data through
- September 2026
- Edition
- October 2026
Next edition expected March 2027
How New York ranks among the states
New York is the 21st most distressed of the 50 states and D.C., and owing money isn’t what puts it there. It’s a high-income state with a lot of poverty: income per person was $85,552 in 2024, the 6th highest, while its poverty rate was the 10th highest. It’s also a state of renters. Only 54.3% of its occupied homes were lived in by their owners from 2020 to 2024, the smallest share of any state; only D.C., at 41.5%, is lower. Renters’ housing costs weigh most: on that part of the score New York is 4th highest among the states, and jobs come next. Late payments sit near the middle of the states, and collections and bankruptcy rank tied for 10th lowest.
What drives the score
The score has four parts. Each measure behind a part is scored from 0 to 100 by where New York falls among the 50 states and D.C., and each part averages its measures. New York’s four parts average 60. That average is higher than the four-part average of 30 of the other 49 states and D.C., or 60% of them, so New York’s score is 60. Every state score on this page reads the same way: a state that scores 80 is more distressed than 80% of the others.
- Renters’ housing costs93In 2024, 28.6% of renter households paid half or more of their income for housing, against 26.1% nationwide
- Jobs69Unemployment averaged 4.4% from June to August 2026; the U.S. rate averaged 4.1%
- Late payments53In early 2025, fewer New Yorkers were 90 or more days behind on cards and car loans than nationwide, and more on mortgages
- Collections and bankruptcy25In early 2025, 8.1% of residents with a credit record had a debt in collections (U.S. 13.2%); in 2025 there were 116.7 bankruptcy filings per 100,000 residents (2024 population)
Beside its neighbors
New Jersey and Pennsylvania score below New York, and Connecticut is the one neighbor that scores higher; the note below compares the two on jobs and renters’ costs.
State Distress Index score, 0 to 100. Connecticut is more distressed on jobs: its jobs part is 97, against 69 for New York, and its unemployment rate was 5.1% in August 2026, against 4.3% here (Bureau of Labor Statistics). On renters’ housing costs New York scores 93, higher than any of its five neighbors; Connecticut is next at 91.
Most distressed in the pandemic jobs slump, easing to early 2025, rising again since
At its worst
In the second quarter of 2020, New York was the 10th most distressed state, with a score of 82. Unemployment had peaked at 16.7% in May 2020, and the jobs part stood at 89. From 2020 through 2023 New York ranked between 10th and 16th in every quarter.
The slide to early 2025
The score fell every quarter from 70 (16th) at the end of 2023 to 56 (23rd) in the first quarter of 2025. Jobs and renters’ costs drove the change: the jobs part dropped from 83 to 60 and the renters’ part from 93 to 85, while late payments started and ended at 59.
Why today differs
Today New York is 21st, with a score of 60. Since the chart’s last quarter, the jobs part has climbed from 60 to 69, and the renters’ part from 85 to 93 with the Census Bureau’s 2025 estimate; late payments eased from 59 to 53, and collections and bankruptcy barely moved. At the end of 2019 New York ranked 13th with a score of 76. Its four-part average then, 64, was only a little above today’s 60, but more states and D.C. now average higher than New York: 20 today, against 12 then, so its score is lower.
New York’s worst quarter was the second of 2020, when it ranked 10th; by the first quarter of 2025 it ranked 23rd
New York’s State Distress Index score each quarter, 0 to 100, from the third quarter of 2006, the first with all four parts, to the first quarter of 2025.
What does it cost to live in New York?
Renting here costs more than in most states, and New York is a state of renters. The median rent was $1,621 a month from 2020 to 2024, the 10th highest among the 50 states and D.C., against $1,413 nationwide (U.S. Census Bureau). What weighs most is rent against income: in 2024, 28.6% of New York renter households paid half or more of their income for rent and utilities, the 4th highest share. And a bigger share of its occupied homes are rented than in any state; only D.C. is higher. We don’t measure food, energy or insurance prices, so we can’t rank New York’s whole cost of living, and our figures cover the state, not New York City alone.
Median rent, a month
$1,621
U.S. $1,413
10th highest among the 50 states and D.C. (2020 to 2024)
Renters paying half or more of income for housing
28.6%
U.S. 26.1%
4th highest among the 50 states and D.C. (2024)
Basic yearly budget, one adult
$62,167
4th highest among the 50 states and D.C. (MIT, 2025 dollars)
In every year of Census figures since 2005, a bigger share of New York renters than U.S. renters paid half their income for housing
Share of renter households paying half or more of their income for rent and utilities, New York and the U.S., each year from 2005 to 2024; there are no one-year Census figures for 2020.
What it costs to get by
The MIT Living Wage Calculator puts yearly basic needs for one adult with no children at $62,167 before taxes. That is the 4th highest among the 50 states and D.C. For two working parents with two children, it estimates $145,758, the 7th highest (2025 dollars). Those are statewide bare-bones budgets; we don’t hold one for New York City alone.
Owners feel the squeeze too: from 2020 to 2024, 27.4% of New York homeowners spent 30% or more of their income on housing costs, the 4th highest share (Census Bureau).
In New York City, rent-stabilized leases that start from Oct. 1, 2026 through Sept. 30, 2027 carry no increase; market-rate apartments aren’t covered. Con Edison’s electric customers in the city and Westchester face increases under a three-year plan approved in January 2026 (see what changed).
Rent takes more of a typical income here than in any neighboring state
| State | Rent, a month | Typical household income | Rent as share of income |
|---|---|---|---|
| New York Rent as share of income 22.7% | $1,621 Typical household income $85,768 | $85,768 | 22.7% |
| Massachusetts Rent as share of income 20.2% | $1,762 Typical household income $104,569 | $104,569 | 20.2% |
| New Jersey Rent as share of income 19.8% | $1,720 Typical household income $104,202 | $104,202 | 19.8% |
| Connecticut Rent as share of income 18.7% | $1,488 Typical household income $95,670 | $95,670 | 18.7% |
| Pennsylvania Rent as share of income 18.7% | $1,209 Typical household income $77,532 | $77,532 | 18.7% |
| Vermont Rent as share of income 17.9% | $1,234 Typical household income $82,836 | $82,836 | 17.9% |
| U.S. Rent as share of income 20.8% | $1,413 Typical household income $81,604 | $81,604 | 20.8% |
Rent is the median monthly rent from the Census Bureau’s American Community Survey, 2020 to 2024; income is 2024 median household income from its Small Area Income and Poverty Estimates. The share is a year of median rent divided by median household income, our calculation.
How is New York’s economy doing?
Unemployment is a little above the national rate and has started to ease. New York’s unemployment rate was 4.3% in August 2026, tied for 16th highest among the 50 states and D.C., against 4.1% for the U.S. (U.S. Bureau of Labor Statistics). A year earlier it was 4.5%; the bureau counts that drop as statistically significant, but not the gap with the national rate. The rate was 4.6% in every month published from September 2025 through June 2026 (the shutdown left no October figure), then eased to 4.4% in July.
Unemployment rate
4.3%
U.S. 4.1%
Tied for 16th highest among the 50 states and D.C. (August 2026)
Unemployment rate, 2025 average
4.3%
U.S. 4.3%
Even with the nation for the year
Highest month in BLS figures back to 1976
16.7%
May 2020, in the pandemic
New York’s unemployment rate has topped the nation’s in every month published since June 2025
Unemployment rate each month, New York and the U.S., seasonally adjusted, January 1990 to August 2026. The Bureau of Labor Statistics published no October 2025 figure because of the federal shutdown.
Above the nation’s rate in every year from 2020 to 2024
Counted over whole years, New York’s unemployment rate topped the U.S. rate in each year from 2020 through 2024. In 2020 it averaged 9.8%, the 5th highest among the 50 states and D.C., and in 2021 it was 7.1%, tied for 2nd highest, against 5.3% nationwide. By 2025 the two were even, at 4.3% (Bureau of Labor Statistics yearly averages).
Unemployment claims and the minimum wage
Unemployment claims go through the New York labor department. Its online and phone services are set to be offline for 9 to 12 days from Nov. 2, 2026, while it moves to a new system (see what to watch).
The minimum wage is $17.00 an hour in New York City, Long Island and Westchester and $16.00 in the rest of the state. The labor department says it won’t rise on Jan. 1, 2027 (New York labor department).
Unemployment is highest in Bronx County
| County | Rate |
|---|---|
| Bronx County (the Bronx) | 7.1% |
| Kings County (Brooklyn) | 5.3% |
| St. Lawrence County | 5.2% |
| Allegany County | 5.0% |
| Richmond County (Staten Island) | 4.8% |
| Yates County | 2.9% |
Unemployment rate in August 2026, not adjusted for seasonal swings, so it isn’t comparable with the statewide rate above: the five highest of New York’s 62 counties and the lowest. Bronx County’s rate was tied for 49th highest of the 3,143 U.S. counties with a rate. Source: U.S. Bureau of Labor Statistics.
Which New York counties are the poorest and most distressed?
Bronx County, the borough of the Bronx, is both New York’s poorest county and its most distressed. In 2024, 28.7% of its residents lived in poverty, the highest rate of the state’s 62 counties (Census Bureau, Small Area Income and Poverty Estimates). It scores 98 on our County Distress Index, which measures household financial strain in every U.S. county. The Bronx is the 56th most distressed of the 3,144 counties we score. It is New York’s only county among the 100 most distressed. Saratoga County, north of Albany, is the least distressed in the state. New York City’s five boroughs are counties of their own: Bronx, Kings (Brooklyn), New York (Manhattan), Queens and Richmond (Staten Island).
Bronx County is the most distressed county in New York; Saratoga County, north of Albany, is the least
County Distress Index score, 0 to 100, for each of New York’s 62 counties, with data through August 2026.
Loading the county map…
The county map could not be loaded. Every county is in the lists on this page.
Most distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 1 | Bronx | 98 | 28.7% |
| 2 | Montgomery | 75 | 15.5% |
| 3 | Kings | 69 | 19.2% |
| 4 | Oswego | 65 | 15.7% |
| 5 | Sullivan | 63 | 18.7% |
| 6 | Chautauqua | 62 | 18.7% |
| 7 | Chemung | 62 | 14.2% |
| 8 | Broome | 60 | 15.9% |
| 9 | Cattaraugus | 59 | 18.7% |
| 10 | Queens | 58 | 13.4% |
Least distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 58 | Nassau | 20 | 5.9% |
| 59 | Genesee | 19 | 9.9% |
| 60 | Ontario | 15 | 9.0% |
| 61 | Wyoming | 11 | 11.4% |
| 62 | Saratoga | 8 | 7.1% |
Rank among New York’s 62 counties, 1 = most distressed. Ranks come from unrounded scores. Poverty: the Census Bureau’s 2024 county poverty rate.
Every county, by score
Bronx County is the only one of New York’s 62 counties to score 80 or more. Montgomery and Kings counties follow at 75 and 69. At the other end, 10 counties score under 30, among them Nassau, on Long Island, and Westchester, just north of the city.
1 score 80–100
1 score 70–79
21 score 50–69
Kings, Oswego, Sullivan, Chautauqua, Chemung, Broome, Cattaraugus, Queens, Herkimer, St. Lawrence, Jefferson, Orleans, Orange, Niagara, Allegany, Fulton, Oneida, Washington, Schenectady, Richmond, Seneca
29 score 30–49
Schoharie, Clinton, Ulster, Franklin, New York, Cortland, Warren, Schuyler, Erie, Onondaga, Monroe, Chenango, Delaware, Steuben, Tioga, Madison, Rockland, Hamilton, Albany, Cayuga, Wayne, Otsego, Yates, Suffolk, Rensselaer, Essex, Dutchess, Greene, Tompkins
10 score 0–29
Columbia, Livingston, Westchester, Lewis, Putnam, Nassau, Genesee, Ontario, Wyoming, Saratoga
Tompkins County is among the poorest, yet far down the distress list
Each county’s score is built from five equal parts. They are late payments; collections and bankruptcy; jobs; renters’ housing costs; and a part combining poverty, child poverty, household income, disability and health insurance. Poverty is one factor among many, so the two lists split. Tompkins County, home to Ithaca, has the 7th highest poverty rate in New York, 17.3%. Yet Tompkins ranks 52nd on distress: it scores lower on collections and bankruptcy than any other county in the state, and its late-payment part is among the five lowest. Franklin County, around Malone on the Canadian border, has the 6th highest poverty rate but ranks 27th. Montgomery County runs the other way. Its poverty rate is tied for 13th highest in the state, yet it ranks 2nd on distress, with a late-payment part second only to the Bronx’s. Sites that use a different Census survey may name a different poorest county; these rates are the Census Bureau’s 2024 county estimates.
The seven counties with the highest poverty rates
| County | Poverty | Distress rank |
|---|---|---|
| Bronx | 28.7% | 1st |
| Kings | 19.2% | 3rd |
| Sullivan | 18.7% | 5th |
| Chautauqua | 18.7% | 6th |
| Cattaraugus | 18.7% | 9th |
| Franklin | 18.0% | 27th |
| Tompkins | 17.3% | 52nd |
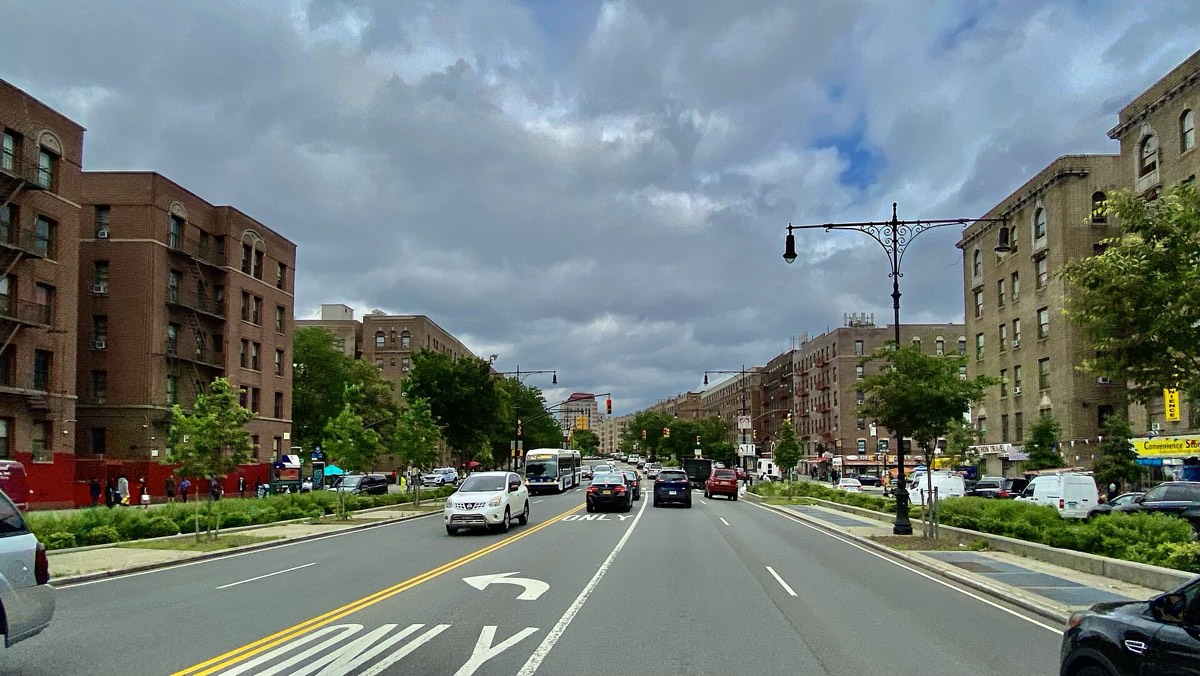
The Grand Concourse in the Bronx, looking north near East 170th Street, in June 2022. Bronx County scores 98 on our County Distress Index, the highest in New York, and its typical household earned $46,486 in 2024, the lowest of the state’s 62 counties (Census Bureau).
Source: U.S. Census Bureau. Photo: Andre Carrotflower, via Wikimedia Commons, CC BY-SA 4.0.

New York City against the rest of the state
New York City’s five counties hold 42.2% of New Yorkers, and weighted by population they average 65 on our index. The 48 counties that are not in the city, on Long Island or in the Hudson Valley average 43; the seven Hudson Valley counties, 36; and Long Island’s Nassau and Suffolk, 28. Of the people who live in New York counties scoring 60 or more, 85.8% live in the city.
American Default Research, County Distress Index, weighted by county population (Census Bureau). Regions as we group them; the Hudson Valley here is Dutchess, Orange, Putnam, Rockland, Sullivan, Ulster and Westchester.
Outside the city, distress runs from Montgomery to Chautauqua
Outside New York City, the five most distressed counties are spread across the state: Montgomery, around Amsterdam; Oswego, on Lake Ontario; Sullivan, in the Catskills; Chemung, around Elmira; and Chautauqua, in the far west. Each scores 62 or more. Montgomery’s late-payment part is the highest of any county outside New York City.
American Default Research, County Distress Index.
Are people leaving New York?
Yes, for other states, though arrivals from abroad have offset most of the loss. From July 2020 to July 2025, 1,045,769 more people moved from New York to other states than moved the other way, by the Census Bureau’s estimates. In the year to July 2025 the net loss was 137,586, or 6.9 for every 1,000 residents (2025 population), the largest for its size of the 50 states and D.C. overall. Over the same five years, 747,996 more people arrived from abroad than left, and births outnumbered deaths by 187,259. New York had 20,002,427 residents in 2025, down 0.6% since 2020, tied for 4th lowest among the 50 states and D.C. overall. The moves, arrivals and births above don’t add up to that change because the Census Bureau’s estimates also include a further adjustment.
Residents
20,002,427
2025, U.S. Census Bureau
More left for other states than moved in
137,586
Year to July 2025; the most per resident of the 50 states and D.C.
More arrived from abroad than left
747,996
July 2020 to July 2025
| Year to July 1 | Moves to and from other states | Moves to and from abroad | Births minus deaths | Total change |
|---|---|---|---|---|
| 2021 | −326,190 Other states Moves to and from abroad 28,772 Births minus deaths 28,302 · Total change −286,917 | 28,772 | 28,302 | −286,917 |
| 2022 | −284,910 Other states Moves to and from abroad 121,570 Births minus deaths 33,358 · Total change −122,320 | 121,570 | 33,358 | −122,320 |
| 2023 | −177,852 Other states Moves to and from abroad 211,383 Births minus deaths 39,190 · Total change 73,518 | 211,383 | 39,190 | 73,518 |
| 2024 | −119,231 Other states Moves to and from abroad 290,637 Births minus deaths 43,594 · Total change 214,876 | 290,637 | 43,594 | 214,876 |
| 2025 | −137,586 Other states Moves to and from abroad 95,634 Births minus deaths 42,815 · Total change 1,008 | 95,634 | 42,815 | 1,008 |
Net change in New York’s population, in people, each year from July 1 to July 1; a minus sign means more left than arrived. The total also includes a Census Bureau adjustment, so the three columns don’t add up to it exactly. Source: U.S. Census Bureau, population estimates, 2025 release. The estimates don’t record why people move, and we don’t hold data on reasons.
The population fell in the years to July 2021 and July 2022. It rose in each of the next three years, but by only 1,008 in the latest. Arrivals from abroad outnumbered people leaving for other states in 2023 and 2024, though not in 2025.
Is New York a poor state?
Not on average, but more of its people are poor than in most states. Income per person was $85,552 in 2024, the 6th highest among the 50 states and D.C., against $73,204 nationwide (U.S. Bureau of Economic Analysis), and the typical household earned $85,768, the 16th highest. Yet 14.0% of New Yorkers lived below the poverty line, the 10th highest rate, against 12.1% for the U.S., and so did 17.9% of its children (U.S. Census Bureau, Small Area Income and Poverty Estimates). Because income per person divides all income, investments included, by every resident, a few very high incomes can raise it a lot. We don’t hold a measure of how unevenly income is spread.
Income per person
$85,552
U.S. $73,204
6th highest among the 50 states and D.C. (2024)
Median household income
$85,768
U.S. $81,604
16th highest among the 50 states and D.C. (2024)
Residents in poverty
14.0%
U.S. 12.1%
10th highest among the 50 states and D.C. (2024)
New York’s poverty rate has been above the nation’s in every year since 2013, and by more in 2024 than in 2013
Share of people living in poverty, New York and the U.S., 1989 to 2024. The Census Bureau made no state estimates for 1990 to 1992 or 1994.
Highest poverty in the Bronx, lowest on Long Island
Poverty is concentrated. In 2024, 28.7% of Bronx County residents lived in poverty, against 5.9% in Nassau County, on Long Island, which has the state’s lowest rate and its highest typical household income, $141,824 (Census Bureau). Manhattan, New York County, has both wealth and want: its typical household earned $105,713, 5th highest among New York’s 62 counties, while its poverty rate, 15.5%, was tied for 13th highest (see the counties).
Our county data stops at the borough, so we can’t rank New York City’s neighborhoods.
Fewer New Yorkers get SNAP than a year ago
In June 2026, 2,720,960 New Yorkers got SNAP food benefits, 13.7% of residents (2024 population), the 5th highest share among the 50 states and D.C., against 10.7% nationwide (U.S. Department of Agriculture). That was 7.9% fewer than the 2,955,731 of June 2025 and the fewest since November 2020. The count fell in 11 of the 12 months from June 2025 to June 2026, so the slide began well before the federal work rules for adults without dependents returned on March 1, 2026.
June’s drop was the steepest of those months, and June was the first month people could lose SNAP under the time limit. The state’s Office of Temporary and Disability Assistance tells people who lost benefits from June 1 for not meeting the rules that they can reapply from Oct. 1, 2026. It gives no count of them, and the slide began a year earlier, so the rules can’t account for all of it.
The drop doesn’t show that fewer New Yorkers need help: 14.0% lived below the poverty line in 2024, the latest year measured (the SNAP rule changes).
SNAP applications go through the New York State Office of Temporary and Disability Assistance →
What changed in New York in the past year
-
July 1, 2026
The Essential Plan’s income limit comes down
New York’s Essential Plan, the state’s low-cost health plan for people with low incomes, now covers people with incomes up to twice the federal poverty level: $31,920 a year for one person in 2026, according to NY State of Health. In March the state health department estimated that about 450,000 New Yorkers would no longer qualify from July 1 and could buy a marketplace plan instead; the department attributes the change to the federal budget law of 2025 (Public Law 119-21). That figure is the state’s estimate of people affected, not a count of people who lost coverage.
NY State of Health, Essential Plan, read Oct. 16, 2026; New York State health department, March 23, 2026
-
June 25, 2026
A rent freeze for New York City’s rent-stabilized apartments
New York City’s Rent Guidelines Board set no increase for one- or two-year leases on rent-stabilized apartments that begin from Oct. 1, 2026 through Sept. 30, 2027. For leases that began in the year before, it had allowed 3% for one year and 4.5% for two. The freeze doesn’t reach market-rate apartments or homes outside the city.
-
March 1, 2026
SNAP work rules return across the state
Adults without dependents who get SNAP food benefits must again meet federal work rules to keep getting them beyond a time limit. USDA ended New York’s waiver of the rules as of Nov. 2, 2025. A federal court case in Rhode Island kept the waiver in place in every county but Saratoga through Feb. 28, 2026, the New York City Department of Social Services told its partner groups. The state’s Office of Temporary and Disability Assistance says people who lost SNAP from June 1, 2026 for not meeting the rules can reapply from Oct. 1, 2026, when the time limit resets. New York’s SNAP count was already falling before the rules returned (see SNAP).
New York City Department of Social Services, Nov. 25, 2025; New York State Office of Temporary and Disability Assistance, SNAP work requirements, read Oct. 16, 2026
-
Jan. 22, 2026
Con Edison gets a smaller rate increase than it asked for
New York’s Public Service Commission approved a three-year electric and gas rate plan for Con Edison, which serves New York City and Westchester County. For a home using 280 kilowatt-hours of electricity a month, the commission’s summary puts the first year’s increase at $4.00 a month, or 3.9% of the total bill; the company had asked for $14.13 a month.
New York State Public Service Commission, Jan. 22, 2026; electric rate case summary
-
Jan. 1, 2026
A higher minimum wage and a bigger child credit
The minimum wage rose to $17.00 an hour in New York City, Long Island and Westchester and to $16.00 in the rest of the state, from $16.50 and $15.50 in 2025 (New York Labor Law § 652). For 2026, the Empire State child credit is $1,000 for each child under 4, as in 2025, and $500 for each child aged 4 to 16, up from $330 (New York State Department of Taxation and Finance).
New York Labor Law § 652; New York State Department of Taxation and Finance, Empire State child credit, read Oct. 16, 2026
-
Oct. 30, 2025
A state emergency over food help during the shutdown
With November’s federal SNAP benefits about to lapse during the federal government shutdown, Gov. Kathy Hochul declared a state emergency and announced state money for emergency food help.
How many New Yorkers are behind on bills?
A bit fewer than nationwide, except on mortgages. In early 2025, 15.5% of New Yorkers with a credit record were 90 or more days late on at least one debt, against 17.2% for the U.S. (Federal Reserve Bank of Philadelphia). We calculate the national share as a population-weighted average of the states.
New York’s place among the 50 states and D.C., 1 = the highest share: mortgages tied for 6th, cards 25th, car loans 31st, collections 48th. We make each U.S. bar by weighting the states by population.
At the end of 2019, 10.9% of New Yorkers with a credit record had a debt in collections, meaning an unpaid debt passed to a collector. By early 2025 the share was 8.1%. The fall doesn’t by itself mean fewer New Yorkers are struggling: the share had already dropped to 9.3% by early 2022, before the credit report change described next. It has climbed back from its low of 7.3% at the end of 2023.
Credit reports changed too; that does not mean household finances changed. In 2022, the three big credit bureaus said they would stop reporting certain medical debts. Nationwide, the share of people with a medical collection on their record went from about 14% in March 2022 to about 5% in June 2023 (Consumer Financial Protection Bureau). We don’t hold New York’s own medical figure, so we can’t say how much of its drop that accounts for.
Counted in dollars, late mortgage debt is among the highest of any state
The Federal Reserve Bank of New York looks at dollars instead of people. At the end of 2025, 1.4% of the money owed on New York mortgages was 90 or more days late, tied for 3rd highest among the 50 states and D.C., against 0.9% nationwide. At the end of 2019 its share, 1.9%, was the highest of the 50 states and D.C. Late card balances were above the U.S. share too, and late car-loan balances below it.
| Loan type | New York | U.S. | New York 2019 | U.S. 2019 |
|---|---|---|---|---|
| Credit card | 12.9% End of 2025 U.S. 12.4% New York 2019 9.0% · U.S. 2019 8.1% | 12.4% | 9.0% | 8.1% |
| Auto loan | 4.3% End of 2025 U.S. 5.2% New York 2019 4.1% · U.S. 2019 4.9% | 5.2% | 4.1% | 4.9% |
| Mortgage | 1.4% End of 2025 U.S. 0.9% New York 2019 1.9% · U.S. 2019 1.0% | 0.9% | 1.9% | 1.0% |
Share of each kind of balance 90 or more days past due, at the end of 2025 and the end of 2019. Source: Federal Reserve Bank of New York, Consumer Credit Panel / Equifax. It counts dollars, so it can’t be set beside the Philadelphia Fed’s count of people above, and it includes old debts that lenders have written off but still report.
Few homeowners are short on equity
Only 1.2% of New York mortgages had less than 10% equity in the second quarter of 2026, the 2nd lowest share among the 50 states and D.C., against 4.7% nationwide (Federal Housing Finance Agency). Equity is the part of a home’s value that its owner doesn’t owe. Fewer New York mortgages than U.S. mortgages were in the early stage of falling behind, too. We haven’t found a source that explains why more New York mortgages are seriously late than in most states, so we don’t offer a reason.
| Measure | New York | U.S. | Rank |
|---|---|---|---|
| Mortgages 30 to 89 days late, Sept. 2025 Tied for 30th highest | 1.4% U.S. 1.6% | 1.6% | Tied for 30th highest |
| People with a credit score under 620, early 2025 28th highest | 11.9% U.S. 13.8% | 13.8% | 28th highest |
| Household debt per person with a credit report, end of 2025 26th highest | $59,420 U.S. $63,200 | $63,200 | 26th highest |
Rank among the 50 states and D.C., 1 = the highest. Mortgages 30 to 89 days late: Consumer Financial Protection Bureau. Credit scores: Federal Reserve Bank of Philadelphia; for the U.S. we weight each state by its population. Debt per person: Federal Reserve Bank of New York. Late payments in every state →
Bankruptcy filings in New York rose for a fourth straight year
New Yorkers filed 23,186 bankruptcy cases in 2025, up 8.7% from 2024 and the most since 2019, when they filed 35,171 (Administrative Office of the U.S. Courts). Filings have risen every year since the low of 14,734 in 2021. For the state’s size, the rate is still below the nation’s: 116.7 filings for every 100,000 residents (2024 population), the 20th lowest among the 50 states and D.C., against 167.1 nationwide.
Most filers use Chapter 7, which can wipe out many debts without a repayment plan: 65.2% of New York’s 2025 filings. Another 30.0% were under Chapter 13, in which a filer repays part of the debts through a court-approved plan, and 4.5% were under Chapter 11, which lets a business or a person keep going while reorganizing debts. That Chapter 11 share is the 4th highest among the 50 states and D.C. overall. The few left were filed under other chapters. The totals on this page count every chapter, business cases included. How bankruptcy works →
| Year | Filings |
|---|---|
| 2001 | 69,060 |
| 2005 | 109,601 |
| 2010 | 56,479 |
| 2019 | 35,171 |
| 2020 | 20,987 |
| 2021 | 14,734 |
| 2022 | 15,542 |
| 2023 | 19,303 |
| 2024 | 21,340 |
| 2025 | 23,186 |
Cases of every chapter filed in New York’s four federal bankruptcy court districts in selected calendar years. Of the years we hold, 2001 to 2025, 2005 had the most filings; we have no figure for 2004. Source: Administrative Office of the U.S. Courts, Table F-2. Bankruptcy filings in every state →
How foreclosure works in New York
Every home foreclosure in New York goes through a court. The lender sues in the state Supreme Court, New York’s main trial court, and the home can be sold only under a court judgment (RPAPL Article 13). At least 90 days before suing, the lender must mail the borrower a notice that lists at least five housing counseling agencies, and report it to the state’s Department of Financial Services (RPAPL §§ 1304 and 1306). Owners who live in a one- to four-family home get a settlement conference, which the court must hold within 60 days after the lender files proof that the papers were served; both sides must negotiate in good faith (CPLR 3408). Once the home is sold, there’s no right to buy it back. Federal rules generally keep a mortgage company from filing the first foreclosure papers until a loan is more than 120 days behind.
- Goes through a court
- Always
- Notice before the case
- 90 days
- Settlement conference
- Required
- Buy-back right after the sale
- None
- Lender can seek the balance left
- Yes
- Homestead protection
- Up to $204,825
What the law says for a home you live in. A lender that wants the balance left after the sale must ask the court within 90 days, and the court counts the home’s fair market value against the debt (RPAPL § 1371). The homestead exemption shields $102,400 to $204,825 of home equity from most creditors, depending on the county, as adjusted April 1, 2024; it doesn’t stop a mortgage foreclosure (CPLR 5206). Sources: New York Real Property Actions and Proceedings Law §§ 1304, 1306, 1353 and 1371; Civil Practice Law and Rules 3408 and 5206; federal rule 12 CFR 1024.41. How foreclosure works in New York →
New York received $539.5 million from the federal Homeowner Assistance Fund and had helped 19,072 homeowners through early 2026 (U.S. Treasury). The state’s program is closed and no longer serving people on its waitlist (New York State Homes and Community Renewal).
Loan changes and foreclosure top New Yorkers’ mortgage complaints
New Yorkers have filed 27,287 mortgage complaints with the Consumer Financial Protection Bureau since 2012. Loan modification, collection and foreclosure came up most often (7,104), then trouble during the payment process (5,451), then loan servicing, payments or escrow (4,494).
- Oct. 14, 2026 FirstKey Holdings, LLC Struggling to pay mortgage: Foreclosure In progress
- Oct. 8, 2026 Santander Holdings USA, Inc. Struggling to pay mortgage: An existing modification, forbearance plan, short sale, or other loss mitigation relief In progress
- Oct. 2, 2026 Shellpoint / NewRez Trouble during payment process: Escrow, taxes, or insurance In progress
- Oct. 1, 2026 Beacon Financial Corporation Trouble during payment process: Escrow, taxes, or insurance In progress
- Oct. 1, 2026 Lakeview Loan Servicing Struggling to pay mortgage: Trying to communicate with the company to fix an issue related to modification, forbearance, short sale, deed-in-lieu, bankruptcy, or foreclosure Closed with explanation
- Oct. 1, 2026 Bank of America Struggling to pay mortgage: Trying to communicate with the company to fix an issue related to modification, forbearance, short sale, deed-in-lieu, bankruptcy, or foreclosure In progress
- Oct. 1, 2026 KeyBank Trouble during payment process: Escrow, taxes, or insurance Closed with explanation
- Oct. 1, 2026 Webster Bank, National Association Trouble during payment process: Fees charged Closed with explanation
- Sept. 30, 2026 JPMorgan Chase Trouble during payment process: Payment process In progress
- Sept. 30, 2026 M&T Bank Struggling to pay mortgage: Trying to communicate with the company to fix an issue related to modification, forbearance, short sale, deed-in-lieu, bankruptcy, or foreclosure Closed with non-monetary relief
The ten latest New York complaints about paying a mortgage or getting help with one, newest first, from the Consumer Financial Protection Bureau’s public complaint record as of Oct. 14, 2026. Complaints about taking out a new loan, and complaints naming a credit reporting company, are left out. Each complaint is one person’s account; the bureau doesn’t check what people tell it, and a complaint isn’t a finding against the company. Every New York mortgage complaint at the Consumer Financial Protection Bureau →
What to watch before the next edition
Four dates before the next edition, nearest first: a jobs report, a pause in unemployment services, and two New Year’s Day items, the minimum wage holding still and Con Edison’s next rate step.
-
Oct. 20, 2026
Every state’s September unemployment rate
The U.S. Bureau of Labor Statistics is scheduled to publish September’s state unemployment rates, the first update since New York’s August rate of 4.3%.
U.S. Bureau of Labor Statistics, State Employment and Unemployment, Sept. 18, 2026
-
Nov. 2, 2026
Unemployment services go offline for an upgrade
The New York labor department starts moving unemployment insurance to a new system at 5 p.m. It expects the work to take 9 to 12 days, during which online and phone unemployment services will be unavailable and payments will be delayed.
New York labor department, unemployment insurance, read Oct. 16, 2026
-
Jan. 1, 2027
No inflation raise for the minimum wage
The New York labor department says the minimum wage will stay at $17.00 an hour in New York City, Long Island and Westchester and $16.00 elsewhere, because one of the conditions in state law that can stop the yearly inflation increase has been met. Home care aides’ minimum wage is the exception.
-
Jan. 1, 2027
Con Edison’s second rate step is set to begin
In the second year of the plan approved in January 2026, Con Edison electric bills are set to rise another $3.55 a month for a home using 280 kilowatt-hours.
New York State Public Service Commission, electric rate case summary, January 2026
Where New York ranks highest and lowest
| Measure | New York | U.S. | Rank | Latest data |
|---|---|---|---|---|
| Renters paying half or more of income for housing 4th highest · 2024 | 28.6% U.S. 26.1% | 26.1% | 4th highest | 2024 |
| Mortgage balances 90+ days late Tied for 3rd highest · End of 2025 | 1.4% U.S. 0.9% | 0.9% | Tied for 3rd highest | End of 2025 |
| Owners paying 30% or more of income for housing 4th highest · 2024* | 27.4% U.S. 22.5% | 22.5% | 4th highest | 2024* |
| Residents getting SNAP food benefits (2024 population) 5th highest · June 2026 | 13.7% U.S. 10.7% | 10.7% | 5th highest | June 2026 |
| Income per person 6th highest · 2024 | $85,552 U.S. $73,204 | $73,204 | 6th highest | 2024 |
| Residents in poverty 10th highest · 2024 | 14.0% U.S. 12.1% | 12.1% | 10th highest | 2024 |
| Median rent, a month 10th highest · 2024* | $1,621 U.S. $1,413 | $1,413 | 10th highest | 2024* |
| Unemployment rate, three-month average Tied for 14th highest · June–August 2026 | 4.4% U.S. 4.1% | 4.1% | Tied for 14th highest | June–August 2026 |
| Median household income 16th highest · 2024 | $85,768 U.S. $81,604 | $81,604 | 16th highest | 2024 |
| Household debt per person with a credit report 26th highest · End of 2025 | $59,420 U.S. $63,200 | $63,200 | 26th highest | End of 2025 |
| Bankruptcy filings per 100,000 residents (2024 population) 20th lowest · 2025 | 116.7 U.S. 167.1 | 167.1 | 20th lowest | 2025 |
| Population change since 2020 Tied for 4th lowest · 2025 | −0.6% U.S. 3.1% | 3.1% | Tied for 4th lowest | 2025 |
| People with a debt in collections 4th lowest · Early 2025 | 8.1% U.S. 13.2% | 13.2% | 4th lowest | Early 2025 |
| Homes lived in by their owners 2nd lowest · 2024* | 54.3% U.S. 65.2% | 65.2% | 2nd lowest | 2024* |
Each rank is New York’s place among the 50 states and D.C., counted from the top (“highest”) or from the bottom (“lowest”). * Census five-year survey, 2020 to 2024. Population: Census Bureau estimates; for the U.S. we total the 50 states and D.C. together. Debts: Federal Reserve Bank of New York (dollars late and debt per person) and Federal Reserve Bank of Philadelphia (people with a credit record; for the U.S. we weight each state by population). Each row’s source is in Sources and method. Download this table: CSV.
Questions about New York
How is New York’s economy doing?
Unemployment is just above the national rate and easing. New York’s rate was 4.3% in August 2026, tied for 16th highest among the 50 states and D.C., against 4.1% for the U.S., and down from 4.5% a year earlier (U.S. Bureau of Labor Statistics). Income per person, $85,552 in 2024, was the 6th highest (U.S. Bureau of Economic Analysis). We don’t measure the state’s total economic output.
Are people leaving New York?
More people move from New York to other states than move in. The net loss was 1,045,769 from July 2020 to July 2025. In the latest year alone, it was 137,586, the largest net loss for its size of any state (U.S. Census Bureau). Arrivals from abroad and births offset most of that loss. New York had 20,002,427 residents in 2025. The Census Bureau doesn’t record why people move.
Which is the poorest county in New York?
Bronx County, the borough of the Bronx. In 2024, 28.7% of its residents lived in poverty, the highest rate of New York’s 62 counties, and its typical household earned $46,486, the lowest (U.S. Census Bureau, Small Area Income and Poverty Estimates). It’s also the most distressed county in the state on our County Distress Index. Kings County, Brooklyn, has the second-highest poverty rate. See all 62 counties, ranked.
What salary do you need to live in New York?
We don’t set one. MIT’s Living Wage Calculator puts basic costs before taxes at $62,167 a year for one adult with no children. For two working parents with two children, it estimates $145,758 (2025 dollars). Those figures are the 4th highest and 7th highest among the 50 states and D.C. overall. Those budgets cover the whole state and only the basics; we don’t hold one for New York City.
What is the poverty line in New York?
The federal poverty guideline for 2026 is $15,960 a year for one person and $33,000 for a family of four (U.S. Department of Health and Human Services). Only Alaska and Hawaii have higher figures, so these are the figures for New York. The 14.0% poverty rate on this page comes from a separate Census Bureau measure.
Is New York’s minimum wage going up in 2027?
No. The New York labor department says the minimum wage stays at $17.00 an hour in New York City, Long Island and Westchester on Jan. 1, 2027. It stays at $16.00 in the rest of the state. A condition in state law that can stop the yearly inflation increase was met (New York labor department).
Cite or reuse New York’s data
Use these figures, with credit, in news stories, research, testimony or grant applications.
State Distress Index
New York
21stmost distressed state
of the 50 states and D.C.
More distressed than 60% of the other states and D.C.
New York is the 21st most financially distressed of the 50 states and D.C. on the State Distress Index, which American Default Research publishes. Its income per person, $85,552 in 2024, was the 6th highest (U.S. Bureau of Economic Analysis). Yet its poverty rate, 14.0%, was the 10th highest, and 28.6% of its renter households paid half or more of their income for housing in 2024, the 4th highest share (U.S. Census Bureau).
Reporters and researchers who want an interview or a custom cut of the data can write to press@americandefault.org
Sources and method
We gather the data, run the numbers and research each state ourselves.
This edition: October 2026 · Next edition expected March 2027
- Late payments, collections and credit scoresFederal Reserve Bank of Philadelphia, Consumer Credit Explorerend of 2019 and early 2025
- Household debt and dollars behindFederal Reserve Bank of New York, Consumer Credit Panel / Equifaxend of 2019 and end of 2025
- Mortgages with little equityFederal Housing Finance Agency, National Mortgage Databasesecond quarter of 2026
- Mortgages 30 to 89 days late; mortgage complaints; medical debts on credit reportsConsumer Financial Protection Bureau: Mortgage Performance Trends; complaint database; Recent changes in medical collections on consumer credit recordsSept. 2025; Oct. 14, 2026; March 2022 to June 2023
- Bankruptcy filingsAdministrative Office of the U.S. Courts, Table F-22001 to 2025
- Unemployment for the state, its counties and the U.S., by month and by yearU.S. Bureau of Labor Statistics, Local Area Unemployment Statistics; State Employment and Unemployment, August 2026Jan. 1990 to Aug. 2026
- Poverty and household income, state and countyCensus Bureau, Small Area Income and Poverty Estimates1989 to 2024
- Renters paying half or more of income for housingCensus Bureau, American Community Survey, one-year estimates2005 to 2024
- Rent, homeownership and owners’ housing costsCensus Bureau, American Community Survey, five-year estimates2020 to 2024
- Population and people moving in and outCensus Bureau, population estimates, 2025 releaseJuly 2020 to July 2025
- Income per personU.S. Bureau of Economic Analysis2024
- SNAPU.S. Department of Agriculture Food and Nutrition AdministrationNov. 2020 to June 2026
- Cost of basic needsMIT Living Wage Calculator2025 dollars
- County scoresAmerican Default Research, County Distress Indexdata through August 2026
- Mortgage help fundU.S. Treasury, Homeowner Assistance Fund; New York State Homes and Community Renewalthrough early 2026; read Oct. 16, 2026
- Foreclosure and homestead lawNew York RPAPL § 1304, § 1306, § 1353 and § 1371; CPLR 3408 and 5206; Department of Financial Services, amounts exempt from judgments; 12 CFR 1024.41as of 2026
- Poverty guidelineU.S. Department of Health and Human Services2026
- Housing counselorsU.S. Department of Housing and Urban DevelopmentOctober 2026
- What changed and what to watchNY State of Health, New York State health department, New York City Rent Guidelines Board, New York City Department of Social Services, New York State Public Service Commission, New York Labor Law § 652, New York labor department, New York State Department of Taxation and Finance, Office of Temporary and Disability Assistance, Office of Governor Kathy Hochul, U.S. Bureau of Labor Statistics release; each item links the page we read (see what changed)Oct. 2025 to Jan. 2027
- County photoAndre Carrotflower, via Wikimedia Commons, CC BY-SA 4.02022
The score has four equal parts: renters’ housing costs; jobs; late payments; and collections and bankruptcy. Each measure is scored against the 50 states and D.C., and a state’s score is the percentage of the other 49 states and D.C. with a lower four-part average; for New York that is 60%. The full method →
We write with AI tools, and Ross Kilburn checks and reviews every page before it's published.
Get the next New York edition by email
One email each time a new New York edition is out; the next is expected in March 2027. Unsubscribe anytime.
Thanks, that helps.