Alabama has had the nation's highest bankruptcy rate every year since 2016: 400.1 per 100,000
Each state is shaded by how distressed its households are, from green (least) to red (most), with data through September 2026. Alabama scores 82 out of 100.
Alabamians file for bankruptcy more than twice as often as Americans overall, and almost all of that gap is Chapter 13 repayment plans. Serious late payments run high too: 23.6% of Alabamians with a credit record had a debt 90 or more days late in early 2025, the 3rd highest share nationally. Jobs are not the problem: the state's 2025 jobless average, 2.9%, was 5th lowest nationally. Alabama’s 9 most distressed counties all sit inside the nation’s 100 most distressed, and eight of them are in the Black Belt.
- Score
- 82/100
- Data through
- September 2026
- Edition
- October 2026
Next edition expected March 2027
How Alabama ranks among the states
On our State Distress Index, Alabama is the 10th most distressed state. What sets it apart is a mismatch. Its residents file for bankruptcy at the highest rate in the country, and a larger share of them are seriously behind on a debt than in nearly every other state. Yet few are out of work, and Alabamians with a credit report owed $48,910 each at the end of 2025, 11th lowest among the states (Federal Reserve Bank of New York). We read that as people falling behind on modest debts on low incomes, not borrowing heavily. That reading is ours; the figures don’t prove it.
What drives the score
The score has four parts. Every measure in a part is ranked against the other states on a scale of 0 to 100, and the part is the average of those ranks. Alabama’s four parts average 69. The score then says how that average compares: a state that scores 80 is more distressed than 80% of the other states and D.C., and Alabama’s average is higher than 82% of theirs, so it scores 82.
- Collections and bankruptcy96The highest bankruptcy filing rate of any state (2025), and 18.7% of people with a debt in collections (early 2025)
- Late payments8812.5% of car-loan borrowers and 17.6% of card borrowers 90 or more days behind (early 2025)
- Renters’ housing costs6024.4% of renter households paid half or more of their income for housing in 2024, below the U.S. 26.1%
- Jobs31A jobless rate of 3.3% over June to August 2026; the U.S. rate was 4.1%
Beside its neighbors
Two of Alabama’s four neighbors score higher: Florida and Mississippi. Georgia sits just below Alabama, and Tennessee, to the north, scores lower and sits in the middle of the states.
- Florida 96
- Mississippi 94
- Georgia 80
- Alabama 82
- Tennessee 52
State Distress Index score, 0 to 100. Heavy bankruptcy filing runs across the region: in 2025 Mississippi had the 2nd highest rate, Tennessee the 3rd highest and Georgia the 5th highest, while Florida had the 17th highest (U.S. Courts, filings per 100,000 residents, 2024 population).
Among the 10 most distressed states for most of the past 20 years
At its worst
Alabama ranked 2nd most distressed, with a score of 98, in the third quarter of 2015, the only quarter it reached that high. Two parts jumped that quarter: renters’ housing costs from 52 to 79 and jobs from 76 to 87. It has never ranked first.
By early 2025
Alabama was tied for 13th, with a score of 74. Its least distressed quarter was the end of 2006, near the start of our history, when it ranked 17th with a score of 68.
Why it moved
Two parts did the moving: jobs and renters’ costs. The collections and bankruptcy part never scored below 88 in any quarter since mid-2006. The jobs part fell from 51 to 25 during 2019, the year Alabama’s unemployment rate dropped below the nation’s (3.2% against 3.7%); it has stayed below every year since. Renters’ costs climbed from 62 to 77 in mid-2023, then fell. Today Alabama scores 82 and ranks 10th (see the note under the chart).
Alabama ranked among the 10 most distressed states in 65 of the 75 quarters since mid-2006, peaking at 2nd in 2015
State Distress Index score each quarter, 0 to 100, third quarter of 2006 to first quarter of 2025.
Why does Alabama have so many bankruptcies?
Alabama has the highest bankruptcy filing rate in the country, and almost all of the gap with the rest of the country is Chapter 13. In 2025, Alabamians filed 20,636 cases, 400.1 for every 100,000 residents using the 2024 population, more than twice the U.S. rate of 167.1 (U.S. Courts). The state has had the highest rate every year since 2016. Of its filings, 70.8% were under Chapter 13, where a filer repays part of the debts through a court-approved plan over three to five years; only Louisiana had a higher share. The reason is debated. One explanation comes from a federal bankruptcy judge in Alabama; the case against it follows.
Bankruptcy filings per 100,000 residents
400.1
U.S. 167.1
Highest among the 50 states and D.C. (2025, using the 2024 population)
Chapter 13 filings per 100,000 residents
283.3
U.S. 60.0
Highest among the 50 states and D.C. (2025, using the 2024 population)
Chapter 7 filings per 100,000 residents
115.0
U.S. 104.3
18th highest among the 50 states and D.C. (2025, using the 2024 population)
Lawyers’ fees, poverty or the courts?
A 2022 article in the Alabama State Bar’s journal argues that many Alabamians are “too broke” for Chapter 7. Its authors, Katarina A. Essenmacher and Judge Henry A. Callaway of the U.S. Bankruptcy Court for the Southern District of Alabama, explain that lawyers ask for Chapter 7 fees up front. Chapter 13 fees can be paid through the plan, so people unable to raise the money may choose Chapter 13. The authors say the state’s “relatively low exemptions and high poverty rate” worsen the problem (The Alabama Lawyer, Dec. 6, 2022).
Fees or poverty alone do not explain the pattern. Mississippi is poorer and files less, with fewer cases under Chapter 13 (332.1 filings per 100,000; 53.6% under Chapter 13). Louisiana has a higher Chapter 13 share, 73.2%, but a much lower filing rate, 222.5 per 100,000 (2025 rates on the 2024 population). Court practices may matter too. A 1997 federal commission traced the consumer repayment plan to Birmingham in the 1930s. It noted that the court districts where the plan began still had high Chapter 13 filing (National Bankruptcy Review Commission, Final Report). No study we found weighs fees, poverty and court practice against each other.
The same article describes how many Chapter 13 cases end:
“About half of the chapter 13 cases in Alabama fail – mostly because the debtors cannot make their plan payments.”
Filing is heaviest in the south and center of the state
Butler County had 843 filings per 100,000 residents in 2025, Lowndes 792 and Chambers 786, each about twice the state’s rate; 91% of Butler’s cases were Chapter 13. In the northeast, DeKalb (186) and Marshall (181) counties filed at less than half the state’s rate, and only 36% of their cases were Chapter 13. Poorer counties tended to file more cases under Chapter 13. In the quarter with the highest poverty rates, 80% of cases were Chapter 13, against 63% in the lowest-poverty quarter (Census Bureau 2023 county populations; U.S. Courts, Table F-5A).
| Year | Filings | Rank by filing rate |
|---|---|---|
| 2015 | 25,672 Rank by filing rate 2nd highest | 2nd highest |
| 2016 | 26,269 Rank by filing rate Highest | Highest |
| 2017 | 27,042 Rank by filing rate Highest | Highest |
| 2018 | 26,846 Rank by filing rate Highest | Highest |
| 2019 | 26,809 Rank by filing rate Highest | Highest |
| 2020 | 18,412 Rank by filing rate Highest | Highest |
| 2021 | 14,940 Rank by filing rate Highest | Highest |
| 2022 | 16,561 Rank by filing rate Highest | Highest |
| 2023 | 17,887 Rank by filing rate Highest | Highest |
| 2024 | 19,395 Rank by filing rate Highest | Highest |
| 2025 | 20,636 Rank by filing rate Highest | Highest |
Bankruptcy cases of every chapter filed in Alabama’s three federal court districts, by calendar year. Filings fell to a low in 2021 and have risen every year since; the 2025 total was the most since 2019, and the 12 months to June 2026 brought 21,688. Rank among the 50 states and D.C. by filings per 100,000 residents, using each year’s Census population estimate (our calculation). For 2025 that is the 2025 estimate, so the rate behind the rank, 397.4, differs slightly from the 400.1 above, which uses the 2024 population. Source: U.S. Courts, Table F-2.
Can wages be garnished in Alabama?
Yes. After a court judgment, a creditor can garnish up to 25% of a person’s weekly pay after taxes, and a week’s pay after taxes at or below 30 times the federal minimum wage can’t be taken (Ala. Code §§ 5-19-15 and 6-10-7; 15 U.S.C. § 1673). For free legal help, see Free help in Alabama.
Is Alabama a poor state?
Yes. Alabama is among the 10 poorest states on poverty, household income and income per person. In 2024, 15.2% of Alabamians lived in poverty, 8th highest among the 50 states and D.C., against 12.1% nationwide, and the typical household earned $66,704, the 7th lowest (Census Bureau, Small Area Income and Poverty Estimates). Income per person, which takes in wages, business profits, investment income and government benefits, was $57,311, the 3rd lowest (Bureau of Economic Analysis). The poverty rate has fallen from its 2014 high but has never dropped to the nation’s.
Residents in poverty
15.2%
U.S. 12.1%
8th highest among the 50 states and D.C. (2024)
Median household income
$66,704
U.S. $81,604
7th lowest among the 50 states and D.C. (2024)
Children in poverty
20.4%
U.S. 15.5%
5th highest among the 50 states and D.C. (2024)
Alabama’s poverty rate has topped the nation’s in every Census estimate since 1989; it peaked at 19.2% in 2014
Share of Alabamians and of all Americans with incomes below the poverty line, 1989 to 2024. No points for 1990 to 1992 or 1994, when the Census Bureau published no state estimates.
Fewer Alabamians get SNAP than a year ago
In June 2026, 648,952 Alabamians, 12.6% of residents, got SNAP food benefits, 11th highest among the 50 states and D.C. and above the U.S. share of 10.7% (U.S. Department of Agriculture). That was 11.5% fewer than the 732,974 of June 2025, and most of the fall came after October 2025, when the count was 722,477. Federal SNAP rules changed under a 2025 law, but we found no date for when Alabama began applying them, so we can’t say how much of the drop they explain. A falling count isn’t falling need: the state’s child poverty rate is 5th highest.
To apply for SNAP: Alabama Department of Human Resources, food assistance →
Fewer paychecks, more benefits: where Alabama’s income comes from
Wages and salaries made up 46.5% of all income in Alabama in 2024, against 49.7% nationwide. Government benefits such as Social Security, Medicare and veterans’ benefits made up 24.1%, 5th highest among the 50 states and D.C. (Bureau of Economic Analysis). A larger share of Alabamians than of Americans overall live with a disability or have no high school diploma.
| Measure | Alabama | U.S. | Rank |
|---|---|---|---|
| Residents with a disability 7th highest | 16.5% U.S. 13.3% | 13.3% | 7th highest |
| Adults without a high school diploma 8th highest | 11.4% U.S. 10.4% | 10.4% | 8th highest |
| Residents without health insurance 14th highest | 9.2% U.S. 8.4% | 8.4% | 14th highest |
| Residents 65 and older 25th highest | 17.8% U.S. 17.2% | 17.2% | 25th highest |
Rank 1 is the highest share among the 50 states and D.C. Source: Census Bureau, American Community Survey, five-year figures for 2020 to 2024.
Alabama’s poorest and most distressed counties
Bullock County, southeast of Montgomery, is Alabama’s poorest: in 2024 its poverty rate was 36.7%, the highest of any of the state’s 67 counties (Census Bureau, Small Area Income and Poverty Estimates). Dallas County, home to Selma, is the most distressed on our County Distress Index, which scores every U.S. county on the strain in its household finances; that puts it 4th most distressed among 3,144 U.S. counties. Alabama’s 9 most distressed counties are all among the country’s 100 most distressed (the 100 most distressed U.S. counties). Shelby County, south of Birmingham, is the least distressed in the state.
Alabama’s most distressed counties stretch across the Black Belt in the middle of the state; the least distressed are Shelby, Madison, Limestone, Baldwin and Elmore
County Distress Index score, 0 to 100, for each of Alabama’s 67 counties, with data through August 2026.
Loading the county map…
The county map could not be loaded. Every county is in the lists on this page.
Most distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 1 | Dallas | 99 | 29.6% |
| 2 | Wilcox | 99 | 34.0% |
| 3 | Greene | 99 | 33.7% |
| 4 | Perry | 99 | 29.8% |
| 5 | Russell | 98 | 20.2% |
| 6 | Conecuh | 97 | 22.7% |
| 7 | Lowndes | 97 | 25.0% |
| 8 | Macon | 97 | 30.8% |
| 9 | Sumter | 97 | 32.6% |
| 10 | Hale | 96 | 21.0% |
Least distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 63 | Elmore | 44 | 11.1% |
| 64 | Baldwin | 43 | 10.5% |
| 65 | Limestone | 38 | 10.3% |
| 66 | Madison | 36 | 9.6% |
| 67 | Shelby | 21 | 6.8% |
Rank in Alabama, 1 = most distressed. Ranks follow unrounded scores, so counties showing the same score can still rank apart: Dallas, Wilcox, Greene and Perry show the same printed score, and so do Conecuh, Lowndes, Macon and Sumter. Poverty rates are the Census Bureau’s for 2024.
Every county, by score
Of Alabama’s 67 counties, 33 score 80 or more, and 42.8% of Alabamians live in one of them. The group takes in three of the state’s biggest counties: Montgomery, home to the capital, ranks 17th most distressed in the state, Mobile 24th and Jefferson, home to Birmingham, 32nd. Madison, around Huntsville, ranks 66th, among the least distressed. Only Shelby scores below 30.
33 score 80–100
Dallas, Wilcox, Greene, Perry, Russell, Conecuh, Lowndes, Macon, Sumter, Hale, Bullock, Pike, Monroe, Barbour, Butler, Choctaw, Montgomery, Bibb, Marengo, Pickens, Clarke, Chambers, Calhoun, Mobile, Escambia, Talladega, Crenshaw, Geneva, Etowah, Randolph, Covington, Jefferson, Marion
12 score 70–79
Fayette, Dale, Coosa, Houston, Lamar, Clay, Walker, Tuscaloosa, Colbert, Chilton, DeKalb, Tallapoosa
16 score 50–69
Winston, Jackson, Washington, Cherokee, Franklin, Henry, Lee, Morgan, Blount, Lawrence, Cleburne, Marshall, Cullman, Coffee, Lauderdale, Autauga
1 score 0–29
Poorest isn’t the same as most distressed
Our county score has five parts, one more than the state score. Poverty is one of five measures in one of them, alongside child poverty, disability, health insurance and household income. The other four parts cover late payments, collections and bankruptcy, jobs, and housing costs. Bullock County, the poorest, ranks 11th most distressed; its jobs score is the lowest among the state’s 20 most distressed counties. Russell County, across the Chattahoochee River from Columbus, Georgia, ranks 5th on distress though its poverty rate is tied for 21st highest in the state; it scores near the top on collections and bankruptcy and on renters’ costs. Mobile and Jefferson, two of the three largest counties, also rank higher on distress than on poverty: Mobile is 24th on distress and 44th highest on poverty, Jefferson 32nd and 55th highest. Lists built on another Census survey or other years can name a different poorest county; these are the Census Bureau’s 2024 county estimates.
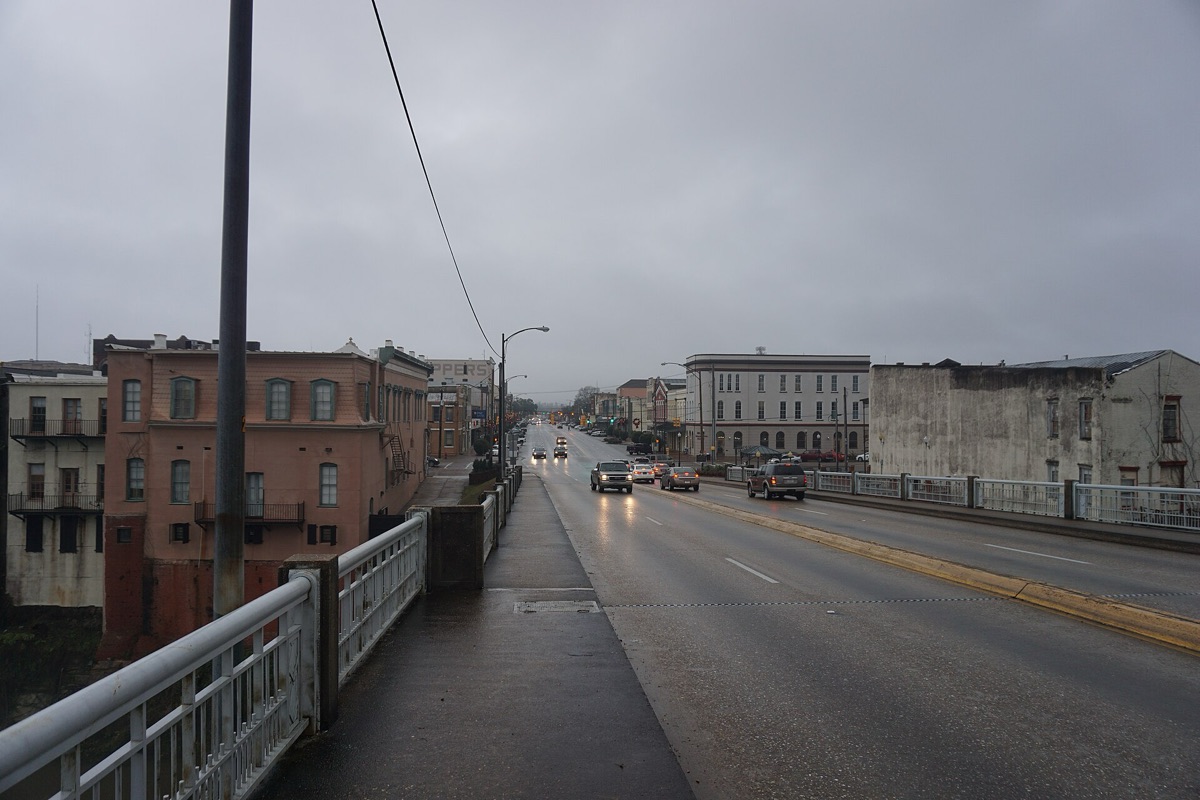
Broad Street in Selma, seen from the Edmund Pettus Bridge in December 2018. Selma is the seat of Dallas County, the most distressed county in Alabama. In 2024, 29.6% of the county’s residents lived in poverty, and its typical household earned $41,409 (Census Bureau).
Sources: U.S. Census Bureau; American Default Research. Photo: Michael Barera, via Wikimedia Commons, CC BY-SA 4.0.

The Black Belt holds most of Alabama’s deepest distress
The Encyclopedia of Alabama counts 17 counties as the traditional Black Belt, a band across the middle of the state named for its dark soil. Every one of them scores 88 or more on our County Distress Index, and eight of the 9 Alabama counties in the country’s 100 most distressed are Black Belt counties; Conecuh is the other. Half of the Black Belt counties had poverty rates of 25.0% or higher in 2024, against 15.2% for the state. Other definitions of the region count fewer or more counties (Encyclopedia of Alabama).
American Default Research, County Distress Index; U.S. Census Bureau, Small Area Income and Poverty Estimates; Encyclopedia of Alabama.
Are Alabamians behind on their bills?
Yes, more than people in all but a few states. In early 2025, 23.6% of Alabamians with a credit record had at least one debt 90 or more days past due. That was 3rd highest among the 50 states and D.C. in the Philadelphia Fed figures. The U.S. share was 17.2%, calculated as the population-weighted average of the states (Federal Reserve Bank of Philadelphia). These are household debts, such as cards, car loans and mortgages, not the state government’s debt.
Alabama’s rank among the 50 states and D.C., 1 = the highest share: auto 3rd, collections 4th, card 5th, mortgage tied for 6th. The U.S. bars are our average of the states, weighted by population.
The share of Alabamians with a debt in collections was lower in early 2025, 18.7%, than at the end of 2019, 28.5%. That isn’t a clean sign that fewer people are struggling. The share was already falling before 2022 (24.1% in early 2022), and it has edged up since the end of 2023 (17.3%). Reporting changed too. In 2022 the three national credit bureaus said they would stop reporting certain medical debts. Nationwide, the share of people with a medical collection on their credit record fell from about 14% in March 2022 to about 5% in June 2023 (Consumer Financial Protection Bureau).
Counted in dollars, car loans stand out
The Federal Reserve Bank of New York counts dollars rather than borrowers: what part of the money owed is 90 or more days past due. On car loans Alabama is well above the U.S., with 6.6% of balances seriously late at the end of 2025. That was tied for 4th highest among the 50 states and D.C. in 2025. On cards, counted in dollars, it is slightly below the U.S., even though a larger share of Alabama card borrowers are behind.
| Loan type | Alabama | U.S. | Alabama 2019 | U.S. 2019 |
|---|---|---|---|---|
| Auto loan | 6.6% End of 2025 U.S. 5.2% Alabama 2019 6.6% · U.S. 2019 4.9% | 5.2% | 6.6% | 4.9% |
| Credit card | 12.2% End of 2025 U.S. 12.4% Alabama 2019 8.4% · U.S. 2019 8.1% | 12.4% | 8.4% | 8.1% |
| Mortgage | 1.2% End of 2025 U.S. 0.9% Alabama 2019 0.9% · U.S. 2019 1.0% | 0.9% | 0.9% | 1.0% |
Percent of balances 90 or more days past due at the end of 2025 and the end of 2019 (Federal Reserve Bank of New York, Consumer Credit Panel / Equifax). These shares count dollars, not people, so they don’t line up with the Philadelphia Fed bars above, and they keep old debts that lenders have written off but still report.
Other signs of strain
Early-stage mortgage trouble, low credit scores, cards near their limit and mortgages with little equity (the part of a home’s value the owner doesn’t owe to a lender) are all more common in Alabama than across the country.
| Measure | Alabama | U.S. | Rank |
|---|---|---|---|
| Mortgages 30 to 89 days late, Sept. 2025 4th highest | 2.4% U.S. 1.6% | 1.6% | 4th highest |
| People with a credit score under 620, early 2025 4th highest | 19.5% U.S. 13.8% | 13.8% | 4th highest |
| Card users near their credit limit, early 2025 3rd highest | 33.9% U.S. 26.9% | 26.9% | 3rd highest |
| Mortgages with under 10% equity, mid-2026 10th highest | 6.5% U.S. 4.7% | 4.7% | 10th highest |
Rank 1 is the highest share among the 50 states and D.C. Mortgages 30 to 89 days late: Consumer Financial Protection Bureau. Credit scores and card use: Federal Reserve Bank of Philadelphia; we made its U.S. figure by averaging the states by population. Equity: Federal Housing Finance Agency.
What changed in Alabama in the past year
-
Oct. 7, 2026
Hurricane Isaias brings a state of emergency and later tax deadlines
Gov. Kay Ivey declared a state of emergency for 40 counties as the storm approached and ordered visitors off the coast of south Baldwin County and Dauphin Island. The Federal Emergency Management Agency issued an emergency declaration on Oct. 9 for Baldwin, Escambia and Mobile counties and the Poarch Band of Creek Indians (FEMA). People in 40 counties, every Black Belt county among them, have until Feb. 4, 2027 for many federal tax returns and payments that came due on or after Oct. 7 (Internal Revenue Service, Oct. 14, 2026). As of Oct. 15, we had found no official count of the damage.
-
June 1, 2026
A new law holds electric base rates until 2029
Under House Bill 475, the base rates that each regulated electric company has in place on Oct. 1, 2026 can’t be raised before Jan. 1, 2029. The freeze covers base rates, not every charge on a bill, so bills can still change. The law also enlarges the Public Service Commission to seven members, with four appointed commissioners starting in January 2027, and creates a Secretary of Energy in the governor’s cabinet from Jan. 19, 2027.
-
June 1, 2026
Older and disabled homeowners can protect more of their home’s value
Under House Bill 96, a homeowner 62 or older or with a disability can now protect up to $56,400 of a home’s value from being taken to pay a court judgment. That protection is the homestead exemption; the 2022 article cited in the bankruptcy section calls Alabama’s exemptions “relatively low.”
-
May 1, 2026
Alabama suspended its state grocery tax for two months
The state’s share of the sales tax on food was suspended from May 1 through June 30, 2026 under Act 2026-604; city and county taxes on food still applied. The state rate on food had been set to drop from 3% to 2% on Sept. 1, 2025 (Alabama Department of Revenue, July 2, 2025); we found no later state notice confirming the 2% rate.
-
Jan. 28, 2026
Fewer Alabamians sign up for marketplace health plans
Alabamians picked 455,776 plans on HealthCare.gov for 2026, down 4.6% from 477,838 for 2025 (our calculation from the Centers for Medicare & Medicaid Services’ counts; CMS, 2025 count). A plan selection is a sign-up; it doesn’t show who went on to pay for coverage.
-
Nov. 1, 2025
November SNAP benefits are held back in the federal shutdown
Following U.S. Department of Agriculture guidance, the state said it would issue no new SNAP benefits for November until federal funding came through; money already on benefit cards could still be spent.
Is Alabama expensive to live in?
Not for renters, by the measures we hold, though incomes are low too. The typical Alabama rent over 2020 to 2024 was $1,007 a month, the 9th lowest of the 50 states and D.C.; for the U.S. it was $1,413 (Census Bureau). In 2024, 24.4% of Alabama renter households paid half or more of their income for rent and utilities, below the U.S. share of 26.1%. We don’t track prices for food, homes, insurance or electricity, so we can’t rank Alabama’s overall cost of living.
Median rent, a month
$1,007
U.S. $1,413
9th lowest among the 50 states and D.C. (2020 to 2024)
Renters spending half or more of income on housing
24.4%
U.S. 26.1%
Tied for 26th highest among the 50 states and D.C. (2024)
Basic yearly budget, one adult
$43,814
10th lowest among the 50 states and D.C. (MIT, 2025 dollars)
The share of Alabama renters paying half or more of their income for housing fell two years in a row and has been below the nation’s since 2023
Renter households whose rent and utilities take half or more of their income, Alabama and the U.S., 2005 to 2024, in percent. No 2020 point: the Census Bureau didn’t publish its usual one-year estimates for that year.
Groceries and power bills
The state sales tax on food was set to fall from 3% to 2% on Sept. 1, 2025. We found no later state notice confirming that rate. The state’s share was suspended for May and June 2026; city and county taxes on groceries still applied. A 2026 law keeps electric companies from raising base rates before 2029, though the freeze covers base rates, not every charge on a bill (see what changed).
What a basic budget costs
By the MIT Living Wage Calculator, one adult with no children needs $43,814 a year before taxes to cover basic needs in Alabama. That is 10th lowest among the 50 states and D.C. in 2025 dollars. A two-earner family with two children needs $99,458 a year.
What is Alabama’s unemployment rate?
Alabama’s unemployment rate was 3.4% in August 2026, below the U.S. rate of 4.1% but up from 2.8% a year earlier (Bureau of Labor Statistics). Over all of 2025 it averaged 2.9%, the 5th lowest of the 50 states and D.C., and it has been below the national rate every year since 2019. The lowest yearly rate in figures back to 1990, 2.5%, came in 2022 and again in 2023. A low rate leaves out people who aren’t looking for work, and we don’t hold the state’s share of adults in the workforce.
Unemployment rate, August 2026
3.4%
U.S. 4.1%
Up from 2.8% in August 2025
Unemployment rate, 2025 average
2.9%
U.S. 4.3%
5th lowest among the 50 states and D.C.
Alabama’s unemployment rate has been below the nation’s every month since December 2018
Monthly unemployment rate, seasonally adjusted, Alabama and the United States, January 1990 to August 2026. No October 2025 figures: none were published during the federal shutdown.
Filing for unemployment
Unemployment benefits are claimed through the Alabama Department of Workforce.
Joblessness is highest in Perry, Greene and Monroe counties
| County | Rate |
|---|---|
| Perry | 7.0% |
| Greene | 6.8% |
| Monroe | 6.6% |
| Wilcox | 6.4% |
| Dallas | 5.6% |
| Mobile | 4.4% |
| Jefferson | 3.8% |
| Madison | 3.0% |
| Shelby | 2.8% |
Unemployment rate in selected counties, August 2026, not adjusted for seasonal swings. Perry County’s rate was tied for 55th highest among the 3,143 U.S. counties with a rate; Shelby and Chambers had Alabama’s lowest. Source: Bureau of Labor Statistics.
How foreclosure works in Alabama
Foreclosures in Alabama usually don’t go through a court. Under federal servicing rules, the process generally can’t begin until a home loan is more than 120 days past due. Using the power of sale written into most mortgages, the lender then advertises the sale in a county newspaper once a week for three weeks (Ala. Code § 35-10-13). For a home on which a homestead exemption was claimed that tax year, it must also mail the owner a notice at least 30 days before the sale (Ala. Code § 6-5-248). After the sale, the former owner can buy the home back within 180 days for a home with that exemption, or within one year for other property (Ala. Code § 6-5-248). The lender can sue for any balance the sale leaves unpaid.
- Goes through a court
- Usually not
- Sale advertised
- 3 weeks
- Mailed notice for a homestead
- 30 days
- Buying back a homestead after the sale
- 180 days
- Buying back other property
- 1 year
- Lender can seek the unpaid balance
- Yes
What the law says. Sources: Ala. Code §§ 35-10-12, 35-10-13 and 6-5-248; federal rule 12 CFR 1024.41. How foreclosure works in Alabama →
Alabama’s share of the federal Homeowner Assistance Fund was $125.7 million, and the program had helped 6,254 homeowners through early 2026 (U.S. Treasury; the count includes homeowners who got housing counseling).
Payment problems top Alabama’s mortgage complaints
Alabamians have sent the Consumer Financial Protection Bureau 4,367 complaints about mortgages since the bureau began taking them in December 2011. Trouble during the payment process came up most (1,322), ahead of loan modifications, collection and foreclosure (760) and loan servicing, payments or escrow (703).
- Oct. 2, 2026 The Bank of New York Mellon Corporation Trouble during payment process: Trying to communicate with the company to fix an issue while managing or servicing your loan Closed with explanation
- Sept. 29, 2026 Truhome Solutions, LLC Struggling to pay mortgage: Foreclosure Closed with explanation
- Sept. 29, 2026 Selene Finance Trouble during payment process: Payment process Closed with explanation
- Sept. 25, 2026 Carrington Mortgage Struggling to pay mortgage: An existing modification, forbearance plan, short sale, or other loss mitigation relief In progress
- Sept. 25, 2026 AmeriHome Mortgage Trouble during payment process: Payment process In progress
- Sept. 23, 2026 Lakeview Loan Servicing Struggling to pay mortgage: Applying for or obtaining a modification, forbearance plan, short sale, or deed-in-lieu Closed with explanation
- Sept. 22, 2026 Carrington Mortgage Trouble during payment process: Escrow, taxes, or insurance Closed with explanation
- Sept. 21, 2026 Southstate Bank Corporation Struggling to pay mortgage: An existing modification, forbearance plan, short sale, or other loss mitigation relief In progress
- Sept. 21, 2026 Select Portfolio Servicing Struggling to pay mortgage: Trying to communicate with the company to fix an issue related to modification, forbearance, short sale, deed-in-lieu, bankruptcy, or foreclosure Closed with explanation
- Sept. 21, 2026 Village Capital Struggling to pay mortgage: Foreclosure Closed with explanation
The 10 most recent Alabama complaints about paying a mortgage or getting help with one, newest first, from the Consumer Financial Protection Bureau’s public record as of Oct. 14, 2026. We leave out complaints about getting a new loan and any naming a credit reporting company. The bureau publishes what people tell it without checking each account. Every Alabama mortgage complaint at the Consumer Financial Protection Bureau →
What to watch before the next edition
Scheduled dates between now and early 2029 that reach Alabama household budgets, nearest first.
-
Oct. 20, 2026
September unemployment rates for the states
The Bureau of Labor Statistics publishes state unemployment rates for September. Alabama’s August rate was 3.4%.
U.S. Bureau of Labor Statistics, release schedule for October 2026
-
January 2027
A new SNAP and TANF system is planned for every county
The Department of Human Resources began testing ACES, its new eligibility system for SNAP and TANF (cash help for families), on Oct. 5 in Montgomery, Elmore, Tuscaloosa, Dallas and Talladega counties and plans, tentatively, to switch the whole state over in January. The department says benefit dates and amounts won’t change.
-
Feb. 4, 2027
Postponed federal tax deadlines after Hurricane Isaias
In the 40 counties the IRS named, many federal returns and payments that came due on or after Oct. 7, 2026 can be filed or paid by this date.
-
Jan. 1, 2029
The earliest date electric base rates can rise
Under House Bill 475, base rates in place on Oct. 1, 2026 can’t go up before this date.
Where Alabama ranks highest and lowest
| Measure | Alabama | U.S. | Rank | Latest data |
|---|---|---|---|---|
| Bankruptcy filings per 100,000 residents (2024 population) Highest · 2025 | 400.1 U.S. 167.1 | 167.1 | Highest | 2025 |
| Share of bankruptcy filings under Chapter 13 2nd highest · 2025 | 70.8% U.S. 35.9% | 35.9% | 2nd highest | 2025 |
| People with a debt 90+ days late 3rd highest · Early 2025 | 23.6% U.S. 17.2% | 17.2% | 3rd highest | Early 2025 |
| Auto loan borrowers 90+ days late 3rd highest · Early 2025 | 12.5% U.S. 8.5% | 8.5% | 3rd highest | Early 2025 |
| People with a debt in collections 4th highest · Early 2025 | 18.7% U.S. 13.2% | 13.2% | 4th highest | Early 2025 |
| Mortgages 30 to 89 days late 4th highest · Sept. 2025 | 2.4% U.S. 1.6% | 1.6% | 4th highest | Sept. 2025 |
| Share of income from government benefits 5th highest · 2024 | 24.1% U.S. 18.3% | 18.3% | 5th highest | 2024 |
| Children in poverty 5th highest · 2024 | 20.4% U.S. 15.5% | 15.5% | 5th highest | 2024 |
| Residents in poverty 8th highest · 2024 | 15.2% U.S. 12.1% | 12.1% | 8th highest | 2024 |
| Residents getting SNAP food benefits 11th highest · June 2026 | 12.6% U.S. 10.7% | 10.7% | 11th highest | June 2026 |
| Renters spending half or more of income on housing Tied for 26th highest · 2024 | 24.4% U.S. 26.1% | 26.1% | Tied for 26th highest | 2024 |
| Unemployment rate, three-month average Tied for 11th lowest · June–August 2026 | 3.3% U.S. 4.1% | 4.1% | Tied for 11th lowest | June–August 2026 |
| Unemployment rate, yearly average 5th lowest · 2025 | 2.9% U.S. 4.3% | 4.3% | 5th lowest | 2025 |
| Household debt per person with a credit report 11th lowest · End of 2025 | $48,910 U.S. $63,200 | $63,200 | 11th lowest | End of 2025 |
| Median household income 7th lowest · 2024 | $66,704 U.S. $81,604 | $81,604 | 7th lowest | 2024 |
| Income per person 3rd lowest · 2024 | $57,311 U.S. $73,204 | $73,204 | 3rd lowest | 2024 |
Ranks run across the 50 states and D.C.; a “highest” rank starts from the top of the list and a “lowest” rank from its foot. Late payments and collections come from the Federal Reserve Bank of Philadelphia and cover people who have a credit record; we averaged the states, weighting each by its population, to get its U.S. number. Every measure’s producer is named in Sources and method. Download this table: CSV.
Questions about Alabama
Is Alabama a poor state?
Yes, among the poorest. Alabama’s 2024 poverty rate, 15.2%, was 8th highest among the 50 states and D.C., and its median household income, $66,704, was the 7th lowest (U.S. Census Bureau, Small Area Income and Poverty Estimates). Measured per person, income was $57,311, the 3rd lowest (U.S. Bureau of Economic Analysis, 2024).
Why does Alabama have so many bankruptcies?
Alabama had 400.1 filings per 100,000 residents in 2025 (using the 2024 population), the highest rate of any state, and 70.8% were Chapter 13 repayment plans (U.S. Courts). A federal bankruptcy judge in Alabama has written that people who can’t pay a Chapter 7 lawyer up front file Chapter 13, where fees go through the plan. Poverty and long-standing court habits may also play a part; no study we found settles it. More on bankruptcy in Alabama →
Which Alabama county is the poorest?
Bullock County, with a 2024 poverty rate of 36.7%, the highest of the state’s 67 counties (U.S. Census Bureau, Small Area Income and Poverty Estimates). Wilcox and Greene come next. On our County Distress Index, Dallas County, home to Selma, is the most distressed.
Is Alabama cheap to live in?
Rent is cheap: the median was $1,007 a month from 2020 to 2024, the 9th lowest of the 50 states and D.C. (U.S. Census Bureau). Incomes are low too, and 24.4% of Alabama renters paid half or more of their income for housing in 2024. We don’t measure food, home, insurance or electricity prices, so we don’t rank the overall cost of living.
What is the poverty line for an Alabama family?
The federal poverty guideline covers Alabama. For 2026 it is $15,960 a year for a person living alone and $33,000 for a household of four; only Alaska and Hawaii have their own figures (U.S. Department of Health and Human Services).
How long do you have to buy a house back after foreclosure in Alabama?
It depends on the home. If a homestead exemption was claimed on it for the tax year of the sale, the former owner has 180 days after the sale; for other property, one year (Ala. Code § 6-5-248). How foreclosure works in Alabama →
Cite or reuse Alabama’s data
Quote these figures in reporting, grant applications or policy work; please credit American Default Research.
State Distress Index
Alabama
10thmost distressed state
of the 50 states and D.C.
More distressed than 82% of the other states and D.C.
Alabama is the 10th most financially distressed of the 50 states and D.C. on the State Distress Index, which American Default Research publishes. Alabamians filed for bankruptcy at a rate of 400.1 per 100,000 residents in 2025, measured against the 2024 population, the highest of any state, and 70.8% of the filings were under Chapter 13 (U.S. Courts). In early 2025, 23.6% of Alabamians with a credit record had a debt 90 or more days late, 3rd highest in the country (Federal Reserve Bank of Philadelphia). The state’s poverty rate was 15.2% in 2024, 8th highest (U.S. Census Bureau, Small Area Income and Poverty Estimates).
Questions, interviews or a custom cut of the data: press@americandefault.org
Sources and method
We gather the data, run the numbers and research each state ourselves.
This edition: October 2026 · Next edition expected March 2027
- Debts 90 or more days late, collections, credit scores and cards near their limitFederal Reserve Bank of Philadelphia, Consumer Credit Explorerend of 2019 and early 2025
- Household debt and balances 90 or more days lateFederal Reserve Bank of New York, Consumer Credit Panel / Equifaxend of 2019 and end of 2025
- Mortgages with little equityFederal Housing Finance Agency, National Mortgage Databasesecond quarter of 2026
- Mortgages 30 to 89 days late; mortgage complaints; medical debts on credit reportsConsumer Financial Protection Bureau: Mortgage Performance Trends; complaint database; Recent changes in medical collections on consumer credit recordsSept. 2025; Oct. 14, 2026; March 2022 to June 2023
- Bankruptcy filings by state, chapter and yearU.S. Courts, Table F-22015 to June 2026
- Bankruptcy filings by countyU.S. Courts, Table F-5A2025
- Why so many Alabamians file Chapter 13Katarina A. Essenmacher and Judge Henry A. Callaway, “Too Broke to File Bankruptcy,” The Alabama Lawyer, Alabama State Bar; National Bankruptcy Review Commission, Final Report, chapter 1Dec. 6, 2022; Oct. 20, 1997
- Unemployment, state, county and nationalU.S. Bureau of Labor Statistics, Local Area Unemployment StatisticsJan. 1990 to Aug. 2026
- Poverty and incomeCensus Bureau, Small Area Income and Poverty Estimates1989 to 2024
- Renters spending half or more of income on housingCensus Bureau, American Community Survey 1-year2005 to 2024
- Rent, disability, schooling, health insurance and ageCensus Bureau, American Community Survey 5-year2020 to 2024
- Population for filing ratesCensus Bureau, population estimates2015 to 2025; counties 2023
- Income per person and where it comes fromU.S. Bureau of Economic Analysis2024
- SNAPU.S. Department of Agriculture Food and Nutrition AdministrationJune 2025 to June 2026
- Cost of a basic budgetMIT Living Wage Calculator2025 dollars
- Mortgage help fundU.S. Treasury, Homeowner Assistance Fundthrough early 2026
- Foreclosure and garnishment lawCode of Alabama (§§ 5-19-15, 6-5-248, 6-10-7, 35-10-12 and 35-10-13); 15 U.S.C. § 1673; 12 CFR 1024.41as of 2026
- Poverty guidelineU.S. Department of Health and Human Services2026
- Housing counselorsU.S. Department of Housing and Urban DevelopmentOctober 2026
- Black Belt countiesEncyclopedia of Alabama, Black Belt Region in Alabamaas read Oct. 2026
- What changed and what to watchOffice of Gov. Kay Ivey, Federal Emergency Management Agency, Internal Revenue Service, Alabama Legislature: HB475 and HB96, Alabama Department of Revenue, Centers for Medicare & Medicaid Services, Alabama Department of Human Resources, U.S. Bureau of Labor Statistics release schedule; each item links to the page we read (see what changed)Oct. 2025 to Jan. 2029
- County photoMichael Barera, via Wikimedia Commons2018
Four equal parts make up the score: late payments; collections and bankruptcy; jobs; and renters’ housing costs. Each measure is ranked against the 50 states and D.C.; the score is the share of the other 50 places whose average of the four parts is below Alabama’s. The full method →
We write with AI tools, and Ross Kilburn checks and reviews every page before it's published.
Get the next Alabama edition by email
One email each time a new Alabama edition is out; the next is expected in March 2027. Unsubscribe anytime.
Thanks, that helps.