Oregon ties for the top state jobless rate, 5.1%, yet is 10th lowest for people behind on debt
Each state is shaded by how distressed its households are, from green (least) to red (most), with data through September 2026. Oregon scores 64 out of 100.
Oregon's unemployment rate has topped the nation's in every month published since August 2024. Bankruptcy filings rose 24.4% in 2025, a faster climb than in any state. Nearly half of Oregon renter households, 49.5%, paid at least 30% of their income for housing over 2020 to 2024. Klamath, Lake, Josephine and Lincoln counties carry the state's highest distress; Hood River and Washington counties the lowest.
- Score
- 64/100
- Data through
- September 2026
- Edition
- October 2026
Next edition expected March 2027
How Oregon ranks among the states
Oregon is the 19th most distressed state on our State Distress Index. Its place comes from a split that most readers wouldn’t expect. On debts, Oregonians are in better shape than most. In early 2025, the share of those with a credit record who were 90 or more days late on a payment was 10th lowest among the 50 states and D.C. (Federal Reserve Bank of Philadelphia). On jobs and rent they are not. The state’s unemployment rate in August 2026 was tied for 2nd highest among the 50 states and D.C. overall. A larger share of renters spend 30% or more of their income on housing than in all but a handful of states. What lies behind the high unemployment is less clear; the possibilities, and the case against each, are in the jobs section.
What drives the score
Four parts make up the score, each running from 0 to 100 according to where Oregon’s measures fall among the 50 states and D.C. Oregon’s four parts average 62. The score turns that average into a share: Oregon’s average is higher than those of 64% of the other states and D.C., so Oregon scores 64.
- Jobs94An unemployment rate of 5.2%, averaged over June to August 2026; U.S. 4.1%
- Renters’ housing costs83In 2024, 26.6% of renter households paid half or more of their income for housing; U.S. 26.1%
- Collections and bankruptcy46192.0 bankruptcy filings per 100,000 residents in 2025 (using the 2024 population), and 9.5% of people with a debt in collections in early 2025
- Late payments249.8% of card borrowers and 5.8% of car-loan borrowers 90 or more days behind in early 2025, both under the U.S. shares
Beside its neighbors
Two of Oregon’s four neighbors score higher: Nevada and California. Washington and Idaho score lower.
State Distress Index score, 0 to 100. High unemployment isn’t Oregon’s alone in the region: in August 2026 the rate was 5.1% in California, 4.9% in Washington and 4.8% in Nevada, while Idaho’s was 3.6% (Bureau of Labor Statistics).
Oregon’s score has climbed since 2021, mostly on jobs
At its worst
Oregon ranked 12th most distressed, with a score of 78, in the second quarter of 2010. That was the only quarter it reached so high, and it has never ranked higher.
By early 2025
Oregon ranked 19th most distressed, with a score of 64, and it holds that rank and score today. Its least distressed stretch came in 2020 and 2021: in five quarters of those two years it scored 36 and ranked 33rd.
Why it moved
Mostly jobs. At the end of 2019 Oregon scored 42 and ranked 30th. Since then the jobs part has climbed from 49 to 94, while the late payments part rose from 12 to 24, collections and bankruptcy from 38 to 46 and renters’ costs from 72 to 83. The sharpest rises came in the second half of 2022, when the jobs part went from 68 to 88, and in mid-2023, when renters’ costs went from 75 to 87 in a single quarter.
Oregon’s score bottomed out at 36 in 2020 and 2021, then rose to 64 by early 2025, its highest since 2014
Oregon’s State Distress Index score, 0 to 100, every quarter from mid-2006 through early 2025.
Is Oregon expensive to live in?
For renters, yes: rent costs more than in most states and takes a bigger share of income. The typical Oregon rent over 2020 to 2024 was $1,525 a month, 14th highest among the 50 states and D.C., against $1,413 for the U.S. (Census Bureau). Rent is high next to what people earn: 49.5% of Oregon renter households paid 30% or more of their income for rent and utilities, 6th highest. Homeowners feel it too, with 25.1% spending 30% or more of their income on housing, 9th highest. We don’t track prices for food, gas, insurance or electricity, so we can’t rank Oregon’s overall cost of living.
Median rent, a month
$1,525
U.S. $1,413
14th highest among the 50 states and D.C. (2020 to 2024)
Renters spending 30% or more of income on housing
49.5%
U.S. 47.6%
6th highest among the 50 states and D.C. (2020 to 2024)
Basic yearly budget, one adult
$55,047
8th highest among the 50 states and D.C. (MIT, 2025 dollars)
In every year with Census figures since 2019, Oregon renters have been more likely than U.S. renters to pay half or more of their income for housing
Percent of renter households spending half or more of their income on rent and utilities, Oregon and the U.S., 2005 to 2024. The line skips 2020, when the Census Bureau put out no regular one-year estimates.
A cap on yearly rent increases
Oregon’s rent stabilization law (ORS 90.323) caps how much the rent on most covered homes can go up in a year: 9.5% in 2026 and 10% in 2027. The state works out the cap each year under ORS 90.324, and its Office of Economic Analysis publishes it (rent stabilization). Electric bills moved both ways in 2026 for Portland General Electric’s customers (see what changed).
What a basic budget costs
The MIT Living Wage Calculator puts yearly basic costs before taxes at $55,047 for one adult with no children. That is 8th highest among the 50 states and D.C. For two working adults with two children, it estimates $140,491, 10th highest (2025 dollars). Those budgets cover basic needs, not a comfortable living. Rent and housing costs in every state →
How is Oregon’s economy doing?
It is growing slowly, with more people out of work than in most states. Oregon’s jobless rate stood at 5.1% in August 2026, tied for 2nd highest among the 50 states and D.C. with California and Connecticut; only D.C.’s, at 5.7%, was higher, and the U.S. rate was 4.1% (Bureau of Labor Statistics). The rate was down from 5.2% in July and from 5.3% a year earlier, but it was still above the national rate. On Oct. 14 the Oregon Employment Department put the September rate at 5.0%. Payrolls have barely grown: the department counted 2,600 more jobs in September than a year earlier, a gain of 0.1%.
Unemployment rate, August 2026
5.1%
U.S. 4.1%
Tied for 2nd highest among the 50 states and D.C.
Unemployment rate, 2025 average
5.2%
U.S. 4.3%
Above the U.S. rate every year since 2022
Jobs added in a year
2,600
September 2025 to September 2026, a gain of 0.1% (Oregon Employment Department)
Oregon’s jobless rate has run above the U.S. rate in every month published since August 2024
Monthly unemployment rate, seasonally adjusted, Oregon and the U.S., January 1990 to August 2026. October 2025 is missing: the Bureau of Labor Statistics published no figures for it during the federal shutdown.
Why is Oregon’s unemployment so high?
No one cause has been shown. We found three possibilities, each with a case against it.
A long pattern. The state’s economists write that it is “not unusual” for Oregon’s rate to drift above the nation’s (Office of Economic Analysis, Aug. 26, 2026). By the Bureau of Labor Statistics’ yearly averages, it was higher in 26 of the 36 years from 1990 to 2025, and the highest of any state in 2001, 2002 and 2003, reaching 8.0% in 2003. The case against: the gap isn’t fixed. Oregon’s rate was at or below the nation’s from 2019 to 2021.
Lost chip-making and factory jobs. The same forecasters cited Bureau of Labor Statistics data on Oregon jobs making semiconductors and other electronic components. Those jobs fell by 28% from January 2023 to June 2026. Manufacturing lost 4,300 jobs in the year to September, more than any other industry (Oregon Employment Department). Intel filed layoff notices in 2025 for its sites in Washington County. The case against: Washington County’s unemployment rate in August, 4.7%, was below the state’s. The highest rates were in the south, far from the chip plants, in Josephine (7.2%), Klamath (6.8%) and Douglas (6.1%) counties. County rates aren’t adjusted for the seasons, so they compare only roughly with the state rate.
Slow hiring rather than mass layoffs. The forecasters describe a “low hire-low fire” job market, and layoff notices have fallen from their 2025 peak. The case against: that describes the slowdown without saying why it hit Oregon harder than the country, and the forecasters themselves note that California, Washington state and Nevada have similar rates.
Unemployment claims and the minimum wage
Unemployment benefits are claimed through the Oregon Employment Department. Oregon’s labor bureau (BOLI) publishes the state’s current minimum wage rates.
Joblessness is highest in Josephine, Klamath and Douglas counties
| County | Rate |
|---|---|
| Josephine | 7.2% |
| Klamath | 6.8% |
| Douglas | 6.1% |
| Jackson | 5.9% |
| Lincoln | 5.7% |
| Coos | 5.7% |
| Multnomah | 5.1% |
| Washington County | 4.7% |
| Deschutes | 4.5% |
| Hood River | 3.7% |
Unemployment rate in selected Oregon counties, August 2026, not adjusted for the seasons. Josephine County’s rate was tied for 43rd highest among the 3,143 U.S. counties with a rate; Hood River’s was the lowest in Oregon. Source: Bureau of Labor Statistics. Unemployment in every state →
Which Oregon counties are poorest and most distressed?
Malheur County, on the Idaho border, is Oregon’s poorest: in 2024, 18.5% of its residents lived in poverty, the highest share in any of the state’s 36 counties (Census Bureau, Small Area Income and Poverty Estimates). On our County Distress Index, which scores every county in the country from 0 to 100 on the strain in household finances, Klamath County, home to Klamath Falls, is the most distressed; Lake, Josephine and Lincoln counties come next. The least distressed is Hood River County, in the Columbia River Gorge, followed by Washington County, west of Portland. No Oregon county ranks among the 100 most or least distressed in the U.S.
Oregon’s most distressed counties stretch across the south and down the coast; the counties scoring 70 or more are home to 9.9% of Oregonians
Each of Oregon’s 36 counties shaded by its County Distress Index score, 0 to 100, with data through August 2026.
Loading the county map…
The county map could not be loaded. Every county is in the lists on this page.
Most distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 1 | Klamath | 85 | 16.6% |
| 2 | Lake | 81 | 17.8% |
| 3 | Josephine | 78 | 13.8% |
| 4 | Lincoln | 76 | 16.3% |
| 5 | Coos | 75 | 16.8% |
| 6 | Douglas | 73 | 14.7% |
| 7 | Jefferson | 72 | 13.7% |
| 8 | Linn | 67 | 12.8% |
| 9 | Wasco | 67 | 12.8% |
| 10 | Curry | 66 | 16.4% |
Least distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 32 | Benton | 33 | 14.3% |
| 33 | Clackamas | 31 | 8.1% |
| 34 | Deschutes | 29 | 7.5% |
| 35 | Washington | 28 | 8.4% |
| 36 | Hood River | 21 | 10.8% |
Rank in Oregon, 1 = most distressed. Ranks follow unrounded scores, so two counties with the same printed score can rank apart, as Marion and Sherman do. Poverty: Census Bureau, 2024.
Every county, by score
Of Oregon’s 36 counties, 2 score 80 or more, Klamath and Lake, and 1.8% of Oregonians live in them (2023 population). With the 5 that score 70 to 79, the most distressed counties hold 9.9% of the state’s people. Multnomah County, the most populous and home to Portland, ranks 26th most distressed of the 36. Only Hood River, Washington and Deschutes counties score below 30.
18 score 50–69
Linn, Wasco, Curry, Sherman, Marion, Jackson, Malheur, Lane, Columbia, Harney, Grant, Crook, Umatilla, Baker, Wheeler, Tillamook, Yamhill, Union
3 score 0–29
Oregon’s poorest county isn’t its most distressed
Poverty is only one piece of the county score, which also weighs late payments, collections and bankruptcy, jobs and housing costs. Malheur County, the poorest, ranks 14th most distressed: its renters’ costs and late payments sit near the middle of U.S. counties. Lake County is both: its poverty rate is 2nd highest in the state, and it ranks 2nd most distressed. Josephine runs the other way: its poverty rate is 15th highest in the state, yet it ranks 3rd most distressed, with Oregon’s highest unemployment rate in August 2026 and the highest renters’ costs among the 10 most distressed counties. Benton County, home to Oregon State University in Corvallis, has a poverty rate tied for 11th highest in the state but ranks only 32nd most distressed of the 36. Another Census survey, or another year, can put a different county at the top; the figures here are the Census Bureau’s 2024 county estimates.
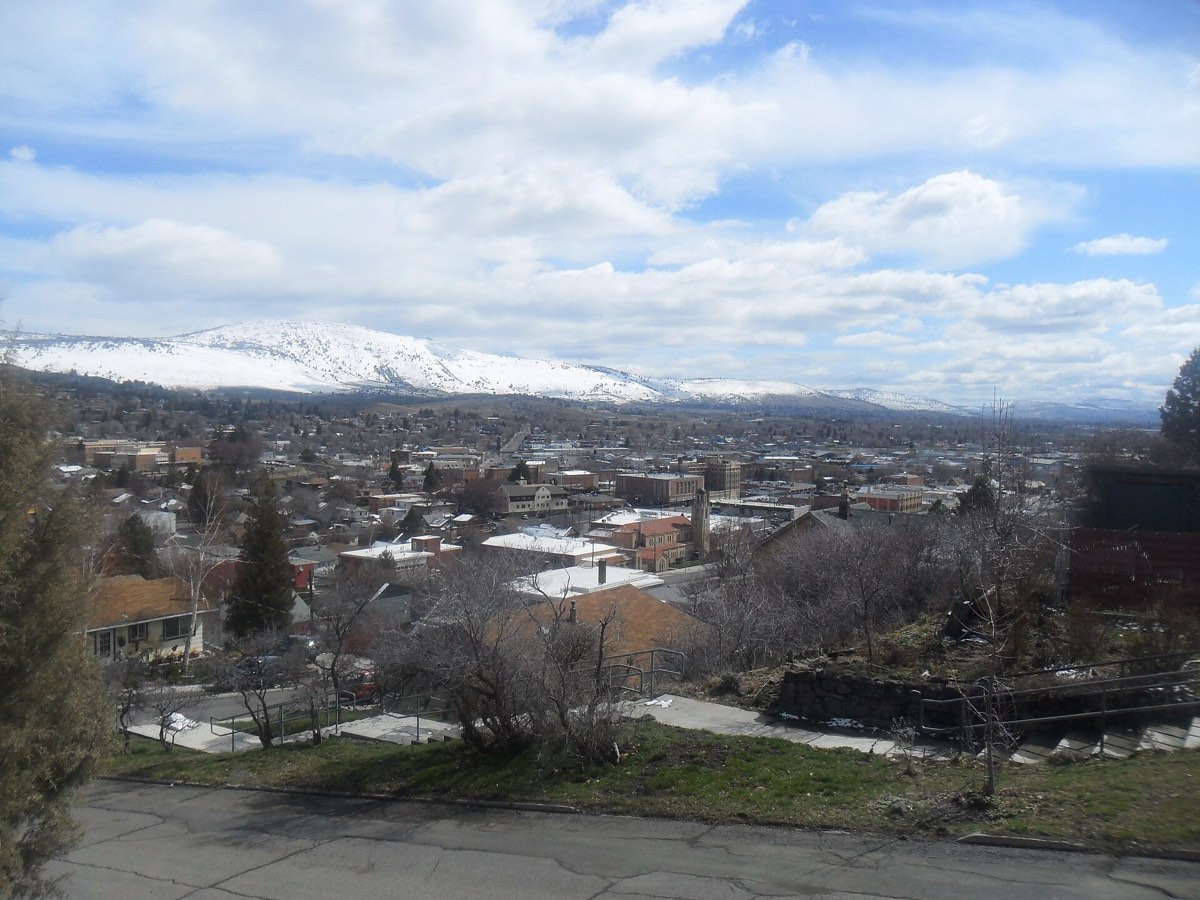
Klamath Falls, seen from a hillside in March 2011, is the seat of Klamath County, the most distressed county in Oregon. In 2024, 16.6% of the county’s residents lived in poverty (Census Bureau), and in August 2026 its unemployment rate of 6.8% was 2nd highest in the state (Bureau of Labor Statistics).
Sources: U.S. Census Bureau; U.S. Bureau of Labor Statistics; American Default Research. Photo: Bobjgalindo, via Wikimedia Commons, CC BY-SA 4.0.

The south and the coast against the Portland suburbs
Every Oregon county that scores 70 or more, except Jefferson in central Oregon, lies in the south or along the coast. The counties around Portland look very different. Washington County had the highest median household income in the state in 2024, $107,040, and scores 28; Clackamas, with a median income of $103,479, scores 31. Multnomah County, home to Portland itself, scores higher than its suburbs, at 49. Away from Portland, Deschutes County, around Bend, scores 29.
American Default Research, County Distress Index; U.S. Census Bureau, Small Area Income and Poverty Estimates.
Is Oregon a poor state?
No. Oregon sits near the middle of the states on poverty and above the middle on household income. In 2024, 11.7% of Oregonians lived in poverty, 25th highest among the 50 states and D.C. and a little under the U.S. rate of 12.1%. The typical household earned $84,897, 17th highest, against $81,604 nationally (Census Bureau, Small Area Income and Poverty Estimates). Income per person in 2024, which counts wages, business and investment income and government benefits, was $70,823, under the U.S. figure of $73,204 (Bureau of Economic Analysis). Every Census estimate since 2016 has put Oregon’s poverty rate under the nation’s.
Residents in poverty
11.7%
U.S. 12.1%
25th highest among the 50 states and D.C. (2024)
Median household income
$84,897
U.S. $81,604
17th highest among the 50 states and D.C. (2024)
Children in poverty
13.0%
U.S. 15.5%
Tied for 29th highest among the 50 states and D.C. (2024)
Oregon’s poverty rate matched or topped the nation’s from 2004 to 2015, peaking at 17.3% in 2011, and has been lower every year since
Percent of people below the poverty line, Oregon and the U.S., 1989 to 2024. The line skips 1990 to 1992 and 1994, years without Census state estimates.
Where Oregonians’ income comes from
Government benefits such as Social Security, Medicare and veterans’ benefits made up 21.1% of all personal income in Oregon in 2024, tied for 13th highest among the 50 states and D.C., against 18.3% nationwide. Wages and salaries paid by employers in the state made up 49.2%, close to the U.S. share of 49.7%; the Bureau of Economic Analysis counts wages where people work, not where they live.
An older state, with more disability
| Measure | Oregon | U.S. | Rank |
|---|---|---|---|
| Residents with a disability 10th highest | 15.5% U.S. 13.3% | 13.3% | 10th highest |
| Residents 65 and older 11th highest | 19.1% U.S. 17.2% | 17.2% | 11th highest |
| Adults without a high school diploma Tied for 28th highest | 8.2% U.S. 10.4% | 10.4% | Tied for 28th highest |
| Residents without health insurance 38th highest | 5.9% U.S. 8.4% | 8.4% | 38th highest |
Rank 1 is the highest share among the 50 states and D.C. Source: Census Bureau, American Community Survey, five-year figures for 2020 to 2024.
How many Oregonians get SNAP food benefits?
In June 2026, 697,500 Oregonians got SNAP food benefits, 16.3% of residents, 3rd highest among the 50 states and D.C., behind only New Mexico and D.C. Across the U.S. the share was 10.7% (U.S. Department of Agriculture). Oregon’s poverty rate, by contrast, ranks 25th highest. Oregonians apply through the state’s human services department.
Residents getting SNAP
16.3%
U.S. 10.7%
3rd highest among the 50 states and D.C. (June 2026)
People getting SNAP
697,500
June 2026, down from 772,310 in June 2025
Most of the past year’s drop came before the state began counting work-rule cut-offs
The number of Oregonians getting SNAP fell 9.7% between June 2025 and June 2026. Of that drop, 51,536 came between June 2025 and March 2026, and 23,274 more by June 2026 (U.S. Department of Agriculture). The state’s count of people cut off under the expanded federal work rules starts at the end of April 2026, when 6,948 people lost benefits, followed by 5,258 at the end of May (Oregon’s human services department). Those cut-offs came after most of the fall, and we found no source that splits the earlier drop by cause. A smaller count isn’t the same as less need.
Are Oregonians behind on their bills?
Fewer than in most states. Among Oregonians with a credit record, 12.1% were 90 or more days late on at least one debt in early 2025, 10th lowest among the 50 states and D.C., against 17.2% across the U.S. (Federal Reserve Bank of Philadelphia). We averaged the states, weighting each by population, for the national figure. The figures cover what households owe on cards, car loans, mortgages and other loans, not Oregon’s state budget.
Oregon’s place among the 50 states and D.C., counted from the smallest share: cards tied for 11th lowest, car loans 17th lowest, mortgages tied for 7th lowest and collections 14th lowest. The U.S. bars are our population-weighted average of the states.
The share of Oregonians with a debt in collections fell from 14.9% at the end of 2019 to 9.5% in early 2025. But that isn’t a sign that fewer people are struggling. The share was already lower by early 2022 (10.8%). Part of the later fall comes from a change in what credit reports show. In 2022, the three national credit bureaus said they would stop reporting certain medical debts. Nationwide, the share of people with a medical collection on their record went from about 14% in March 2022 to about 5% in June 2023 (Consumer Financial Protection Bureau).
Oregonians owe more than most, but less of it is late
The Federal Reserve Bank of New York measures dollars rather than people. Oregonians with a credit report owed $69,640 each at the end of 2025, 12th highest among the 50 states and D.C. and more than the U.S. average of $63,200. Yet a smaller share of those dollars was seriously late than across the country on cards, car loans and mortgages alike.
| Loan type | Oregon | U.S. | Oregon 2019 | U.S. 2019 |
|---|---|---|---|---|
| Auto loan | 3.6% End of 2025 U.S. 5.2% Oregon 2019 2.6% · U.S. 2019 4.9% | 5.2% | 2.6% | 4.9% |
| Credit card | 9.5% End of 2025 U.S. 12.4% Oregon 2019 6.3% · U.S. 2019 8.1% | 12.4% | 6.3% | 8.1% |
| Mortgage | 0.6% End of 2025 U.S. 0.9% Oregon 2019 0.5% · U.S. 2019 1.0% | 0.9% | 0.5% | 1.0% |
Share of balances 90 or more days past due, end of 2025 and end of 2019 (Federal Reserve Bank of New York, Consumer Credit Panel / Equifax). These count dollars, not people, so they can’t be compared with the Philadelphia Fed bars above, and they include old debts that lenders have written off but still report.
Other signs of strain are lower too
Mortgages a month or two behind, low credit scores, cards near their limit and mortgages with little equity (the part of a home’s value the owner doesn’t owe) are all less common in Oregon than across the country.
| Measure | Oregon | U.S. | Rank |
|---|---|---|---|
| Mortgages 30 to 89 days late, Sept. 2025 2nd lowest | 0.8% U.S. 1.6% | 1.6% | 2nd lowest |
| People with a credit score under 620, early 2025 10th lowest | 9.5% U.S. 13.8% | 13.8% | 10th lowest |
| Card users near their credit limit, early 2025 17th lowest | 23.1% U.S. 26.9% | 26.9% | 17th lowest |
| Mortgages with under 10% equity, mid-2026 Tied for 21st lowest | 4.0% U.S. 4.7% | 4.7% | Tied for 21st lowest |
Rank counted from the smallest share among the 50 states and D.C. Mortgages 30 to 89 days late: Consumer Financial Protection Bureau. Credit scores and card use: Federal Reserve Bank of Philadelphia, with our population-weighted U.S. figure. Equity: Federal Housing Finance Agency. Late payments in every state →
Are bankruptcies rising in Oregon?
Yes, faster than almost anywhere. Oregonians filed 8,202 bankruptcy cases in 2025, up 24.4% from 2024; only D.C. had a faster rise (U.S. Courts). It was the most filings in a year since 2019, and the count has gone up every year since its 2022 low of 4,202. Measured against the population, Oregon sits closer to the middle: 192.0 filings for every 100,000 residents, using the 2024 population, 16th highest among the 50 states and D.C., against 167.1 nationally. The 12 months to June 2026 brought 8,244 filings.
Rise in filings from 2024
24.4%
U.S. 11.1%
2nd highest among the 50 states and D.C. (2025)
Bankruptcy filings per 100,000 residents
192.0
U.S. 167.1
16th highest among the 50 states and D.C. (2025, using the 2024 population)
Share of filings under Chapter 13
21.8%
U.S. 35.9%
17th lowest among the 50 states and D.C. (2025)
Most Oregon filers use Chapter 7: 77.7% of 2025 cases. Under it, a trustee sells some property to pay debts, and most of the rest is wiped out. Chapter 13, where a filer repays part of the debts through a court-approved plan, made up 21.8%, well under the U.S. share. A few dozen cases, almost all Chapter 11, make up the rest. Filings have climbed along with unemployment since 2023, but we found no study tying the two together in Oregon, and filings rose across the country too, by 11.1% in 2025.
| Year | Filings |
|---|---|
| 2016 | 9,131 |
| 2017 | 9,191 |
| 2018 | 8,815 |
| 2019 | 8,996 |
| 2020 | 6,636 |
| 2021 | 4,771 |
| 2022 | 4,202 |
| 2023 | 5,687 |
| 2024 | 6,594 |
| 2025 | 8,202 |
Bankruptcy cases of every chapter filed in the U.S. Bankruptcy Court for the District of Oregon, by calendar year. Source: Administrative Office of the U.S. Courts, Table F-2. Bankruptcy filings in every state →
How foreclosure works in Oregon
In Oregon, a home can be foreclosed without going to court: a trustee sells it after a fixed set of notices (ORS 86.705 to 86.815), though a lender can choose to sue in court instead (ORS 88.010). Federal servicing rules generally keep the process from starting until a home loan is more than 120 days behind. Before it files a notice of default on a home, a lender must ask for a resolution conference, a meeting with a neutral facilitator to look at ways to avoid foreclosure, through the state’s Foreclosure Avoidance Program. A lender that started 30 or fewer foreclosures the year before can claim an exemption (ORS 86.726).
The notice of sale must go to the owner at least 120 days before the sale (ORS 86.764) and run in a local newspaper once a week for four weeks (ORS 86.774). The owner can stop the sale by catching up on what is overdue until five days before it (ORS 86.778). After a trustee’s sale, the former owner can’t buy the home back, and the lender can’t sue for any balance the sale leaves unpaid (ORS 86.797).
- Goes through a court
- Not required
- Resolution conference first
- Yes, unless exempt
- Notice before the sale
- 120 days
- Catching up allowed until
- 5 days before
- Buying back after a trustee’s sale
- No
- Lender can seek the unpaid balance
- No
What the law says. Sources: ORS 86.705, 86.726, 86.764, 86.774, 86.778, 86.797 and 88.010; federal rule 12 CFR 1024.41. How foreclosure works in Oregon →
Oregon’s award from the federal Homeowner Assistance Fund was $90.9 million, and the program had helped 3,951 homeowners through early 2026 (U.S. Treasury). The state stopped taking new applications on July 17, 2026 (Oregon Housing and Community Services).
What changed in Oregon in the past year
-
Oct. 14, 2026
The state reports September unemployment, little changed from August
The Oregon Employment Department published its own September estimate six days before the federal figures for every state. It shows the rate barely moved from August, with health care adding the most jobs over the year and manufacturing and government cutting the most (the figures are in the jobs section).
-
July 30, 2026
Daimler Truck tells the state it will close its Portland truck plant
Daimler Truck North America gave notice that it would permanently close its Portland Truck Manufacturing Plant and related sites in North Portland, affecting about 387 workers, with operations ending on Oct. 30, 2026.
Oregon Higher Education Coordinating Commission, WARN notice #9549
-
July 17, 2026
Oregon’s Homeowner Assistance Fund stops taking new applications
Oregon Housing and Community Services closed the federally funded mortgage help program to new applicants and said it would keep working through pending applications until the money runs out (how many homeowners it helped).
Oregon Housing and Community Services, Homeowner Assistance Fund
-
July 8, 2026
Portland General Electric’s home rates fall as data centers pay more
To carry out the 2025 POWER Act (House Bill 3546), the Oregon Public Utility Commission shifted costs onto the company’s data center customers. Their rates rose 29% on average, and home rates fell 1.3% on average. That followed a rise of about 5% in the typical home bill on April 1, which waited out the winter: the FAIR Act (House Bill 3179) bars home rate increases from Nov. 1 to March 31 (Oregon Public Utility Commission, release on the April 1 rates). This item covers Portland General Electric only, not Pacific Power.
-
End of April 2026
The state counts SNAP cut-offs under the new federal work rules
Oregon’s human services department told legislators that a 2025 federal law expanded SNAP’s work rules to more than 300,000 Oregonians, including veterans and people experiencing homelessness who used to be exempt. Its count of people who lost benefits under the rules begins at the end of April (the counts are in the SNAP section).
Oregon’s human services department (ODHS), presentation to the Legislature, June 15, 2026
-
Nov. 13, 2025
Intel files another layoff notice for its Washington County sites
Intel told the state that about 669 more employees at or reporting to its Hillsboro and Aloha sites would lose their jobs, following a larger notice for the same sites in July 2025.
Oregon Higher Education Coordinating Commission, WARN notice #9389
-
Nov. 7, 2025
A transportation tax package is signed, then mostly rejected by voters
Gov. Tina Kotek signed House Bill 3991, which raised transportation taxes and fees. Voters later rejected most of the fee and tax increases in Measure 120, according to the Oregon Department of Transportation. A higher supplemental registration fee for vehicles rated at 40 miles per gallon or more is in effect, and a per-mile road charge for existing electric vehicles is set to begin on July 1, 2027.
Loan modifications and foreclosure top Oregon’s mortgage complaints
Oregonians have sent the Consumer Financial Protection Bureau 5,217 complaints about mortgages since the start of 2012. The issue raised most often was the one the bureau calls “loan modification, collection, foreclosure” (1,314). Close behind came “trouble during payment process” (1,279), then “loan servicing, payments, escrow account” (1,045).
- Oct. 4, 2026 M&T Bank Struggling to pay mortgage: Trying to communicate with the company to fix an issue related to modification, forbearance, short sale, deed-in-lieu, bankruptcy, or foreclosure Closed with explanation
- Oct. 2, 2026 LoanCare Struggling to pay mortgage: Trying to communicate with the company to fix an issue related to modification, forbearance, short sale, deed-in-lieu, bankruptcy, or foreclosure Closed with explanation
- Oct. 1, 2026 CrossCountry Mortgage Struggling to pay mortgage: Applying for or obtaining a modification, forbearance plan, short sale, or deed-in-lieu In progress
- Sept. 30, 2026 Shellpoint / NewRez Struggling to pay mortgage: Trying to communicate with the company to fix an issue related to modification, forbearance, short sale, deed-in-lieu, bankruptcy, or foreclosure In progress
- Sept. 30, 2026 Ocwen / Onity Group Trouble during payment process: Trying to communicate with the company to fix an issue while managing or servicing your loan Closed with explanation
- Sept. 29, 2026 CMG Financial Trouble during payment process: Payment process Closed with explanation
- Sept. 29, 2026 Goldman Sachs Bank USA Trouble during payment process: Escrow, taxes, or insurance Closed with explanation
- Sept. 28, 2026 Rocket Mortgage Struggling to pay mortgage: Foreclosure Closed with explanation
- Sept. 23, 2026 Fay Servicing Struggling to pay mortgage: Applying for or obtaining a modification, forbearance plan, short sale, or deed-in-lieu Closed with explanation
- Sept. 23, 2026 Shellpoint / NewRez Struggling to pay mortgage: Trying to communicate with the company to fix an issue related to modification, forbearance, short sale, deed-in-lieu, bankruptcy, or foreclosure In progress
The 10 newest Oregon complaints about paying a mortgage or getting help with one, from the Consumer Financial Protection Bureau’s public record as of Oct. 14, 2026. Complaints about getting a new loan, and any naming a credit reporting company, are left out. The bureau publishes what people report without checking each account. Every Oregon mortgage complaint at the Consumer Financial Protection Bureau →
What to watch before the next edition
What is scheduled between now and January 2027 that could affect household budgets in Oregon, nearest first.
-
Oct. 20, 2026
September unemployment rates for every state
The Bureau of Labor Statistics publishes September rates for the 50 states and D.C., the first chance to rank Oregon’s September figure. The Oregon Employment Department plans to release September county rates the same day.
U.S. Bureau of Labor Statistics, State Employment and Unemployment for August 2026
-
Oct. 30, 2026
Daimler Truck’s Portland plant is set to close
The company’s notice to the state says operations at the Portland plant and its related sites will end on this date.
Oregon Higher Education Coordinating Commission, WARN notice #9549
-
Nov. 18, 2026
October unemployment and the state’s next revenue forecast
The Oregon Employment Department plans to release the statewide rate for October. The Office of Economic Analysis lists its next economic and revenue forecast, which includes the kicker outlook, for the same day; its calendar calls the dates tentative (2026 forecast calendar).
-
Jan. 1, 2027
A higher cap on yearly rent increases
For 2027, the most a landlord can raise the rent on most tenancies covered by the state’s rent stabilization law is 10%, up from 9.5% in 2026. Larger manufactured-home parks have a lower cap.
-
Jan. 1, 2027
Medicaid work requirements are due to start
Under the 2025 federal law that changed SNAP, work requirements for some members of the Oregon Health Plan, the state’s Medicaid program, are due to begin on this date, according to a timeline the state’s human services and health agencies gave legislators in September 2025. The law lets a state ask for more time, up to the end of 2028.
Where Oregon ranks highest and lowest
| Measure | Oregon | U.S. | Rank | Latest data |
|---|---|---|---|---|
| Unemployment rate, three-month average Tied for 2nd highest · June–August 2026 | 5.2% U.S. 4.1% | 4.1% | Tied for 2nd highest | June–August 2026 |
| Rise in bankruptcy filings from the year before 2nd highest · 2025 | 24.4% U.S. 11.1% | 11.1% | 2nd highest | 2025 |
| Residents getting SNAP food benefits 3rd highest · June 2026 | 16.3% U.S. 10.7% | 10.7% | 3rd highest | June 2026 |
| Renters spending 30% or more of income on housing 6th highest · 2024* | 49.5% U.S. 47.6% | 47.6% | 6th highest | 2024* |
| Homeowners spending 30% or more of income on housing 9th highest · 2024* | 25.1% U.S. 22.5% | 22.5% | 9th highest | 2024* |
| Renters spending half or more of income on housing Tied for 9th highest · 2024 | 26.6% U.S. 26.1% | 26.1% | Tied for 9th highest | 2024 |
| Household debt per person with a credit report 12th highest · End of 2025 | $69,640 U.S. $63,200 | $63,200 | 12th highest | End of 2025 |
| Median rent, a month 14th highest · 2024* | $1,525 U.S. $1,413 | $1,413 | 14th highest | 2024* |
| Bankruptcy filings per 100,000 residents (2024 population) 16th highest · 2025 | 192.0 U.S. 167.1 | 167.1 | 16th highest | 2025 |
| Median household income 17th highest · 2024 | $84,897 U.S. $81,604 | $81,604 | 17th highest | 2024 |
| Residents in poverty 25th highest · 2024 | 11.7% U.S. 12.1% | 12.1% | 25th highest | 2024 |
| People with a debt in collections 14th lowest · Early 2025 | 9.5% U.S. 13.2% | 13.2% | 14th lowest | Early 2025 |
| People with a debt 90+ days late 10th lowest · Early 2025 | 12.1% U.S. 17.2% | 17.2% | 10th lowest | Early 2025 |
| Share of credit card dollars 90+ days late Tied for 7th lowest · End of 2025 | 9.5% U.S. 12.4% | 12.4% | Tied for 7th lowest | End of 2025 |
| Mortgages 30 to 89 days late 2nd lowest · Sept. 2025 | 0.8% U.S. 1.6% | 1.6% | 2nd lowest | Sept. 2025 |
Ranks cover the 50 states and D.C.: “highest” counts down from the largest figure, “lowest” up from the smallest, and places with the same printed figure share a rank. *Census Bureau five-year figures, 2020 to 2024. Late payments and collections come from the Federal Reserve Bank of Philadelphia and count people with a credit record; for its U.S. figure we averaged the states, weighting each by population. Card balances count dollars (Federal Reserve Bank of New York). Each producer is named in Sources and method. Download this table: CSV.
Questions about Oregon
Is it expensive to live in Oregon?
For renters, more than in most states. The median rent was $1,525 a month over 2020 to 2024, 14th highest among the 50 states and D.C., and 49.5% of renter households paid 30% or more of their income for housing (U.S. Census Bureau). By the MIT Living Wage Calculator, one adult needs $55,047 a year for a basic budget in Oregon (2025 dollars). We don’t measure prices for food, gas or insurance, so we don’t rank the overall cost of living.
Why does Oregon have such high unemployment?
No single cause has been proven. At 5.1% in August 2026, Oregon’s rate was tied for 2nd highest among the 50 states and D.C. (U.S. Bureau of Labor Statistics). The state’s economists report a 28% fall in jobs making semiconductors and other electronic components from January 2023 to June 2026 and slow hiring. But the highest county rates are in the south, far from the chip plants. Oregon’s rate has topped the nation’s in most years since 1990. More on Oregon’s jobs →
What’s the poorest county in Oregon?
Malheur County, on the Idaho border, with a 2024 poverty rate of 18.5%, the highest of the state’s 36 counties (U.S. Census Bureau, Small Area Income and Poverty Estimates). Lake and Wheeler counties come next. On our County Distress Index, Klamath County is the most distressed.
What’s the poverty line in Oregon?
Oregon uses the federal poverty guideline. The 2026 guideline is $15,960 for one person and $33,000 for a family of four; Alaska and Hawaii are the only states with separate figures (U.S. Department of Health and Human Services).
How much is the Oregon kicker?
On 2025 Oregon returns, filed in 2026, the kicker credit was 9.863% of a filer’s 2024 Oregon tax before most credits, and it can be claimed only on returns for odd-numbered years (Oregon Department of Revenue). Statewide it came to $1.4 billion, by the state economists’ count, and their August 2026 forecast put the revenue that decides the personal kicker below the level that would trigger one for 2025 to 2027.
Cite or reuse Oregon’s data
Reporters, grant writers and policy staff are welcome to use these figures; please credit American Default Research.
State Distress Index
Oregon
19thmost distressed state
of the 50 states and D.C.
More distressed than 64% of the other states and D.C.
American Default Research publishes the State Distress Index. Oregon ranks as the 19th most financially distressed of the 50 states and D.C. overall. In August 2026, its unemployment rate was 5.1%, tied for 2nd highest among the 50 states and D.C. (U.S. Bureau of Labor Statistics). Over 2020 to 2024, 49.5% of its renter households paid 30% or more of their income for housing, 6th highest (U.S. Census Bureau, American Community Survey). Yet in early 2025 only 12.1% of Oregonians with a credit record had a debt 90 or more days late, 10th lowest (Federal Reserve Bank of Philadelphia).
Questions, interviews or a custom cut of the data: press@americandefault.org
Sources and method
We gather the data, run the numbers and research each state ourselves.
This edition: October 2026 · Next edition expected March 2027
- People 90 or more days late, debts in collections, credit scores and card useFederal Reserve Bank of Philadelphia, Consumer Credit Explorerend of 2019, early 2022 and early 2025
- Debt per person and the share of balances 90 or more days lateFederal Reserve Bank of New York, Consumer Credit Panel / Equifaxend of 2019 and end of 2025
- Mortgages with little equityFederal Housing Finance Agency, National Mortgage Databasesecond quarter of 2026
- Mortgages 30 to 89 days late; mortgage complaints; medical debts on credit reportsConsumer Financial Protection Bureau: Mortgage Performance Trends; complaint database; Recent changes in medical collections on consumer credit recordsSept. 2025; Oct. 14, 2026; March 2022 to June 2023
- Bankruptcy filings by year and chapterU.S. Courts, Table F-22016 to June 2026
- Unemployment, state, county and nationalU.S. Bureau of Labor Statistics, Local Area Unemployment StatisticsJan. 1990 to Aug. 2026
- September unemployment and jobs by industryOregon Employment Department, news releaseOct. 14, 2026
- Chip-making jobs, the job market and the kickerOregon Office of Economic Analysis, Oregon Economic and Revenue ForecastAug. 26, 2026
- Poverty and incomeCensus Bureau, Small Area Income and Poverty Estimates1989 to 2024
- Renters spending half or more of income on housingCensus Bureau, American Community Survey 1-year2005 to 2024
- Rent, housing costs, disability, age, schooling and health insuranceCensus Bureau, American Community Survey 5-year2020 to 2024
- Population for filing ratesCensus Bureau, population estimates2024
- Personal income per person and by sourceU.S. Bureau of Economic Analysis2024
- SNAPU.S. Department of Agriculture Food and Nutrition AdministrationJune 2025 to June 2026
- SNAP work-rule cut-offsOregon’s human services department, presentation to the LegislatureJune 15, 2026
- Cost of a basic budgetMIT Living Wage Calculator2025 dollars
- Rent increase capOregon Office of Economic Analysis, rent stabilization2026 and 2027
- Kicker creditOregon Department of Revenueread October 2026
- Mortgage help fundU.S. Treasury, Homeowner Assistance Fund; Oregon Housing and Community Servicesthrough early 2026; July 17, 2026
- Foreclosure lawOregon Revised Statutes, chapter 86 and chapter 88; 12 CFR 1024.41as of 2026
- Poverty guidelineU.S. Department of Health and Human Services2026
- Housing counselorsU.S. Department of Housing and Urban DevelopmentOctober 2026
- What changed and what to watchOregon Higher Education Coordinating Commission, WARN notices, Oregon Public Utility Commission, Oregon Department of Transportation, Oregon’s human services department and Oregon Health Authority, Office of Economic Analysis forecast calendar, U.S. Bureau of Labor Statistics; every item above links to its own sourceNov. 2025 to Jan. 2027
- County photoBobjgalindo, via Wikimedia Commons2011
The four equal parts of the score are jobs, renters’ housing costs, collections and bankruptcy, and late payments. Each part runs from 0 to 100, and the score is the share of the other states and D.C. whose four-part average is lower than Oregon’s. The full method →
We write with AI tools, and Ross Kilburn checks and reviews every page before it's published.
Get the next Oregon edition by email
One email each time a new Oregon edition is out; the next is expected in March 2027. Unsubscribe anytime.
Thanks, that helps.