Maryland lost 18.1% of its federal government jobs, the largest share of any state
Each state is shaded by how distressed its households are, from green (least) to red (most), with data through September 2026. Maryland scores 70 out of 100.
Maryland lost 18.1% of its federal government jobs from January 2025 to August 2026, the largest share of any state. Its typical household income, $102,835 in 2024, was 4th highest nationally. Late payments and renters’ housing costs sit above the middle of the states. Baltimore City, Somerset County and Dorchester County rank highest for local distress. Howard and Carroll counties rank lowest.
- Score
- 70/100
- Data through
- September 2026
- Edition
- October 2026
Next edition expected March 2027
How Maryland ranks among the states
Maryland is the 16th most distressed of the 50 states and D.C., even though it is one of the richest states (is Maryland rich?). In 2024 its typical household income was the 4th highest of the 50 states and D.C., and its poverty rate was tied for 3rd lowest. Yet in early 2025, 17.2% of Marylanders with a credit record had a debt 90 or more days late, the same share as nationwide (Federal Reserve Bank of Philadelphia). They do owe more than people in most states. At the end of 2025, household debt came to $81,390 per Marylander with a credit report, the 7th highest. Credit cards accounted for $5,090 of it, the 5th highest (Federal Reserve Bank of New York). Those balances aren’t part of the score. What the score counts is how often people fall behind, end up in collections or file for bankruptcy, how many are out of work and how much renters pay. Maryland lands a little above the middle on each.
What drives the score
A part is the average of one or more measures, and each measure gets a score from 0 to 100 for where Maryland stands among the states. Maryland’s four parts average 66, which is higher than the four-part average of 35 of the other 49 states and D.C. in the index. Those make up 70% of the other places, and that percentage is the score, not the average of the parts.
- Renters’ housing costs79Just over a quarter of Maryland renter households, 25.7%, spent half or more of their income on rent and utilities in 2024, tied for 16th highest among the states; the U.S. share was 26.1%.
- Late payments67In early 2025, Maryland borrowers were 90 or more days behind on cards, car loans and mortgages a little more often than borrowers nationwide.
- Collections and bankruptcy61Maryland had 198.1 bankruptcy filings per 100,000 residents in 2025 (2024 population), 15th highest among the states, though a smaller share of people than nationwide had a debt in collections.
- Jobs56The jobless rate for June through August 2026 averaged 4.2%, close to the nation’s 4.1%, which makes jobs the lowest of Maryland’s four parts.
Beside its neighbors
Delaware scores higher than Maryland. West Virginia, the District of Columbia, Pennsylvania and Virginia score lower.
State Distress Index score, 0 to 100. Income doesn’t set the order. Of the six, only D.C.’s typical household earned more than Maryland’s in 2024, $109,289. Delaware’s earned less, $87,510, yet Delaware scores higher, and West Virginia’s earned the least, $60,662, yet West Virginia scores lower (Census Bureau, Small Area Income and Poverty Estimates).
Maryland’s score peaked in 2021, sank in 2023 and climbed back
Its worst and best quarters
Maryland was most distressed in the first quarter of 2021, 11th among the states with a score of 80. Renters’ housing costs, at 79, and jobs, at 64, were its highest parts, after a year in which unemployment averaged 6.5%, against 8.1% nationwide. Its least distressed quarter in our history, which starts in mid-2006, was the third quarter of 2007, at 20, 41st. Through the Great Recession it stayed near the middle, ranking between 25th and 32nd from mid-2008 through 2013.
The 2023 low and the climb back
In the second half of 2023 the score fell to 42, 30th among the states. Unemployment averaged 2.2% that year, Maryland’s lowest yearly rate in Bureau of Labor Statistics figures going back to 1990, and the jobs part sank to 5. From the end of 2023 the score rose every quarter through the end of the chart. One Census Bureau estimate lifted the renters’ part from 60 to 79 in the third quarter of 2024 alone, and the jobs part rose as unemployment did (see jobs).
Since the chart ends
In the chart’s last quarter, early 2025, Maryland scored 70 and ranked 16th. Today it scores 70, 16th, the same as then. The renters’ part held at 79 once the Census Bureau’s 2025 estimate came in, while the jobs part rose from 38 to 56 as unemployment climbed.
Maryland’s distress score, 2006 to early 2025: it ranked 41st most distressed in 2007, 11th in early 2021 and 16th in early 2025
Score on the State Distress Index, 0 to 100, each quarter from the third quarter of 2006 to the first quarter of 2025.
Maryland’s poorest, richest and most distressed counties
Somerset County, on the Eastern Shore, is Maryland’s poorest: 20.3% of its residents lived in poverty in 2024, the highest rate among Maryland’s 23 counties and Baltimore City (Census Bureau, Small Area Income and Poverty Estimates). On our County Distress Index, which measures strain on household finances in every U.S. county, Baltimore City is the most distressed place in the state, with a score of 97; Somerset is second. Baltimore City is an independent city counted as a county, separate from Baltimore County, and it is the only Maryland place among the 100 most distressed of the 3,144 counties we score, at 94th (the national list). Howard County, between Baltimore and Washington, is the richest, with a typical household income of $149,980 in 2024, and also the least distressed.
Baltimore City and two Eastern Shore counties, Somerset and Dorchester, are the only places scoring 80 or more; they hold 10.1% of Marylanders
County Distress Index score, 0 to 100, for each of Maryland’s 23 counties and Baltimore City; data through August 2026.
Loading the county map…
The county map could not be loaded. Every county is in the lists on this page.
Most distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 1 | Baltimore city | 97 | 18.0% |
| 2 | Somerset | 90 | 20.3% |
| 3 | Dorchester | 83 | 14.1% |
| 4 | Prince George's | 78 | 10.4% |
| 5 | Wicomico | 76 | 16.0% |
| 6 | Allegany | 64 | 16.6% |
| 7 | Baltimore | 61 | 9.3% |
| 8 | Caroline | 60 | 11.1% |
| 9 | Charles | 58 | 6.8% |
| 10 | Cecil | 55 | 9.1% |
Least distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 20 | Montgomery | 18 | 7.5% |
| 21 | Anne Arundel | 17 | 6.6% |
| 22 | Queen Anne's | 13 | 6.1% |
| 23 | Carroll | 9 | 5.8% |
| 24 | Howard | 8 | 5.5% |
Rank in Maryland, 1 = most distressed. Ranks come from unrounded scores. Poverty: the Census Bureau’s 2024 estimate of the share of residents in poverty.
Every county, by score
The least distressed group is also the largest: 10 places, from Howard and Montgomery near Washington to Queen Anne’s and Talbot on the Eastern Shore, score under 30 and hold 45.1% of Marylanders. The places scoring 70 or more are Baltimore City, Prince George’s, Somerset, Dorchester and Wicomico; together they hold 27.1%.
3 score 80–100
2 score 70–79
10 score 0–29
Garrett, Talbot, Calvert, St. Mary's, Frederick, Montgomery, Anne Arundel, Queen Anne's, Carroll, Howard
Prince George’s, a middle-income county, is among Maryland’s most distressed
Poverty is only one piece of our county score. The County Distress Index gives equal weight to five parts. They are late payments, collections and bankruptcy, jobs (the unemployment rate and the share of adults 25 to 54 without work), renters’ housing costs, and a part built from poverty, child poverty, household income, disability and health insurance. Prince George’s County, east of Washington, has the 11th highest poverty rate in the state and sits in the middle on income. But only Baltimore City scores higher on late payments or on renters’ costs, so it ranks 4th most distressed. Charles County, to its south, has the 4th highest household income in Maryland, $125,985, and still ranks 9th, with late payments and collections near the top of the state. Western Maryland runs the other way: Allegany County has the 3rd highest poverty rate yet ranks 6th on distress. Garrett, with the 7th highest, ranks 15th, with the lowest renters’ costs in the state. Kent County, on the upper Eastern Shore, has the 5th highest poverty rate but ranks 13th, with the lowest collections-and-bankruptcy score in Maryland. Other lists may name a different poorest county if they use another Census survey or year; ours is the Census Bureau’s 2024 county estimate.
The five poorest
| County | Poverty | Distress rank |
|---|---|---|
| Somerset | 20.3% | 2nd |
| Baltimore city | 18.0% | 1st |
| Allegany | 16.6% | 6th |
| Wicomico | 16.0% | 5th |
| Kent | 14.6% | 13th |
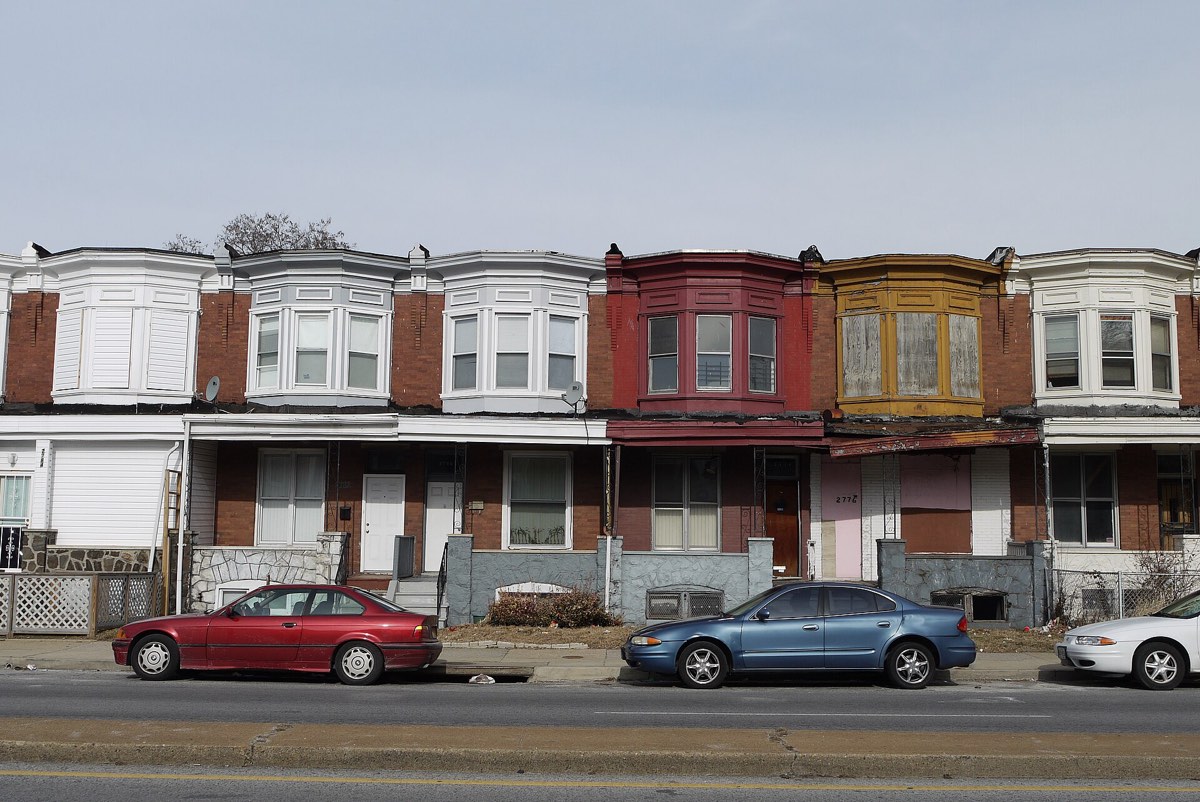
Rowhouses on North Avenue in Baltimore in January 2011. Baltimore City counted 949,708 residents in the 1950 census, its largest count; the 2020 census counted 585,708, 62% of that peak (U.S. Census Bureau).
Source: U.S. Census Bureau. Photo: Eli Pousson, Baltimore Heritage, Wikimedia Commons, CC0.

On the Eastern Shore, three counties rank near the top on late payments
Somerset, Dorchester and Wicomico counties, around Princess Anne, Cambridge and Salisbury, are three of Maryland’s five most distressed places, and all three rank near the top of the state on late payments. In August 2026, 4.5% of Dorchester’s labor force and 4.4% of Somerset’s were out of work, not adjusting for seasonal swings (Bureau of Labor Statistics). Local waivers from SNAP’s work rule had spared some adults in Somerset, Dorchester, Baltimore City, Kent and Worcester. Those waivers are gone. By September 2025, Maryland’s human services department said no place in the state had one (see SNAP).
American Default Research, County Distress Index; U.S. Bureau of Labor Statistics; Maryland’s human services department.
Maryland’s cost of living: rent among the highest in the country
Rent is where Maryland’s costs show most in our data. The typical rent in Maryland, $1,705 a month across 2020 to 2024, ranked 8th highest among the 50 states and D.C., against a U.S. median of $1,413 (U.S. Census Bureau). Because incomes are high too, a year of median rent equals 19.9% of Maryland’s median household income, a bit less than the U.S. figure of 20.8% (our calculation). But many renters still stretch: 48.7% of Maryland renter households spent at least 30% of their income on housing in 2020 to 2024. We don’t measure prices for food, fuel or power, so this page can’t rank Maryland’s whole cost of living; electric bills come up below.
Median rent, a month
$1,705
U.S. $1,413
8th highest among the states, 2020 to 2024
Renters spending at least 30% of income on housing
48.7%
U.S. 47.6%
11th highest among the states, 2020 to 2024
Basic yearly budget, one adult
$53,949
11th highest among the states, MIT Living Wage Calculator, 2025 dollars
Maryland renters paying half their income on housing peaked at 27.4% in 2023, the highest of any year since 2005, and eased to 25.7% in 2024
Renter households spending half or more of their income on rent and utilities, Maryland and the U.S., 2005 to 2024. There is no 2020 point: the Census Bureau put out no one-year estimates that year.
What a bare-bones budget costs in Maryland
For one adult with no children, the MIT Living Wage Calculator puts basic costs in Maryland at $53,949 a year before taxes; for two working parents with two children, $128,925. The budgets count necessities only.
Electric bills aren’t in our data either. Customers of the electric company Pepco in Montgomery and Prince George’s counties have paid more since an Aug. 28, 2026, rate decision. A December 2025 decision by the Maryland Public Service Commission added a small charge to Baltimore Gas and Electric (BGE) bills from February 2026 through 2027. It is 72 cents a month for the average home electric customer and $1.95 for gas. BGE has applied to change its electric rates again (see what changed and what to watch).
Rent takes more of a typical income in D.C. and Virginia than in Maryland
Of Maryland’s neighbors, only D.C. and Virginia spend a bigger share of a typical household income on rent; Delaware, Pennsylvania and West Virginia spend less. We don’t measure other prices.
| Place | Rent, a month | Typical household income | Rent as share of income |
|---|---|---|---|
| D.C. Rent as share of income 21.5% | $1,954 Typical household income $109,289 | $109,289 | 21.5% |
| Virginia Rent as share of income 20.6% | $1,579 Typical household income $92,116 | $92,116 | 20.6% |
| Maryland Rent as share of income 19.9% | $1,705 Typical household income $102,835 | $102,835 | 19.9% |
| Delaware Rent as share of income 19.2% | $1,401 Typical household income $87,510 | $87,510 | 19.2% |
| Pennsylvania Rent as share of income 18.7% | $1,209 Typical household income $77,532 | $77,532 | 18.7% |
| West Virginia Rent as share of income 17.2% | $872 Typical household income $60,662 | $60,662 | 17.2% |
Rent is the Census Bureau’s median gross rent for 2020 to 2024; income is its 2024 median household income estimate; the share divides a year of that rent by that income, our calculation. Rent and housing costs across the U.S. →
Maryland’s unemployment rate has caught up with the nation’s
In August 2026, 4.1% of Maryland’s labor force was out of work, the same as the U.S. rate; Maryland was tied for 22nd highest among the 50 states and D.C. (U.S. Bureau of Labor Statistics). Its yearly rate was below the nation’s in every year from 1990 through 2025. The monthly rate began climbing in mid-2023 and kept rising through 2024, from 2.8% in January to 3.4% in December, then ran above the U.S. rate from April to July 2026, peaking at 4.4% against 4.3% nationwide.
Unemployment rate
4.1%
U.S. 4.1%
Tied for 22nd highest among the states, August 2026
Drop in federal government jobs
18.1%
All states and D.C. together 10.0%
Highest among the states, January 2025 to August 2026
Drop in all jobs
1.2%
3rd highest among the states, January 2025 to August 2026
Maryland’s jobless rate ran below the nation’s for most of the time since 1990; in 2026 it caught up and, for four months, passed it
Unemployment rate, seasonally adjusted, for Maryland and the U.S., monthly from January 1990 through August 2026. October 2025 is blank because the federal shutdown stopped that month’s count.
Maryland lost a larger share of its federal jobs than any other state
Federal government jobs located in Maryland fell from 162,000 in January 2025 to 132,700 in August 2026, a loss of 29,300, or 18.1%. No other state lost as large a share; across the 50 states and D.C. together, federal jobs fell 10.0%. The sharpest drop came in one month, from 147,000 in September 2025 to 137,300 in October. Counting every employer, Maryland had 33,700 fewer jobs in August 2026 than in January 2025. The drop of 1.2% was 3rd highest among the 50 states and D.C. (U.S. Bureau of Labor Statistics, Current Employment Statistics). August figures are preliminary; we calculated the changes.
Federal jobs were 4.7% of all jobs in Maryland in August 2026, the 3rd highest share after D.C. and Hawaii. Two cautions. These counts place each job where the employer is, not where the worker lives, so they leave out Marylanders who work for federal agencies in D.C. or Virginia. And Maryland’s unemployment rate had already been rising since mid-2023, well before January 2025, when these counts begin.
| State | Jan. 2025 | Aug. 2026 | Drop |
|---|---|---|---|
| Maryland Drop 18.1% | 162,000 Aug. 2026 132,700 | 132,700 | 18.1% |
| D.C. Drop 14.6% | 192,200 Aug. 2026 164,200 | 164,200 | 14.6% |
| Alaska Drop 14.1% | 15,600 Aug. 2026 13,400 | 13,400 | 14.1% |
| Virginia Drop 13.4% | 195,700 Aug. 2026 169,500 | 169,500 | 13.4% |
| Utah Drop 12.9% | 41,700 Aug. 2026 36,300 | 36,300 | 12.9% |
Federal government jobs located in each place, seasonally adjusted; August 2026 is preliminary. Source: U.S. Bureau of Labor Statistics, Current Employment Statistics (State and Area); the drop is our calculation. Unemployment in every state →
Unemployment is highest in Baltimore City
| Place | Rate |
|---|---|
| Baltimore City | 5.5% |
| Allegany | 5.1% |
| Charles | 4.6% |
| Dorchester | 4.5% |
| Prince George’s | 4.4% |
| Somerset | 4.4% |
| Montgomery | 3.5% |
| Carroll | 3.0% |
| Queen Anne’s | 3.0% |
Unemployment rate, August 2026, not adjusted for seasonal swings: the six highest of Maryland’s 23 counties and Baltimore City (Prince George’s and Somerset tie), Montgomery, the most populous county, and the two lowest, which tie. Source: U.S. Bureau of Labor Statistics.
Is Maryland a rich state?
By income, yes. Maryland’s typical household earned $102,835 in 2024, the 4th highest of the 50 states and D.C., against $81,604 for the U.S., and 9.2% of residents lived in poverty, against 12.1% nationwide (U.S. Census Bureau, Small Area Income and Poverty Estimates). Counted per resident instead of per household, income was $79,259 in 2024, the 11th highest (U.S. Bureau of Economic Analysis).
Inside the state, incomes split widely: Howard County’s typical household earned $149,980 in 2024 and Somerset County’s $53,022 (see the counties).
Maryland’s poverty rate has been below the nation’s in every year we hold since 1989
Share of people living below the poverty line, Maryland and the U.S., 1989 to 2024. The Census Bureau made no state estimates for 1990 to 1992 or 1994.
Unemployment benefits are claimed through Maryland’s labor department. The state minimum wage is $15 an hour; Howard, Montgomery and Prince George’s counties set higher rates (Maryland’s labor department).
How many Marylanders are behind on their debts?
About the same share as across the country. In early 2025, 17.2% of Marylanders with a credit record had a debt 90 or more days late, tied for 21st highest among the 50 states and D.C. and level with the U.S. share (Federal Reserve Bank of Philadelphia). The national share is our average of the states, weighted by population. The bigger difference is in how much Marylanders owe.
Ranks among the 50 states and D.C. (1 = highest): cards 19th highest, car loans tied for 18th highest, mortgages tied for 14th highest, collections 23rd highest. The U.S. bars average the states, weighting each by its population (our calculation).
Fewer Marylanders have a debt in collections than at the end of 2019: 12.5% of people with a credit record in early 2025, down from 19.3%. Most of that fall came between early 2022 and mid-2023, from 15.6% to 11.0%, the same months the three big credit bureaus removed many medical debts from reports. Across the country the share of people with a medical collection fell from about 14% in March 2022 to about 5% in June 2023 (Consumer Financial Protection Bureau). Since mid-2023 Maryland’s share has edged back up.
Marylanders owe more than most Americans
Debt measured in dollars tells a different story. Household debt equaled 103% of a year’s income per person in Maryland, the 6th highest ratio of the 50 states and D.C. The national ratio was 86%. We calculated both from Federal Reserve Bank of New York debt at the end of 2025 and U.S. Bureau of Economic Analysis income for 2024. By the New York Fed’s count of balances, 6.0% of Maryland’s car-loan dollars were 90 or more days late at the end of 2025, the 13th highest share, against 5.2% nationwide.
| Loan type | Maryland | U.S. | Maryland 2019 | U.S. 2019 |
|---|---|---|---|---|
| Credit card | 11.7% End of 2025 U.S. 12.4% Maryland 2019 7.4% · U.S. 2019 8.1% | 12.4% | 7.4% | 8.1% |
| Auto loan | 6.0% End of 2025 U.S. 5.2% Maryland 2019 5.1% · U.S. 2019 4.9% | 5.2% | 5.1% | 4.9% |
| Mortgage | 1.1% End of 2025 U.S. 0.9% Maryland 2019 1.3% · U.S. 2019 1.0% | 0.9% | 1.3% | 1.0% |
Share of balances 90 or more days late at the end of 2025 and the end of 2019 (Federal Reserve Bank of New York, Consumer Credit Panel / Equifax). It counts dollars, not people, so it doesn’t match the Philadelphia Fed’s shares above, and written-off debts that lenders keep reporting stay in it.
Home equity matches the U.S.; mortgages 30 to 89 days late run a bit higher
In the second quarter of 2026, 4.8% of Maryland mortgages had less than 10% equity, against 4.7% nationwide (Federal Housing Finance Agency). Equity means the home’s value minus the loan balance still owed.
| Measure | Maryland | U.S. | Rank |
|---|---|---|---|
| Mortgages with less than 10% equity, April to June 2026 19th highest | 4.8% U.S. 4.7% | 4.7% | 19th highest |
| Mortgages 30 to 89 days late, Sept. 2025 Tied for 14th highest | 1.9% U.S. 1.6% | 1.6% | Tied for 14th highest |
Rank among the 50 states and D.C., 1 = the highest share. Equity: Federal Housing Finance Agency. Payments 30 to 89 days late, an early stage of falling behind: Consumer Financial Protection Bureau. Late payments in every state →
Maryland’s bankruptcy filings are at their highest since 2019
Bankruptcy cases filed in Maryland rose 11.7% in 2025, to 12,405, more than in any year since 2019, when 17,488 were filed (Administrative Office of the U.S. Courts). That was the third rise in a row after a low of 7,442 in 2022, and filings kept climbing: 13,503 cases were filed in the 12 months to June 2026. Per resident, Maryland had 198.1 filings for every 100,000 people in 2025 (2024 population), 15th highest among the 50 states and D.C., against 167.1 nationwide.
More than a third of Maryland’s 2025 filings, 36.3%, were under Chapter 13, in which the filer repays part of what they owe through a court-approved plan, close to the U.S. share of 35.9%. Most of the rest were under Chapter 7, which can wipe out many debts.
For cases filed from June 1, 2026, Maryland protects up to $125,000 in a home the filer lives in (see what changed). People searching for Maryland’s homestead exemption often mean the Homestead Property Tax Credit, a separate property-tax program; the bankruptcy exemption is what shields part of a home’s value from creditors in a bankruptcy case.
| Year | Filings |
|---|---|
| 2010 | 29,698 |
| 2019 | 17,488 |
| 2020 | 11,249 |
| 2021 | 8,323 |
| 2022 | 7,442 |
| 2023 | 9,610 |
| 2024 | 11,108 |
| 2025 | 12,405 |
| July 2025 to June 2026 | 13,503 |
All chapters, by calendar year, plus the latest 12 months published, for the U.S. Bankruptcy Court for the District of Maryland. No year from 2006 through 2025 had more filings than 2010. Source: Administrative Office of the U.S. Courts, Table F-2. Bankruptcy filings in every state →
SNAP in Maryland: fewer people get food help than a year ago
In June 2026, 624,548 Marylanders got SNAP food benefits, once called food stamps, 6.1% fewer than the 665,084 who got them in June 2025 (U.S. Department of Agriculture). That’s 10.0% of residents (2024 population), 26th highest among the 50 states and D.C., against 10.7% nationwide. Most of the year’s drop came before anyone lost benefits under the wider federal work rules, which first cut people off in March 2026.
People getting SNAP
624,548
June 2026, U.S. Department of Agriculture
Share of residents getting SNAP
10.0%
U.S. 10.7%
26th highest among the states, June 2026 (2024 population)
Change from a year earlier
−6.1%
June 2025 to June 2026
The count fell by 23,111 from June 2025 to February 2026, before the first work-rule losses, and by 17,425 from February to June 2026, as they began. November 2025 stands apart: during the federal shutdown the count dropped to 625,814, from 665,503 in October, then came back to 651,955 in December (U.S. Department of Agriculture). No source we read explains the rest of the slide between October and February.
What changed in SNAP’s rules
Under the 2025 federal law, SNAP’s work rule now reaches adults up to age 64, up from 54, who have no child under 14 living with them. It took effect Nov. 1, 2025, and applies to current customers at their next renewal. Maryland’s human services department estimates that up to 80,000 more Marylanders may need to meet it. The law also made local waivers from the rule much harder to get. About 10,250 adults in Baltimore City and Dorchester, Kent, Somerset and Worcester counties had been spared under such waivers; by September 2025 the department said no Maryland place had one. On July 1, 2026, the state restarted the rule’s three-year clock (see what changed).
Fewer people on SNAP isn’t proof that fewer need it. The program still reaches a larger share of Marylanders than the Census Bureau counts as poor (see Is Maryland a rich state?).
Apply for SNAP at myMDTHINK, the state’s benefits site →
What changed in Maryland in the past year
-
Aug. 28, 2026
Pepco’s electric rates go up in Montgomery and Prince George’s
The Maryland Public Service Commission allowed Pepco to raise its rates by $50.9 million a year, less than half the $119.9 million the utility asked for. The commission put the cost for the average home customer at $3.94 more a month, with the new rates taking effect the day of the decision. It also opened a second phase to consider taking out of rates certain costs named in this year’s Utility RELIEF Act.
-
July 28, 2026
Paid sign-ups for marketplace health coverage drop in Maryland
Paid enrollment in health plans bought through Maryland’s marketplace fell 5% from 2025 to 2026, KFF found in its analysis of federal figures, against 12% nationwide. The larger federal help toward premiums ended after 2025; Maryland is one of the states that adds a subsidy of its own.
-
July 1, 2026
Maryland restarts the three-year clock on SNAP’s work rule
Maryland’s human services department restarted the three-year period over which SNAP’s work rule counts months of benefits. Adults who lost benefits for not meeting the rule, or who used up their three months, can apply for a new three months of benefits if they otherwise qualify. Our latest monthly SNAP count, for June, comes before the reset (see SNAP).
Maryland’s human services department, “Did You Lose Your SNAP Benefits?”, July 29, 2026
-
June 1, 2026
A bigger home exemption in bankruptcy
For bankruptcy cases filed on or after June 1, 2026, Maryland law protects up to $125,000 in a home the filer lives in, the most for one home even when more than one person in the case claims it, under a law Gov. Wes Moore signed May 12. The protection now also covers a home held in a revocable trust, and from fiscal 2028 the amount is set to be adjusted each year for inflation (see bankruptcy).
-
March 3, 2026
The first Marylanders lose SNAP under wider work rules
Maryland’s human services department said the first SNAP customers would lose benefits that month under federal work rules that took effect Nov. 1, 2025. The rules now cover adults up to age 64 who have no child under 14 living with them, and they apply to current customers at their next renewal. The department estimates that up to 80,000 more Marylanders may need to meet them (see SNAP).
-
Nov. 3, 2025
State money goes toward November SNAP benefits during the shutdown
With November food benefits held up by the federal shutdown, Gov. Wes Moore released $62 million in state money toward paying them in full. The governor’s office said a federal judge had ordered the U.S. Department of Agriculture to use contingency funds, and the Trump administration said in court it would cover only up to half of benefits. The number of Marylanders getting SNAP dipped in November and rose again in December (see SNAP).
How foreclosure works in Maryland
Maryland foreclosures go through the courts: the lender files the case in the county’s Circuit Court. There’s usually no trial; the court reviews the sale after it happens and approves it unless someone files an objection. The lender must first send a notice of intent to foreclose at least 45 days before filing, and can’t file until 90 days after you fall behind or 45 days after that notice, whichever is later (Md. Code, Real Prop. § 7-105.1). If you live in the home, you can ask for foreclosure mediation, a meeting with the lender and an administrative law judge from the state’s Office of Administrative Hearings. It isn’t automatic: you file the request with the Circuit Court and pay a $50 fee. You can stop the sale by paying everything past due, with penalties and fees, up to 1 business day before it (§ 7-105.1(p)). Once the home is sold, there’s no right to buy it back: Maryland’s highest court held in 1967 that this right ends at the sale (Butler v. Daum), and the court’s approval passes your title to the buyer (§ 7-105(c)). If the sale brings in less than you owe, the lender can ask the court for the rest within 3 years (§ 7-105.17). Under federal rules, a mortgage company generally can’t make the first foreclosure filing until the loan is more than 120 days behind.
- Goes through a court
- Yes
- Notice before the case is filed
- 45 days
- Earliest filing after falling behind
- 90 days
- Foreclosure mediation
- On request
- Last chance to pay what’s due and stop the sale
- 1 business day before
- Buy-back right after the sale
- None
- Time to seek the leftover balance
- 3 years
What the law says for a home you live in. Sources: Maryland Code, Real Property §§ 7-105, 7-105.1 and 7-105.17; Butler v. Daum, 245 Md. 447 (1967); the Office of Administrative Hearings’ foreclosure mediation page; federal rule 12 CFR 1024.41. How foreclosure works in Maryland →
The federal Homeowner Assistance Fund gave Maryland $248.6 million for pandemic-era mortgage help; 26,053 households had been helped through early 2026, U.S. Treasury figures show.
Maryland mortgage complaints: what homeowners report to the CFPB
Marylanders have sent 16,876 complaints about mortgages to the Consumer Financial Protection Bureau, counting from 2012. The most common issue is loan modifications, collection and foreclosure (4,313), ahead of trouble during the payment process (3,868), then loan servicing, payments or escrow (2,793).
- Oct. 2, 2026 United Wholesale Mortgage (UWM) Trouble during payment process: Trying to communicate with the company to fix an issue while managing or servicing your loan In progress
- Oct. 1, 2026 Selene Finance Struggling to pay mortgage: Applying for or obtaining a modification, forbearance plan, short sale, or deed-in-lieu Closed with explanation
- Sept. 30, 2026 Carrington Mortgage Trouble during payment process: Trying to communicate with the company to fix an issue while managing or servicing your loan In progress
- Sept. 30, 2026 Wells Fargo Struggling to pay mortgage: Applying for or obtaining a modification, forbearance plan, short sale, or deed-in-lieu In progress
- Sept. 29, 2026 Wells Fargo Struggling to pay mortgage: Foreclosure In progress
- Sept. 29, 2026 Carrington Mortgage Trouble during payment process: Payment process In progress
- Sept. 29, 2026 Shellpoint / NewRez Struggling to pay mortgage: Foreclosure Closed with explanation
- Sept. 29, 2026 Solar Mosaic LLC Trouble during payment process: Loan sold or transferred to another company Closed with explanation
- Sept. 28, 2026 Carrington Mortgage Trouble during payment process: Trying to communicate with the company to fix an issue while managing or servicing your loan In progress
- Sept. 27, 2026 CMG Financial Trouble during payment process: Private mortgage insurance (PMI) Closed with explanation
The latest ten Maryland complaints about making payments on a mortgage or getting help with one, newest first, as the Consumer Financial Protection Bureau’s public database showed them on Oct. 14, 2026. We leave out complaints about getting a new loan and those naming a credit reporting company. Each complaint is one person’s account, which the bureau doesn’t verify, and a complaint isn’t a finding against the company. Every Maryland mortgage complaint at the CFPB →
What to watch before the next edition
Four dates before the next edition, nearest first: two data releases and two steps in BGE’s request to change its electric rates.
-
Oct. 20, 2026
The September state jobs report
Maryland’s labor department plans to release the state’s September unemployment rate and job counts, from the Bureau of Labor Statistics’ two state surveys, including the next count of federal jobs located in Maryland.
-
Oct. 26, 2026
Public hearings on BGE’s electric rate request begin
The Maryland Public Service Commission holds virtual public comment hearings on Baltimore Gas and Electric’s application to change its electric base rates (Case No. 9888) on Oct. 26 and Nov. 4. A third hearing, on Nov. 18, is set to be held in person.
Maryland Public Service Commission, Oct. 2, 2026; Oct. 6, 2026
-
Nov. 20, 2026
The October state jobs report
Maryland’s labor department plans to release October’s statewide unemployment rate and job counts. There is no October 2025 unemployment rate to set it against: the federal shutdown left that month without one.
-
Dec. 23, 2026
Written comments on BGE’s request are due
Written comments on BGE’s electric rate application (Case No. 9888) are due to the Maryland Public Service Commission by this date.
Where Maryland ranks highest and lowest
| Measure | Maryland | U.S. | Rank | Latest data |
|---|---|---|---|---|
| Median household income 4th highest · 2024 | $102,835 U.S. $81,604 | $81,604 | 4th highest | 2024 |
| Credit card debt per person with a credit report 5th highest · End of 2025 | $5,090 U.S. $4,350 | $4,350 | 5th highest | End of 2025 |
| Household debt per person with a credit report 7th highest · End of 2025 | $81,390 U.S. $63,200 | $63,200 | 7th highest | End of 2025 |
| Household debt as a share of income per person 6th highest · 2025 | 103% U.S. 86% | 86% | 6th highest | 2025 |
| Median rent, a month 8th highest · 2024* | $1,705 U.S. $1,413 | $1,413 | 8th highest | 2024* |
| Renters spending at least 30% of income on housing 11th highest · 2024* | 48.7% U.S. 47.6% | 47.6% | 11th highest | 2024* |
| Drop in federal government jobs since January 2025 Highest · Aug. 2026 | 18.1% U.S. 10.0% | 10.0% | Highest | Aug. 2026 |
| Income per person 11th highest · 2024 | $79,259 U.S. $73,204 | $73,204 | 11th highest | 2024 |
| Car-loan balances 90+ days late 13th highest · End of 2025 | 6.0% U.S. 5.2% | 5.2% | 13th highest | End of 2025 |
| Bankruptcy filings per 100,000 residents (2024 population) 15th highest · 2025 | 198.1 U.S. 167.1 | 167.1 | 15th highest | 2025 |
| People with a debt 90+ days late Tied for 21st highest · Early 2025 | 17.2% U.S. 17.2% | 17.2% | Tied for 21st highest | Early 2025 |
| Unemployment rate, three-month average Tied for 22nd highest · June–August 2026 | 4.2% U.S. 4.1% | 4.1% | Tied for 22nd highest | June–August 2026 |
| Residents getting SNAP food benefits (2024 population) 26th highest · June 2026 | 10.0% U.S. 10.7% | 10.7% | 26th highest | June 2026 |
| Population growth since 2020 17th lowest · 2025 | 1.4% U.S. 3.1% | 3.1% | 17th lowest | 2025 |
| Residents in poverty Tied for 3rd lowest · 2024 | 9.2% U.S. 12.1% | 12.1% | Tied for 3rd lowest | 2024 |
Ranks compare Maryland with the 50 states and D.C.; “highest” is counted from the top of the list and “lowest” from the bottom. * Census five-year survey, 2020 to 2024. Debt as a share of income: debt per person at the end of 2025 divided by income per person in 2024 (Federal Reserve Bank of New York; Bureau of Economic Analysis), our calculation. Federal jobs: January 2025 to August 2026, August preliminary (Bureau of Labor Statistics), our calculation; its U.S. column is the total for the 50 states and D.C. combined. Population growth: Census Bureau estimates, with the U.S. column again the total for the 50 states and D.C. combined. People with a debt 90+ days late: Federal Reserve Bank of Philadelphia, counting people who have a credit record, with a U.S. column that is our average of the states weighted by population. Every row’s source is in Sources and method. Download this table: CSV.
Questions about Maryland
Is Maryland a rich state?
By income, yes. Its typical household earned $102,835 in 2024, the 4th highest of the 50 states and D.C., and its poverty rate, 9.2%, was tied for 3rd lowest (U.S. Census Bureau, Small Area Income and Poverty Estimates). Still, on our State Distress Index it is the 16th most distressed, more distressed than 70% of the other states and D.C., because on late payments, bankruptcy, jobs and renters’ costs it sits a little above the middle.
Is Maryland expensive to live in?
For housing, yes. Maryland’s median rent, $1,705 a month in 2020 to 2024, was the 8th highest of the 50 states and D.C. (U.S. Census Bureau). The MIT Living Wage Calculator puts a single adult’s basic yearly costs at $53,949, the 11th highest. We don’t measure other prices, so we can’t rank the whole cost of living.
How is Maryland’s economy doing?
Its unemployment rate, 4.1% in August 2026, matched the nation’s after years below it (U.S. Bureau of Labor Statistics). From January 2025 to August 2026, federal government jobs located in Maryland fell 18.1%, the largest share of any state, and all jobs fell 1.2% (Bureau of Labor Statistics data, our calculation; August is preliminary).
What is the richest county in Maryland, and the poorest?
Howard County has the highest typical household income, $149,980 in 2024, and Somerset County the highest poverty rate, 20.3% (U.S. Census Bureau, Small Area Income and Poverty Estimates). On our County Distress Index, Howard is the least distressed place in Maryland and Baltimore City the most.
What is Maryland’s poverty line?
Most aid programs use the federal poverty guidelines. In 2026, they are $15,960 a year for one person and $33,000 for a family of four. Maryland uses the same figures as every state except Alaska and Hawaii (U.S. Department of Health and Human Services). The 9.2% poverty rate on this page comes from the Census Bureau’s own, separate poverty measure.
Are people moving out of Maryland?
We don’t track who moves in or out. Census Bureau estimates show Maryland’s population grew 1.4% from 2020 to 2025, to 6,265,347, the 17th lowest growth of the 50 states and D.C. and below the U.S. figure of 3.1% (our sum of the states).
Cite or reuse Maryland’s data
Quote or reuse these figures freely, with credit, in reporting, research or grant writing.
State Distress Index
Maryland
16thmost distressed state
of the 50 states and D.C.
More distressed than 70% of the other states and D.C.
Maryland ranks 16th most distressed on American Default Research’s State Distress Index among the 50 states and D.C.. The index measures strain on household finances. Yet Maryland’s median household income was $102,835 in 2024, the 4th highest in the country (U.S. Census Bureau). Marylanders carried $81,390 of household debt per person with a credit report at the end of 2025, the 7th highest (Federal Reserve Bank of New York). From January 2025 to August 2026, federal government jobs located in Maryland fell 18.1%, the largest share of any state (U.S. Bureau of Labor Statistics; our calculation).
For interviews or a custom cut of the data, write to press@americandefault.org
Sources and method
We gather the data, run the numbers and research each state ourselves.
This edition: October 2026 · Next edition expected March 2027
- Unemployment rates for Maryland, its counties and the U.S., by month and yearU.S. Bureau of Labor Statistics, Local Area Unemployment StatisticsJan. 1990 to Aug. 2026
- Federal government jobs and all jobs, by stateU.S. Bureau of Labor Statistics, Current Employment Statistics (State and Area)Jan. 2025 to Aug. 2026 (August preliminary)
- Poverty and household incomeCensus Bureau, Small Area Income and Poverty Estimates1989 to 2024
- Renter households spending half their income or more on housingCensus Bureau, American Community Survey, one-year estimates2005 to 2024
- Rent and renters’ costsCensus Bureau, American Community Survey, five-year estimates2020 to 2024
- PopulationCensus Bureau, population estimates; decennial census for Baltimore City2020 to 2025; 1950 and 2020
- Income per personBureau of Economic Analysis2024
- Late payments and collectionsFederal Reserve Bank of Philadelphia, Consumer Credit Explorerend of 2019 to early 2025
- Household debt and dollars behindFederal Reserve Bank of New York, Consumer Credit Panel / Equifaxend of 2019 and end of 2025
- Mortgages with little equityFederal Housing Finance Agency, National Mortgage Databasesecond quarter of 2026
- Mortgages 30 to 89 days late; mortgage complaints; medical debts on credit reportsConsumer Financial Protection Bureau: Mortgage Performance Trends; complaint database; Recent changes in medical collections on consumer credit recordsSept. 2025; Oct. 14, 2026; March 2022 to June 2023
- Bankruptcy filingsAdministrative Office of the U.S. Courts, Table F-22006 to June 2026
- Bankruptcy home exemption2026 Laws of Maryland, Chapter 400 (Senate Bill 939)signed May 12, 2026
- SNAPU.S. Department of Agriculture Food and Nutrition AdministrationJune 2025 to June 2026
- SNAP rules in MarylandMaryland’s human services department: fact sheet on the 2025 federal law; work-rule release; the clock resetSept. 19, 2025; March 3, 2026; July 29, 2026
- Cost of getting byMIT Living Wage CalculatorFebruary 2026 update
- Mortgage help fundU.S. Treasury, Homeowner Assistance Fundthrough early 2026
- Foreclosure lawMaryland Code, Real Property § 7-105, § 7-105.1 and § 7-105.17; Office of Administrative Hearings; 12 CFR 1024.41as of 2026
- Minimum wage and unemployment claimsMaryland’s labor department2026
- Poverty guidelineU.S. Department of Health and Human Services2026
- Housing counselorsU.S. Department of Housing and Urban DevelopmentOctober 2026
- What changed and what to watchMaryland Public Service Commission (BGE charge, Dec. 22, 2025; BGE hearings), KFF, Office of Governor Wes Moore, Maryland’s labor department release dates, Census Bureau release schedule; every dated item links the page it was read on (see what changed)Nov. 2025 to Dec. 2026
- PhotoEli Pousson, Baltimore Heritage, via Wikimedia Commons, CC02011
The score has four equal parts: renters’ housing costs; late payments; collections and bankruptcy; and jobs. We score each measure against all 50 states and D.C.; Maryland’s score is the percentage of the other 50 places whose four-part average is lower than its own. The full method →
We write with AI tools, and Ross Kilburn checks and reviews every page before it's published.
Get the next Maryland edition by email
One email each time a new Maryland edition is out; the next is expected in March 2027. Unsubscribe anytime.
Thanks, that helps.