State Distress Index · SDI
Connecticut
most distressed state
of the 50 states and D.C.
Connecticut’s unemployment was 5.1% in August 2026, tied for 2nd highest nationally
Each state is shaded by how distressed its households are, from green (least) to red (most), with data through September 2026. Connecticut scores 74 out of 100.
Connecticut’s August 2026 unemployment rate was 5.1%, tied for 2nd highest among the 50 states and D.C., even though its income per person ranked 2nd highest. Renters’ housing costs also push up its distress score of 74. Unpaid loans are less common than in most states. Greater Bridgeport and the Naugatuck Valley are the most distressed planning regions; Lower Connecticut River Valley is the least.
- Score
- 74/100
- Data through
- September 2026
- Edition
- October 2026
Next edition expected March 2027
How Connecticut ranks among the states
On financial distress Connecticut is tied for 13th of the 50 states and D.C., and debt isn’t what puts it there. Its homeowners have the lowest share of mortgages with little equity. Its residents are less likely than most Americans to be 90 days behind on a card or car loan. What lifts the score is work: the state’s unemployment rate rose from 3.5% at the end of 2024 to 5.2% in June and July 2026 without a single monthly dip. The jobs part of its score is now 2nd highest. Renters’ housing costs, a part where it ranks 5th highest, add the rest.
What drives the score
The score has four parts. Each measure behind a part gets a score from 0 to 100 for where Connecticut falls among the 50 states and D.C., and each part averages its measures. Connecticut’s four parts average 67. Every other state and D.C. has an average of its own, and 74% of them are lower than Connecticut’s. That share, 74, is the score.
- Jobs97The June-to-August 2026 unemployment average was 5.2%; the U.S. figure was 4.1%
- Renters’ housing costs91In 2024, 27.8% of renter households paid half or more of their income for housing (U.S. 26.1%)
- Late payments44Card and car-loan borrowers fall 90 days behind less often than nationwide; mortgage borrowers slightly more often (early 2025)
- Collections and bankruptcy36A smaller share of people with a debt in collections than most states (early 2025) and a low bankruptcy filing rate (2025)
Beside its neighbors
Connecticut is more distressed than all three states that border it. New York comes closest; Rhode Island and Massachusetts score far lower.
- Connecticut 74
- New York 60
- Rhode Island 32
- Massachusetts 36
State Distress Index score, 0 to 100. The gap is jobs: Connecticut’s jobs part is 97, against 69 in New York, 69 in Massachusetts and 45 in Rhode Island. In August 2026 unemployment was 4.3% in New York, 4.3% in Massachusetts and 3.7% in Rhode Island (Bureau of Labor Statistics). On renters’ costs New York scores higher, 93 to Connecticut’s 91.
Jobs moved the score most: up in 2020, down through 2024, up again since early 2025
At its worst
Tied for 11th most distressed (with Michigan), with a score of 78, in the third quarter of 2020, up from 58 a quarter earlier. The jobs part leapt from 42 to 81 as unemployment surged in the pandemic, peaking at 11.9% in May 2020; the other three parts barely moved.
By early 2025
Ranked 26th, with a score of 50, after easing to 42 (30th) at the end of 2024, when the jobs part was down to 35. Its least distressed quarters were at the start of our full history: 39th, with a score of 24, in the third quarter of 2006 and the second quarter of 2007.
Why today differs
Jobs again. Since the chart’s last quarter, the jobs part has climbed from 41 to 97, while the other three parts moved four points or less. That leaves Connecticut tied for 13th today, with a score of 74.
Connecticut was tied for 11th most distressed state in the third quarter of 2020, its worst point; by early 2025 it had eased to 26th
Connecticut’s State Distress Index score each quarter, 0 to 100, mid-2006 to early 2025.
Is Connecticut expensive to live in?
Expensive, and hardest on renters. MIT’s Living Wage Calculator puts basic costs for a single adult with no children at $54,178 a year before taxes, the 9th highest of the 50 states and D.C. overall. For two working parents with two children, it estimates $149,091, the 5th highest (2025 dollars). In 2024, 27.8% of Connecticut renter households paid half or more of their income for rent and utilities, the 7th highest share (Census Bureau). Home prices rose 6.1% in 2025, the 2nd highest increase among the 50 states and D.C., against 2.9% nationwide (Federal Housing Finance Agency). We don’t measure food, insurance or electricity prices, so we can’t rank the overall cost of living.
Basic budget, one adult, a year
$54,178
9th highest among the 50 states and D.C. (MIT, 2025 dollars)
Renters paying half or more of income for housing
27.8%
U.S. 26.1%
7th highest among the 50 states and D.C. (2024)
Home price growth
6.1%
U.S. 2.9%
2nd highest among the 50 states and D.C. (2025)
Connecticut renters have been more stretched than renters nationwide in every Census estimate since 2007
Share of renter households whose rent and utilities take half or more of their income, Connecticut and the U.S., 2005 to 2024. The Census Bureau released no one-year figures for 2020.
Why is Connecticut so expensive?
Rent alone isn’t the reason: the median, $1,488 a month from 2020 to 2024, was 17th highest among the 50 states and D.C., a little above the U.S. $1,413 (Census Bureau). The strain shows when costs meet income. Renters’ housing costs take a bigger share of income than in most states, and so do owners’: 26.4% of homeowners spent 30% or more of it on housing costs, tied for 7th highest (2020 to 2024). We don’t hold data on taxes, child care or energy prices, so we can’t say how much each adds.
In April, state regulators approved interim residential rate cuts from May 1, 2026. They put the savings at about $30 a month on an average Eversource bill and about $34 on an average United Illuminating bill. In July, Eversource asked for a yearly increase of $727 million (see what changed).
Rent costs less than in Massachusetts or New York, more than in Rhode Island
| Measure | Connecticut | Massachusetts | New York | Rhode Island |
|---|---|---|---|---|
| Median rent, a month, 2020 to 2024 New York $1,621 · Rhode Island $1,342 | $1,488 Massachusetts $1,762 | $1,762 | $1,621 | $1,342 |
| Median rent as a share of median household income New York 22.7% · Rhode Island 19.3% | 18.7% Massachusetts 20.2% | 20.2% | 22.7% | 19.3% |
| Renters paying half or more of income, 2024 New York 28.6% · Rhode Island 26.2% | 27.8% Massachusetts 26.0% | 26.0% | 28.6% | 26.2% |
| Homes their owners live in, 2020 to 2024 New York 54.3% · Rhode Island 63.6% | 66.5% Massachusetts 62.5% | 62.5% | 54.3% | 63.6% |
Set against typical household income, Connecticut’s rent is the lowest of the four, yet its share of renters paying half their income is second only to New York’s. Sources: Census Bureau, American Community Survey (five-year figures for rent and owner-occupied homes, one-year figures for renters paying half their income) and Small Area Income and Poverty Estimates. We work out rent as a share of income by multiplying the 2020 to 2024 median monthly rent by 12 and dividing by 2024 median household income.
Connecticut counties and planning regions: where distress runs highest
Greater Bridgeport is the most distressed planning region, with a score of 61: it is more distressed than 61% of the other U.S. counties and county equivalents. Naugatuck Valley, around Waterbury, is next at 58, and it is the poorest: 12.5% of its residents lived in poverty in 2024 (Census Bureau, Small Area Income and Poverty Estimates). Lower Connecticut River Valley, around Middletown, is the least distressed. Connecticut’s eight counties stopped working as governments in 1960, and since late 2022 the Census Bureau has published the state’s data for 9 planning regions instead (Census Bureau notice, June 6, 2022). Our County Distress Index scores each region alongside every U.S. county. None of the nine is among the 100 most or least distressed U.S. counties and county equivalents.
Distress is highest around Bridgeport, Waterbury and New Haven, and lowest along the lower Connecticut River and in the northeast
Each of Connecticut’s 9 planning regions shaded by its County Distress Index score (0 to 100), with data through August 2026.
Loading the planning region map…
The planning region map could not be loaded. Every planning region is in the lists on this page.
Most distressed
| Rank | Planning region | Score | Poverty |
|---|---|---|---|
| 1 | Greater Bridgeport Planning Region | 61 | 11.4% |
| 2 | Naugatuck Valley Planning Region | 58 | 12.5% |
| 3 | South Central Connecticut Planning Region | 55 | 11.5% |
| 4 | Capitol Planning Region | 51 | 10.4% |
| 5 | Southeastern Connecticut Planning Region | 47 | 9.6% |
Least distressed
| Rank | Planning region | Score | Poverty |
|---|---|---|---|
| 6 | Northwest Hills Planning Region | 42 | 8.6% |
| 7 | Western Connecticut Planning Region | 40 | 7.8% |
| 8 | Northeastern Connecticut Planning Region | 35 | 7.7% |
| 9 | Lower Connecticut River Valley Planning Region | 35 | 7.2% |
Rank among Connecticut’s 9 planning regions, 1 = most distressed. Ranks follow unrounded scores, so Northeastern Connecticut and Lower Connecticut River Valley both show 35 but rank apart. Poverty: Census Bureau, 2024.
Every planning region, by score
No Connecticut region scores 70 or more. Four score 50 or more: Greater Bridgeport, Naugatuck Valley, South Central Connecticut and the Capitol region around Hartford, the state capital. The other five score from 35 to 47.
The poorest regions are the most distressed, but not in the same order
Our region score has five equal parts: late payments; collections and bankruptcy; jobs; renters’ housing costs; and a fifth built from poverty, child poverty, disability, health insurance and household income. In Connecticut the four poorest regions are also the four most distressed, but the order differs. Greater Bridgeport has the 3rd highest poverty rate of the nine, yet it is the most distressed. It scores highest of the nine on renters’ housing costs and on jobs. Below the top four, distress follows poverty in the same order, from Southeastern Connecticut down to Lower Connecticut River Valley. Western Connecticut, around Danbury, has the highest typical household income, $130,842, and ranks 7th. Northeastern Connecticut, around Putnam, has the lowest renters’ housing costs of the nine but the third-highest jobs score. All nine regions score the same on late payments. Collections and bankruptcy still come from data for the eight old counties: each region takes the figures of the old county that held most of its people, so Naugatuck Valley shares that score with South Central, and Western with Greater Bridgeport.
The four regions with the least poverty
| Planning region | Poverty | Distress rank |
|---|---|---|
| Lower Connecticut River Valley Planning Region | 7.2% | 9th |
| Northeastern Connecticut Planning Region | 7.7% | 8th |
| Western Connecticut Planning Region | 7.8% | 7th |
| Northwest Hills Planning Region | 8.6% | 6th |
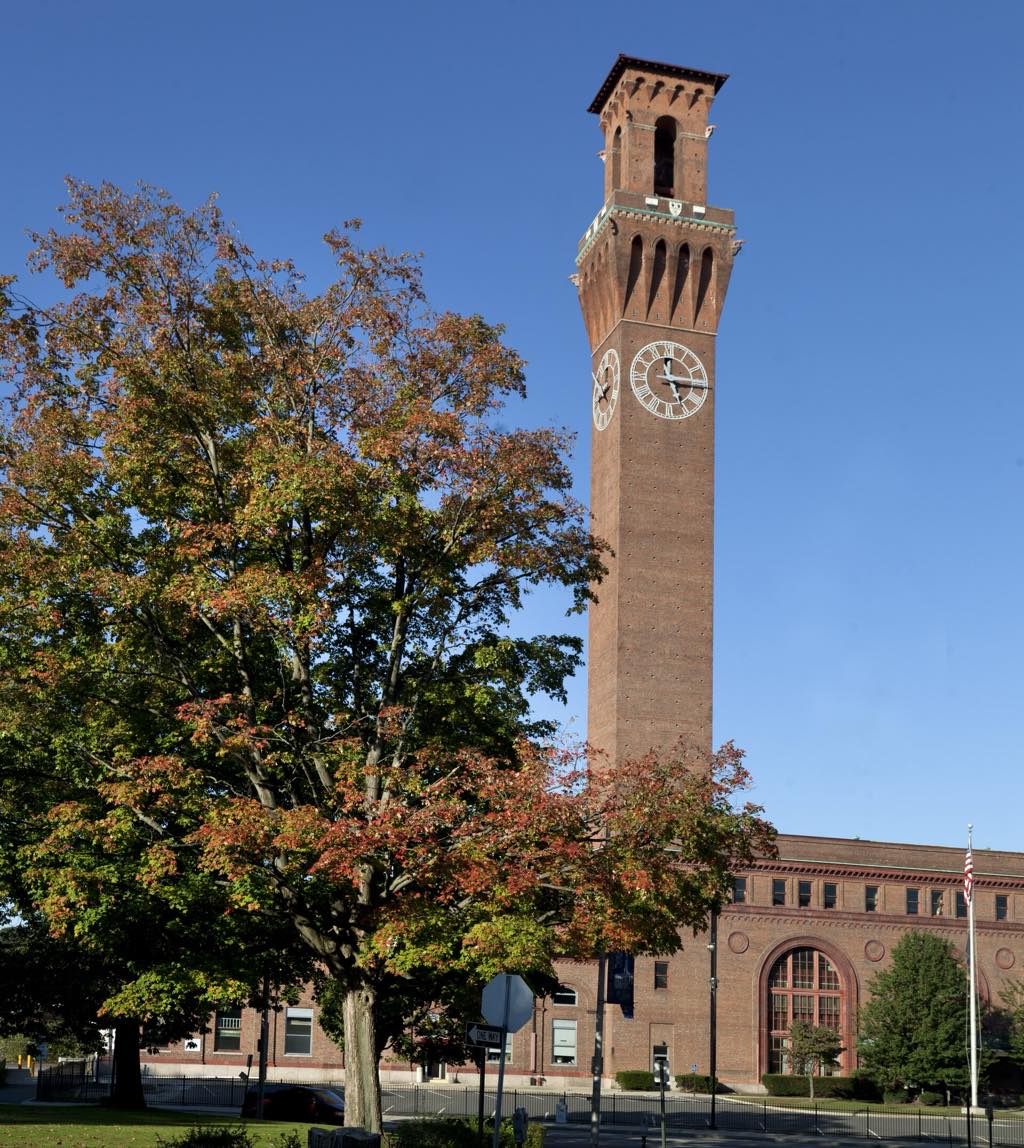
The clock tower of Union Station in Waterbury, in the Naugatuck Valley Planning Region, photographed in 2011. The region scores 58 on our County Distress Index, the second highest of Connecticut’s 9 planning regions, and its typical household earned $81,346 in 2024, the lowest of the nine (Census Bureau).
Source: U.S. Census Bureau. Photo: Carol M. Highsmith, Library of Congress, via Wikimedia Commons, public domain.
Greater Bridgeport has the highest jobless rate of the nine
Its unemployment rate was 5.6% in August 2026, the highest of Connecticut’s 9 regions, and renters’ housing costs weigh more on its score than on any other region’s. Greater Bridgeport was carved from old Fairfield County along with Western Connecticut, the richest region. Yet Greater Bridgeport is the most distressed of the state’s nine regions, and Western Connecticut ranks 7th.
American Default Research, County Distress Index; U.S. Bureau of Labor Statistics (August 2026, not adjusted for seasonal swings).
What’s behind Connecticut’s high unemployment rate?
The state’s labor department says the rise came mostly from people newly looking for work, not layoffs, but other figures don’t settle it. Connecticut’s unemployment rate was 5.1% in August 2026, tied for 2nd highest among the 50 states and D.C., against 4.1% for the U.S. (Bureau of Labor Statistics). It rose from 3.5% at the end of 2024 to 5.2% in June and July 2026, never dipping from one month to the next, the highest since November 2021. Meanwhile, the national rate in August 2026 was the same as in December 2024.
Unemployment rate
5.1%
U.S. 4.1%
Tied for 2nd highest among the 50 states and D.C. (August 2026)
Unemployment rate, 2025 average
4.0%
U.S. 4.3%
Below the nation’s for the year
Payroll jobs, June 2026
1,726,500
A record at the time; private-sector jobs set a new high in August, by the Connecticut Department of Labor’s count
Connecticut’s unemployment rate passed the nation’s in January 2026 and has stayed above it
Unemployment rate each month, Connecticut and the U.S., seasonally adjusted, January 1990 to August 2026. No figures were published for October 2025, during the federal shutdown.
Two explanations, and no answer yet
The Connecticut Department of Labor says the past year’s rise came mostly from people newly entering the job market, not from layoffs, and that claims for unemployment benefits are about where they were a year earlier (August report). That is the department’s own reading.
Not everything fits it. The same report says the state’s labor force shrank by 4,100 in August. CT Mirror had pointed out in July that the number of unemployed people was rising while the labor force shrank. Both trends push the jobless rate up (CT Mirror, July 21, 2026). State rates rest partly on a household survey, and the department notes that survey response rates remain lower than before the pandemic. A separate count from employers put payroll jobs at a record 1,726,500 in June, and private-sector jobs set a new high in August. We don’t know which picture is right; the coming months’ figures should help (see what to watch).
Unemployment is highest in Greater Bridgeport and the Naugatuck Valley
| Planning region | Rate |
|---|---|
| Greater Bridgeport | 5.6% |
| Naugatuck Valley | 5.5% |
| Capitol | 5.0% |
| South Central Connecticut | 4.9% |
| Northeastern Connecticut | 4.6% |
| Southeastern Connecticut | 4.3% |
| Western Connecticut | 3.9% |
| Northwest Hills | 3.9% |
| Lower Connecticut River Valley | 3.8% |
Unemployment rate in each of Connecticut’s 9 planning regions, August 2026, not adjusted for seasonal swings, so it differs from the statewide rate above. Source: Bureau of Labor Statistics.
Filing a claim, and the minimum wage
Claims for unemployment benefits are filed with the Connecticut Department of Labor.
The state minimum wage is $16.94 an hour in 2026 and is set to rise to $17.48 on Jan. 1, 2027 (Office of Governor Ned Lamont, Aug. 5, 2026).
Is Connecticut a rich state?
By income per person, yes: $95,067 in 2024, the 2nd highest among the 50 states and D.C., behind only D.C. (Bureau of Economic Analysis). The typical household is less far ahead. Median household income was $95,670, 12th highest, and 10.1% of residents lived in poverty, against 12.1% nationwide (Census Bureau, Small Area Income and Poverty Estimates, 2024). Income per person divides all income, including investment income, by every resident, so a smaller number of very high incomes can lift it well above what a typical household earns. We don’t hold a measure of how unequal incomes are.
Income per person
$95,067
U.S. $73,204
2nd highest among the 50 states and D.C. (2024)
Median household income
$95,670
U.S. $81,604
12th highest among the 50 states and D.C. (2024)
Residents in poverty
10.1%
U.S. 12.1%
Tied for 13th lowest among the 50 states and D.C. (2024)
Connecticut’s poverty rate is still below the nation’s, but it is higher than in 1989, while the U.S. rate is lower than then
Share of people living in poverty, Connecticut and the U.S., 1989 to 2024. The Census Bureau made no state estimates for 1990 to 1992 or 1994.
Investment income is a bigger share of Connecticut’s income than in most states
Investment income, such as dividends, interest and rent, made up 22.4% of all income in Connecticut in 2024, 12th highest among the 50 states and D.C. overall. Wages and salaries paid by employers in the state came to 43.6%, the 8th lowest share. The Bureau of Economic Analysis counts wages where people work, so pay residents earn in other states isn’t in it. Government benefits such as Social Security and Medicare were 14.5%, the 4th lowest.
Inside the state the gap is wide. Western Connecticut’s typical household earned $130,842 in 2024, about 1.6 times the $81,346 in the Naugatuck Valley (Census Bureau; see the regions). Our data stops at the 9 planning regions, so we can’t rank the richest or poorest towns.
SNAP enrollment has fallen every month since September 2024
In June 2026, 304,528 Connecticut residents got SNAP food benefits, 8.3% of the population, a share tied for 16th lowest among the 50 states and D.C., against 10.7% nationwide (U.S. Department of Agriculture). The count was 392,528 in September 2024 and has fallen every month since. It was already down to 338,147 by November 2025, before the Dec. 1, 2025 date from which the governor’s office counts residents losing SNAP under the new federal work rules for adults without dependents. The steepest one-month drop came later, from March to April 2026. A smaller count doesn’t mean fewer people need help, and it doesn’t say why people left (see the state’s grocery cards).
SNAP applications go through the Connecticut Department of Social Services →
Fewer Connecticut residents are behind on their bills than in most states
Among Connecticut residents with a credit record, 14.1% were 90 or more days late on at least one debt in early 2025, 20th lowest among the 50 states and D.C. overall. The U.S. share was 17.2% (Federal Reserve Bank of Philadelphia; we calculate the U.S. share as a population-weighted average of the states). These are household debts, owed by people, not the state government’s debt.
Connecticut among the 50 states and D.C.: collections tied for 19th lowest, card 23rd lowest, auto tied for 15th lowest, mortgage tied for 14th highest. The U.S. figure is a population-weighted average of the states that we calculate.
At the end of 2019, 15.9% of Connecticut residents with a credit record had a debt in collections, meaning an unpaid debt sent to a collector. In early 2025 the share was 10.4%. That drop doesn’t show fewer people struggling. The three big credit bureaus dropped many medical debts from credit reports in 2022 and 2023. Nationwide, the share of people with a medical collection on their record fell from about 14% in March 2022 to about 5% in June 2023 (Consumer Financial Protection Bureau). We don’t hold Connecticut’s own medical figure, so we can’t say how much of its drop that explains.
In 2019, more mortgage money was behind than in almost any state; by 2025 the share was near the U.S. rate
The Federal Reserve Bank of New York measures the share of money owed, not of borrowers, that is 90 or more days late. At the end of 2019, 1.8% of Connecticut’s mortgage balances were that far behind, the 2nd highest share of the 50 states and D.C. overall. By the end of 2025 the share was 1.0%, close to the U.S. figure of 0.9%, and smaller shares of card and auto balances were that far behind than nationwide. Connecticut residents do owe more than most: $67,530 per person with a credit report at the end of 2025, 16th highest, against $63,200 nationwide.
| Loan type | Connecticut | U.S. | Connecticut 2019 | U.S. 2019 |
|---|---|---|---|---|
| Credit card | 10.5% End of 2025 U.S. 12.4% Connecticut 2019 7.1% · U.S. 2019 8.1% | 12.4% | 7.1% | 8.1% |
| Auto loan | 3.1% End of 2025 U.S. 5.2% Connecticut 2019 3.1% · U.S. 2019 4.9% | 5.2% | 3.1% | 4.9% |
| Mortgage | 1.0% End of 2025 U.S. 0.9% Connecticut 2019 1.8% · U.S. 2019 1.0% | 0.9% | 1.8% | 1.0% |
Federal Reserve Bank of New York, Consumer Credit Panel / Equifax: the share of each kind of balance 90 or more days past due, at the end of 2025 and at the end of 2019. Because it measures dollars rather than borrowers, it isn’t comparable with the Philadelphia Fed chart above, and it counts written-off debts that lenders still report.
Homeowners have more cushion than in any other state
Only 1.1% of Connecticut mortgages had less than 10% equity in the second quarter of 2026, the lowest share among the 50 states and D.C., against 4.7% nationwide (Federal Housing Finance Agency). Equity is the part of a home’s value its owner doesn’t owe to a lender.
| Measure | Connecticut | U.S. | Rank |
|---|---|---|---|
| Mortgages 30 to 89 days late, Sept. 2025 Tied for 16th highest | 1.8% U.S. 1.6% | 1.6% | Tied for 16th highest |
| People with a credit score under 620, early 2025 Tied for 20th lowest | 11.4% U.S. 13.8% | 13.8% | Tied for 20th lowest |
| Card users near their credit limit, early 2025 Tied for 12th lowest | 22.9% U.S. 26.9% | 26.9% | Tied for 12th lowest |
Rank among the 50 states and D.C. Mortgages 30 to 89 days late, an early stage of falling behind: Consumer Financial Protection Bureau. Credit scores and card use: Federal Reserve Bank of Philadelphia, with a U.S. figure that is a population-weighted average of the states that we calculate.
Bankruptcy filings rose for a third straight year but stay low
Connecticut residents filed 3,671 bankruptcy cases in 2025, up 10.0% from 2024 and the most since 2020 (U.S. Courts). That is 99.9 filings for every 100,000 residents, using the 2024 population, the 16th lowest rate among the 50 states and D.C., against 167.1 nationwide. On the same measure Massachusetts (71.3) and Rhode Island (96.8) were lower and New York (116.7) higher. Most Connecticut cases are filed under Chapter 7, the kind that can erase many debts without a repayment plan: 83.7% of filings, the 4th highest share, against 62.4% across the 50 states and D.C. How bankruptcy works →
What changed in Connecticut in the past year
-
Sept. 17, 2026
Unemployment eases slightly after a year of increases
The Connecticut Department of Labor reported August’s unemployment rate at 5.1%, down from 5.2% in June and July. Payroll jobs fell by 300 because of government job cuts, while private employers reached a new high. The department says the past year’s rise came mostly from people newly looking for work, not from layoffs (see why the rate rose).
-
Sept. 11, 2026
Health insurance rates for 2027 are approved
The Connecticut Insurance Department approved average increases of 11.3% for 2027 individual health plans and 15.1% for small-group plans. Insurers had asked for 16.2% in the individual market. About 220,000 residents are covered by the plans the department regulates, and open enrollment for 2027 coverage starts Oct. 23, 2026.
-
Aug. 4, 2026
Grocery cards for people cut from SNAP
The state began handing out one-time prepaid grocery cards worth $300 a person to residents who have lost SNAP food benefits since Dec. 1, 2025 under the federal work rules for adults without dependents. The $8.5 million in state money goes out through community action agencies. In June the governor’s office estimated that about 25,000 residents would lose benefits under the rules (June 30 announcement).
-
July 14, 2026
Eversource asks for a large electric rate increase
Eversource asked the Connecticut Public Utilities Regulatory Authority for a $727 million yearly rate increase. If it were approved as filed, the average residential customer’s rates would rise 18%, according to the Connecticut Office of the Attorney General, which opposes the request. It is a request, not a decision.
-
Apr. 22, 2026
Lower electric rates and a credit on the bill
In April, state regulators approved lower residential electric rates from May 1, 2026 to April 30, 2027: about $30 a month off an average Eversource bill and $34 off an average United Illuminating bill, mostly through lower public benefits charges. The rates are interim and can be adjusted. The governor’s office says the public benefits part of the bill has shown as a credit since May 1, and in September the State Bond Commission approved more state bonds to keep paying down those costs through at least April 30, 2027 (Office of Governor Ned Lamont, Sept. 8, 2026).
Connecticut Public Utilities Regulatory Authority, Apr. 22, 2026
-
Feb. 19, 2026
Health plan sign-ups set a record even as extra federal help ended
Access Health CT, the state’s health insurance marketplace, enrolled 157,246 people in plans for 2026, up from 151,151 a year earlier, even though the extra federal help with premiums ended Dec. 31, 2025. Of those, 51,629 were in Covered CT, which gives eligible residents coverage at no cost.
How foreclosure works in Connecticut
Every home foreclosure in Connecticut goes through the Superior Court. Strict foreclosure, with no auction, is the default: the court sets “law days.” If the owner hasn’t paid off the whole debt by the owner’s law day, the title passes to the lender. A party can ask the court to order a sale instead, and the court decides (Conn. Gen. Stat. § 49-24). Before starting, a lender must mail a notice giving the homeowner 60 days to meet with it or a credit counseling agency and to contact the Connecticut Housing Finance Authority about emergency mortgage help (§ 8-265ee). Owners who live in the home can ask for the court’s Foreclosure Mediation Program by filing within 15 days of the return date on the court papers (§ 49-31l). Under federal rules, a mortgage company generally can’t start a foreclosure until the loan is more than 120 days behind.
- Goes through a court
- Always
- Default kind
- Strict foreclosure
- Auction
- Only if ordered
- Notice before the case
- 60 days
- Court mediation program
- Yes
- Time to ask for mediation
- 15 days
- Lender can seek the balance left
- Yes
What the law says. Sources: Conn. Gen. Stat. §§ 8-265ee, 49-14, 49-24 and 49-31l; federal rule 12 CFR 1024.41; Connecticut Judicial Branch, Foreclosure Mediation Program. How foreclosure works in Connecticut →
Connecticut received $123.1 million from the federal Homeowner Assistance Fund and had helped 4,513 homeowners through early 2026 (U.S. Treasury).
Connecticut’s most common mortgage complaint: trouble with payments
Connecticut residents have filed 5,900 mortgage complaints with the Consumer Financial Protection Bureau since 2012. Trouble during the payment process came up most often (1,608), then loan modification, collection and foreclosure (1,332), then loan servicing, payments or escrow (963).
- Oct. 7, 2026 Rocket Mortgage Trouble during payment process: Trying to communicate with the company to fix an issue while managing or servicing your loan Closed with explanation
- Oct. 2, 2026 CMG Financial Struggling to pay mortgage: An existing modification, forbearance plan, short sale, or other loss mitigation relief Closed with explanation
- Sept. 28, 2026 CMG Financial Struggling to pay mortgage: An existing modification, forbearance plan, short sale, or other loss mitigation relief Closed with explanation
- Sept. 28, 2026 Amerinational Community Services, Inc. Trouble during payment process: Escrow, taxes, or insurance In progress
- Sept. 26, 2026 LoanCare Struggling to pay mortgage: Applying for or obtaining a modification, forbearance plan, short sale, or deed-in-lieu Closed with explanation
- Sept. 25, 2026 Idaho Housing and Finance Association Trouble during payment process: Escrow, taxes, or insurance Closed with explanation
- Sept. 25, 2026 Carrington Mortgage Struggling to pay mortgage: Foreclosure In progress
- Sept. 24, 2026 LoanCare Trouble during payment process: Escrow, taxes, or insurance Closed with explanation
- Sept. 24, 2026 Freedom Mortgage Struggling to pay mortgage: An existing modification, forbearance plan, short sale, or other loss mitigation relief In progress
- Sept. 24, 2026 CMG Financial Trouble during payment process: Trying to communicate with the company to fix an issue while managing or servicing your loan Closed with explanation
The ten most recent Connecticut complaints about making mortgage payments or getting help with them, newest first, from the Consumer Financial Protection Bureau’s public complaint record as of Oct. 14, 2026. Complaints about getting or closing a loan, or about credit reports, are left out. The bureau doesn’t verify what people tell it. Every Connecticut mortgage complaint at the Consumer Financial Protection Bureau →
What to watch before the next edition
The Oct. 19 jobs report is the first test of whether unemployment keeps easing.
-
Oct. 19, 2026
Connecticut’s September jobs report
The Connecticut Department of Labor publishes September’s unemployment rate and payroll jobs, the first figures since August’s 5.1%.
-
Oct. 23, 2026
Open enrollment for 2027 health coverage begins
People who buy their own coverage can sign up for 2027 plans, with individual-plan rates approved at an average of 11.3% more than in 2026.
-
Nov. 20, 2026
Federal unemployment figures for October
The U.S. Bureau of Labor Statistics is scheduled to publish every state’s October 2026 unemployment rate, which will show where Connecticut’s rate stands among the states.
U.S. Bureau of Labor Statistics, release schedule, read Oct. 15, 2026
-
Jan. 1, 2027
The minimum wage is set to rise
Connecticut’s minimum wage is set to go from $16.94 to $17.48 an hour, under a 2019 state law that adjusts it at the start of each year.
Where Connecticut ranks highest and lowest
| Measure | Connecticut | U.S. | Rank | Latest data |
|---|---|---|---|---|
| Income per person 2nd highest · 2024 | $95,067 U.S. $73,204 | $73,204 | 2nd highest | 2024 |
| Unemployment rate, three-month average Tied for 2nd highest · June–August 2026 | 5.2% U.S. 4.1% | 4.1% | Tied for 2nd highest | June–August 2026 |
| Home price growth 2nd highest · 2025 | 6.1% U.S. 2.9% | 2.9% | 2nd highest | 2025 |
| Renters paying half or more of income for housing 7th highest · 2024 | 27.8% U.S. 26.1% | 26.1% | 7th highest | 2024 |
| Owners paying 30% or more of income for housing Tied for 7th highest · 2024* | 26.4% U.S. 22.5% | 22.5% | Tied for 7th highest | 2024* |
| Median household income 12th highest · 2024 | $95,670 U.S. $81,604 | $81,604 | 12th highest | 2024 |
| Debt per person with a credit report 16th highest · End of 2025 | $67,530 U.S. $63,200 | $63,200 | 16th highest | End of 2025 |
| Mortgages 30 to 89 days late Tied for 16th highest · Sept. 2025 | 1.8% U.S. 1.6% | 1.6% | Tied for 16th highest | Sept. 2025 |
| Median rent, a month 17th highest · 2024* | $1,488 U.S. $1,413 | $1,413 | 17th highest | 2024* |
| People with a debt 90+ days late 20th lowest · Early 2025 | 14.1% U.S. 17.2% | 17.2% | 20th lowest | Early 2025 |
| People with a debt in collections Tied for 19th lowest · Early 2025 | 10.4% U.S. 13.2% | 13.2% | Tied for 19th lowest | Early 2025 |
| Residents in poverty Tied for 13th lowest · 2024 | 10.1% U.S. 12.1% | 12.1% | Tied for 13th lowest | 2024 |
| Bankruptcy filings per 100,000 residents (2024 population) 16th lowest · 2025 | 99.9 U.S. 167.1 | 167.1 | 16th lowest | 2025 |
| Residents getting SNAP food benefits Tied for 16th lowest · June 2026 | 8.3% U.S. 10.7% | 10.7% | Tied for 16th lowest | June 2026 |
| Mortgages with less than 10% equity Lowest · Mid-2026 | 1.1% U.S. 4.7% | 4.7% | Lowest | Mid-2026 |
Rank among the 50 states and D.C.: “highest” counts down from the top, “lowest” up from the bottom. * Census five-year survey, 2020 to 2024. Home prices: Federal Housing Finance Agency, change over the year. Debts: Federal Reserve Bank of New York (debt per person) and Federal Reserve Bank of Philadelphia (people with a credit record; its U.S. figure is a population-weighted average of the states that we calculate). Every source is listed in Sources and method. Download this table: CSV.
Questions about Connecticut
Is Connecticut a rich state?
By income per person, yes: $95,067 in 2024, the 2nd highest among the 50 states and D.C. (U.S. Bureau of Economic Analysis). The typical household earned $95,670, 12th highest, and 10.1% of residents lived in poverty, below the U.S. rate of 12.1% (U.S. Census Bureau, Small Area Income and Poverty Estimates, 2024). On household financial distress it still ranks tied for 13th, mostly because of jobs and renters’ housing costs.
Does Connecticut still have counties?
Not as governments. Its eight counties stopped working as governments in 1960, and since late 2022 the Census Bureau has published Connecticut data for 9 planning regions instead (Census Bureau notice). On our County Distress Index the most distressed region is Naugatuck Valley, around Waterbury: see all 9 regions, ranked.
Why is unemployment so high in Connecticut?
It was 5.1% in August 2026, tied for 2nd highest among the 50 states and D.C. (U.S. Bureau of Labor Statistics). The Connecticut Department of Labor puts the past year’s rise down mostly to people newly looking for work rather than layoffs. Against that, the state’s labor force shrank in August, the department notes that survey response rates remain lower than before the pandemic, and private-sector payroll jobs hit a new high in August. We don’t know which explanation is right.
Is it cheaper to live in Florida or Connecticut?
On what we measure, it depends. Florida’s median rent was higher, $1,669 a month against Connecticut’s $1,488 (U.S. Census Bureau, 2020 to 2024), and more Florida renters paid half their income for housing in 2024, 32.1% against 27.8%. But MIT’s Living Wage Calculator puts basic costs for one adult higher in Connecticut, $54,178 a year against $50,117, and Connecticut’s typical household earns more, $95,670 against $77,687 (2024). We don’t measure food, insurance or energy prices.
What is a good salary in Connecticut?
We don’t set one. The closest figure we hold is MIT’s Living Wage Calculator, which estimates basic costs before taxes. It puts the yearly need at $54,178 for one adult with no children and $149,091 for two working parents with two children (2025 dollars). Those are the 9th highest and 5th highest among the 50 states and D.C. overall. Those are bare-bones budgets, not a comfortable income.
What is Connecticut’s poverty level?
Connecticut uses the federal poverty guideline, which for 2026 sets the line at $15,960 a year for a single person and $33,000 for a family of four. Only Alaska and Hawaii have their own, higher figures (U.S. Department of Health and Human Services).
Cite or reuse Connecticut’s data
Quote or reuse these figures, with credit, in reporting, grant applications or policy work.
State Distress Index
Connecticut
Tied for 13thmost distressed state
of the 50 states and D.C.
More distressed than 74% of the other states and D.C.
Connecticut ranks tied for 13th on the State Distress Index among the 50 states and D.C.. American Default Research measures household financial distress with this index. Yet Connecticut’s income per person was $95,067 in 2024, the 2nd highest (U.S. Bureau of Economic Analysis). Its unemployment rate was 5.1% in August 2026, tied for 2nd highest (U.S. Bureau of Labor Statistics). In 2024, 27.8% of its renter households paid half or more of their income for housing, the 7th highest share (U.S. Census Bureau).
For interviews or a custom cut of the data, reporters and researchers can write to press@americandefault.org
Sources and method
We gather the data, run the numbers and research each state ourselves.
This edition: October 2026 · Next edition expected March 2027
- Late payments, collections, credit scores and cards near their limitFederal Reserve Bank of Philadelphia, Consumer Credit Explorerend of 2019 and early 2025
- Household debt and dollars behindFederal Reserve Bank of New York, Consumer Credit Panel / Equifaxend of 2019 and end of 2025
- Mortgages with little equity; home pricesFederal Housing Finance Agency: National Mortgage Database; House Price Indexsecond quarter of 2026; 2025
- Mortgages 30 to 89 days late; mortgage complaints; medical debts on credit reportsConsumer Financial Protection Bureau: Mortgage Performance Trends; complaint database; Recent changes in medical collections on consumer credit recordsSept. 2025; Oct. 14, 2026; March 2022 to June 2023
- Bankruptcy filingsAdministrative Office of the U.S. Courts, Table F-22024 and 2025
- Unemployment, state, regional and nationalU.S. Bureau of Labor Statistics, Local Area Unemployment StatisticsJan. 1990 to Aug. 2026
- Payroll jobs, labor force and why unemployment roseConnecticut labor department, Aug. report and mid-year report; CT MirrorJune to Aug. 2026
- Poverty and incomeCensus Bureau, Small Area Income and Poverty Estimates1989 to 2024
- Renters paying half or more of income for housingCensus Bureau, American Community Survey 1-year2005 to 2024
- Rent, homeownership and owners’ housing costsCensus Bureau, American Community Survey 5-year2020 to 2024
- Planning regions in place of countiesCensus Bureau, Change to County-Equivalents in the State of Connecticut, 87 FR 34235June 6, 2022
- Income per person and its sourcesU.S. Bureau of Economic Analysis2024
- SNAPU.S. Department of Agriculture Food and Nutrition AdministrationSept. 2024 to June 2026
- Cost of basic needsMIT Living Wage Calculator2025 dollars
- Mortgage help fundU.S. Treasury, Homeowner Assistance Fundthrough early 2026
- Foreclosure lawConnecticut General Statutes, Chapter 846 and Chapter 134; Connecticut Judicial Branch, Foreclosure Mediation Program; 12 CFR 1024.41as of 2026
- Poverty guidelineU.S. Department of Health and Human Services2026
- Housing counselorsU.S. Department of Housing and Urban DevelopmentOctober 2026
- What changed and what to watchConnecticut labor department, Connecticut Insurance Department, Connecticut Public Utilities Regulatory Authority, Office of Governor Ned Lamont, Connecticut Office of the Attorney General, Access Health CT, U.S. Bureau of Labor Statistics release schedule; each item links to the page we read (what changed)Feb. 2026 to Jan. 2027
- Region photoCarol M. Highsmith, Library of Congress, via Wikimedia Commons2011
The score has four equal parts: late payments; collections and bankruptcy; jobs; and renters’ housing costs. Connecticut’s score is the share of the other states and D.C. whose average of the four parts is lower than its own. The full method →
We write with AI tools, and Ross Kilburn checks and reviews every page before it's published.
Get the next Connecticut edition by email
One email each time a new Connecticut edition is out; the next is expected in March 2027. Unsubscribe anytime.
Thanks, that helps.