Federal jobs based in D.C. fell by 26,900 through September 2026
Each state is shaded by how distressed its households are, from green (least) to red (most), with data through September 2026. District of Columbia scores 54 out of 100.
Federal jobs based in D.C. fell by 26,900 from January 2025 to September 2026. D.C.’s poverty rate ranks 3rd highest among the 50 states and D.C. Free help for residents behind on rent or a mortgage is listed below.
- Score
- 54/100
- Data through
- September 2026
- Edition
- October 2026
Next edition expected March 2027
How D.C. ranks among the states
The District scores 54 on the State Distress Index, 24th of 51 (the 50 states and D.C.). It has the country’s highest unemployment, but one of the lowest shares of residents with debt in collections. That contrast helps explain why its overall rank is 24th. We expect collections to rise if job losses last; that is our projection.
What drives the score
We rank D.C. on each part, average those ranks, then rank that average against every state. That is why the overall score of 54 is not the simple average of the four part scores below. Higher scores mean more strain.
- Renters’ housing costs3025.0% of renter households paid at least half their income toward housing in 2024
- Late payments8016.8% of auto borrowers and 15.9% of card borrowers were at least 90 days late in early 2025
- Jobs99Resident unemployment averaged 5.7% from July through September 2026
- Collections and bankruptcy117.6% had a debt in collections; the score’s bankruptcy input was 88.0 filings per 100,000 residents in 2025
How the older score moved
Peak in the series
The older quarterly score reached 86 from late 2017 into 2018
Latest historical quarter
It fell to 52 by early 2025 as renter costs and collections eased
Current edition
We rebuilt the score in 2026. Today’s 54 cannot be compared directly with the older series shown below.
D.C.’s older distress score fell to 52 by early 2025
State Distress Index score, quarterly historical series through early 2025. The current score uses newer data.
How the eight wards differ
D.C. has wards rather than counties. The Census Bureau shows large gaps in income, poverty, joblessness and rent burden across D.C.’s eight wards. The table shows each share with an approximate 90% margin of error.
Median household income ranges from $52,769 in Ward 8 to $144,877 in Ward 3, about 2.7 times as much. Ward 3’s estimate is close to Wards 1, 2 and 6; Ward 8 is clearly lowest.
| Ward | Median income (± margin) | Poverty (± margin) | Unemployment (± margin) | Rent ≥50% of income (±) |
|---|---|---|---|---|
| Ward 1 Unemployment (± margin) 4.4% ±1.3% · Rent ≥50% of income (±) 14.6% ±2.1% | $132,588 ±$7,079 Poverty (± margin) 13.0% ±2.1% | 13.0% ±2.1% | 4.4% ±1.3% | 14.6% ±2.1% |
| Ward 2 Unemployment (± margin) 3.4% ±0.6% · Rent ≥50% of income (±) 21.5% ±2.3% | $132,753 ±$6,757 Poverty (± margin) 11.0% ±1.2% | 11.0% ±1.2% | 3.4% ±0.6% | 21.5% ±2.3% |
| Ward 3 Unemployment (± margin) 3.8% ±0.8% · Rent ≥50% of income (±) 21.1% ±3.6% | $144,877 ±$7,347 Poverty (± margin) 7.7% ±1.1% | 7.7% ±1.1% | 3.8% ±0.8% | 21.1% ±3.6% |
| Ward 4 Unemployment (± margin) 6.3% ±1.7% · Rent ≥50% of income (±) 26.6% ±5.6% | $127,583 ±$7,976 Poverty (± margin) 10.9% ±1.7% | 10.9% ±1.7% | 6.3% ±1.7% | 26.6% ±5.6% |
| Ward 5 Unemployment (± margin) 6.9% ±1.1% · Rent ≥50% of income (±) 21.5% ±3.3% | $102,771 ±$3,893 Poverty (± margin) 14.9% ±1.9% | 14.9% ±1.9% | 6.9% ±1.1% | 21.5% ±3.3% |
| Ward 6 Unemployment (± margin) 3.5% ±0.6% · Rent ≥50% of income (±) 16.0% ±2.0% | $138,170 ±$6,459 Poverty (± margin) 10.5% ±1.2% | 10.5% ±1.2% | 3.5% ±0.6% | 16.0% ±2.0% |
| Ward 7 Unemployment (± margin) 12.7% ±2.1% · Rent ≥50% of income (±) 31.1% ±4.4% | $71,088 ±$2,837 Poverty (± margin) 22.9% ±2.6% | 22.9% ±2.6% | 12.7% ±2.1% | 31.1% ±4.4% |
| Ward 8 Unemployment (± margin) 13.3% ±2.3% · Rent ≥50% of income (±) 30.9% ±3.4% | $52,769 ±$4,643 Poverty (± margin) 30.6% ±3.3% | 30.6% ±3.3% | 13.3% ±2.3% | 30.9% ±3.4% |
Census Bureau, 2020–2024 American Community Survey five-year estimates, tables B19013, B17001, B23025 and B25070. Income is in 2024 dollars. Income margins are Census-published. Share margins are conservative approximations calculated from published 90% margins for numerator and denominator; they may overstate uncertainty.
East of the Anacostia
Wards 7 and 8 lie largely east of the Anacostia River. Their five-year median household income estimates are $71,088 and $52,769. In Ward 8, 30.6% of residents lived in poverty, and 30.9% of renters paid at least half their income for housing.
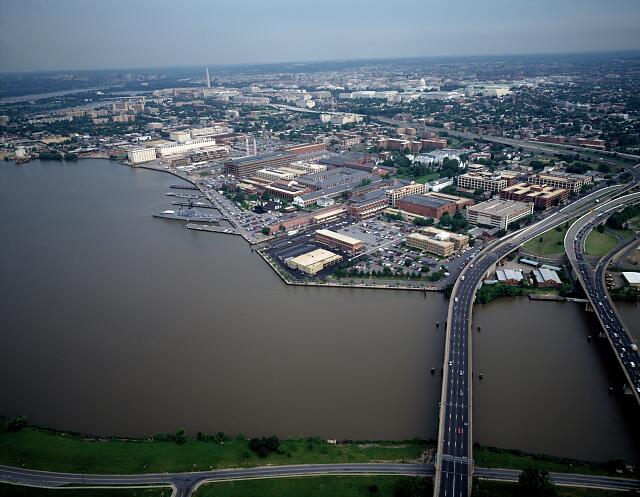
The Anacostia River. Wards 7 and 8 lie mostly east of it.
Photo: Carol M. Highsmith, public domain, via Library of Congress.
Ward 8’s unemployment estimate is 13.3%, compared with 3.8% in Ward 3.
What does it cost to live in D.C.?
D.C.’s typical monthly rent was $1,954, compared with $1,413 nationally. In 2024, 25.0% of D.C. renters spent at least half their income on housing, about the same share as nationally.
Median gross rent
$1,954
U.S. $1,413
2020–2024 ACS five-year estimate
Renters spending at least half their income on housing
25.0%
U.S. 26.1%
2024 ACS one-year estimate
Owner-occupied share
41.5%
U.S. 65.2%
2020–2024 ACS five-year estimate
D.C.’s median household income is $109,289, above the U.S. figure of $81,604. The ward table shows how far incomes vary within the city.
What are homes worth?
The U.S. Census Bureau estimates the median value of owner-occupied D.C. homes at $737,100 in 2020–2024. This is what owners reported their homes were worth, not the price of homes sold today.
What protections do D.C. renters have?
Most D.C. households rent. Renters have protections when rent rises, a building is sold or a landlord seeks eviction.
Rent increases and a building sale
D.C. requires at least 60 days’ written notice of a rent increase. In rent-stabilized homes, the standard annual caps are 4.1% for most tenants and 2.1% for registered elderly or disabled tenants from May 2026 through April 2027. The Office of the Tenant Advocate explains the exceptions.
When a landlord plans to sell, D.C.’s Tenant Opportunity to Purchase Act gives some renters a chance to buy. Most renters in single-family houses lost that purchase right in 2018, though elderly or disabled tenants can be exceptions. Since the December 2025 law change, many renters in buildings with two to four units also receive notice of sale without a purchase right. The Tenant Advocate’s bill of rights explains the rules.
An eviction notice and court case
A landlord cannot remove a tenant by changing the locks. An eviction requires a legal reason, a court order and U.S. Marshals supervision. For unpaid rent, D.C. Code § 42-3505.01 requires written notice at least 10 days before filing an eviction case. A landlord cannot file over less than $600 in unpaid rent.
After notice, a landlord can file in D.C. Superior Court’s Landlord and Tenant Branch. The renter receives court papers and a hearing date. A judge decides the case; only after a court order can U.S. Marshals carry out an eviction. Go to the court date: missing it can mean losing by default. Legal Aid DC and the Office of the Tenant Advocate explain court papers and legal help.
Jobs and the federal workforce
The federal government is a major employer in the District. The Bureau of Labor Statistics counted 26,900 fewer federal jobs based here in September 2026 than in January 2025. Many of the people who held those jobs live in Maryland or Virginia. The drop follows federal workforce cuts that began in 2025.
The resident unemployment rate was 5.6% in September 2026, above the U.S. 4.2%. D.C.’s three-month average, which feeds the current distress score, was 5.7%.
D.C. unemployment has run above the U.S. rate since 2020. The gap widened in 2025 and narrowed this year.
D.C. unemployment has run above the national rate
Resident unemployment rate, monthly; seasonally adjusted where published. The latest month is September 2026.
Jobs across all employers
Counting every employer, D.C. had 719,900 jobs in September 2026, down 45,600 from January 2025. Federal jobs account for only part of that decline.
If you lost a federal job
Former federal employees generally file for unemployment in the jurisdiction where their last federal job was based. The D.C. Department of Employment Services explains how to file. DISB’s federal-worker resource page links to housing counseling, mortgage and renter help.
Are people leaving D.C.?
The Census Bureau’s 2025 estimate shows D.C.’s population grew slightly from 2024 to 2025. The city’s chief financial officer found slightly more people moved out than moved in over that year. Births exceeded deaths, so the total population still grew. These figures do not isolate federal workers or show the effect of the later job losses.
Is D.C. poor?
D.C.’s median household income is the highest in the country, but 16.4% of residents lived in poverty in 2024. That poverty share ranked 3rd highest.
The chart shows poverty estimates for all eight wards. Ward 8 has the highest estimate.
A larger share of D.C. receives food aid than the U.S.
In July 2026, 131,264 D.C. residents received SNAP food benefits. That was about 18.9% of the population, compared with 10.5% nationally. Enrollment fell 6.9% from a year earlier.
How many D.C. residents are behind on their bills?
This section is about what households owe. In early 2025, 16.8% of D.C. auto borrowers were at least 90 days late, the highest share in the country.
The chart shows how late auto loans stand out, while the share of residents with debt in collections is low.
Ranks among the 50 states and D.C.: auto loans highest; cards 10th highest; mortgages tied for 12th highest; collections 2nd lowest. The U.S. figures come from the Philadelphia Fed’s national estimates.
Few D.C. mortgage borrowers were at least 90 days late (1.4%). Car loans are where more borrowers are falling behind. The Consumer Financial Protection Bureau explains payment options and repossession rights; mortgage help covers a different set of options.
Dollars behind tell a second story
By dollars owed, 13.6% of D.C. auto-loan balances were at least 90 days late at the end of 2025, up from 9.8% in 2019. The table compares D.C. with the U.S. across three kinds of debt.
| Loan balance 90+ days late | D.C. | U.S. | D.C. 2019 | U.S. 2019 |
|---|---|---|---|---|
| Credit card D.C. 2019 6.5% · U.S. 2019 8.1% | 11.2% U.S. 12.4% | 12.4% | 6.5% | 8.1% |
| Auto loan D.C. 2019 9.8% · U.S. 2019 4.9% | 13.6% U.S. 5.2% | 5.2% | 9.8% | 4.9% |
| Mortgage D.C. 2019 0.8% · U.S. 2019 1.0% | 1.0% U.S. 0.9% | 0.9% | 0.8% | 1.0% |
Federal Reserve Bank of New York, Consumer Credit Panel / Equifax, end of 2025 and end of 2019. These are shares of dollars owed.
How common is bankruptcy in D.C.?
Using U.S. Courts filings and the Census 2025 population estimate, we calculate 89.1 filings per 100,000 D.C. residents in 2025, about half the national rate of 166.3. The score uses a different population denominator and a rate of 88.0. The rate shown here ranked 40th highest among the 50 states and D.C.
The bankruptcy statistics page shows the national history. Legal Aid DC provides information about legal help in the District.
Foreclosure, tax sales and help in D.C.
In D.C., a lender can foreclose through court or without court if it follows the notice and mediation rules. The second route is called a power of sale. Overdue property taxes and condo assessments follow different rules.
Foreclosure without court
The lender sends a notice of default by certified and first-class mail. A homeowner has 30 days after that mailing to choose mediation by returning DISB’s election form with a $50 fee. The mediation administrator can waive the requirements for good cause. The lender must obtain a mediation certificate before moving toward a sale outside court.
Catching up on missed mortgage payments can stop a sale if done at least five business days before bidding. D.C. law limits that right to once every two years. A court foreclosure follows a different process.
The broad order is: default notice and mediation form; a 30-day window to return the form; mediation or a certificate allowing the lender to proceed; then notice of a sale. D.C. sets deadlines for some steps, not one fixed total length. The D.C. law guide and foreclosure timeline explain the steps.
- Power of sale and notice
- D.C. Code § 42-815
- Mediation election and certificate
- D.C. Code § 42-815.02
- Mortgage cure
- D.C. Code § 42-815.01
- Court route
- D.C. Code § 42-815.04
The D.C. law and help guide gives the source text and limits.
Property-tax sale and condo liens
If property taxes go unpaid, D.C. can sell a lien on the home. After six months, the buyer of that lien can ask a court to end the owner’s right to pay the debt and keep the home. The owner can still pay what is owed before the court’s final judgment, under the D.C. Code’s conditions. This is separate from mortgage foreclosure.
Unpaid condo fees, including a special assessment, can become a lien on the unit. Under D.C. Code § 42-1903.13, part of that debt can take priority over a first mortgage. An association can seek a sale even when the mortgage is current.
Property-tax relief
The Homestead Deduction lowers the taxable value of an eligible owner-occupied home. Qualified older or disabled owners can receive a 50% property-tax reduction. Schedule H is a separate income-based credit for eligible renters and homeowners.
D.C. calls its annual tax sale a Tax Lien Sale. The 2026 sale has run; the Office of Tax and Revenue posts sold notices and redemption resources. Owners with a tax-sale question can reach the Real Property Tax Ombudsman at 202-727-1529.
Sources: D.C. Code tax lien, redemption, court petition, and condo lien.
Where to find help now
DISB’s Foreclosure Prevention Program offers free counseling through the D.C. Foreclosure Prevention Hotline, 202-265-2255 (Monday–Friday, 9 a.m.–5 p.m.). DISB’s government program line is 202-442-7765 (Monday–Friday, 8:15 a.m.–4:45 p.m.). The D.C. Department of Housing and Community Development covers foreclosure, buying and renting at 202-442-7200. The U.S. Department of Housing and Urban Development’s counselor line is 800-569-4287.
Renters can contact the Office of the Tenant Advocate at 202-719-6560 and Legal Aid DC at 202-628-1161 while waiting for rental aid to reopen. The Office of Tax and Revenue lists homestead and senior or disabled homeowner tax relief at 202-727-4829.
Programs closed or for buyers
The Homeowner Assistance Fund has ended. The D.C. Housing Finance Agency’s reverse-mortgage tax and insurance program is not accepting applications. The Home Purchase Assistance Program helps qualified buyers with purchase and closing costs; it is not delinquent-mortgage aid.
Emergency Rental Assistance plans to open appointment scheduling Dec. 3, 2026, at noon, until available FY27 funds are committed.
Help with utility bills and shutoffs
The D.C. Department of Energy and Environment opened FY27 applications for energy assistance and utility discounts on Oct. 20. DC Water lists discounts and payment plans. The D.C. Public Service Commission’s bill of rights bars electric shutoffs for nonpayment when the forecast reaches 95°F or falls to 32°F or below; gas has a cold-weather protection. A medically necessary delay may be available with the required certification and payment agreement.
What mortgage complaints show
D.C. consumers have filed 2,379 mortgage complaints with the Consumer Financial Protection Bureau since 2012. The records below are the latest complaints about paying a mortgage or getting help with one. A complaint is one person’s account; the bureau does not verify it.
- Oct. 6, 2026 Ocwen / Onity Group Payment process: escrow, taxes or insurance In progress
- Oct. 5, 2026 M&T Bank Struggling to pay: applying for a modification, forbearance, short sale or deed-in-lieu In progress
- Sept. 30, 2026 LoanCare Struggling to pay: trouble reaching the company about a modification, forbearance or foreclosure In progress
- Sept. 29, 2026 Rocket Mortgage Struggling to pay: an existing modification, forbearance or other relief Closed with explanation
- Sept. 25, 2026 Rocket Mortgage Payment process: releasing the lien Closed with explanation
- Sept. 21, 2026 MidFirst Bank Struggling to pay: an existing modification, forbearance or other relief Closed with explanation
- Sept. 18, 2026 First National Bank of Pennsylvania Payment process: private mortgage insurance Closed with explanation
- Sept. 17, 2026 CrossCountry Mortgage Payment process: trouble reaching the company to fix a problem with the loan In progress
- Sept. 14, 2026 Shellpoint / NewRez Payment process Untimely response
- Sept. 14, 2026 Bank of America Payment process: trouble reaching the company to fix a problem with the loan Closed with explanation
Latest ten public D.C. mortgage-servicing complaints reported by the Consumer Financial Protection Bureau. Search every D.C. mortgage complaint.
What changed in D.C.
Federal employment and citywide jobs fell. Rent rules and wages also changed household budgets this year.
-
September 2026
Federal jobs and total jobs remain below January 2025
BLS counted 165,300 federal jobs and 719,900 total jobs located in D.C. That is 26,900 fewer federal jobs and 45,600 fewer jobs overall than in January 2025.
-
September 2026
Tenant rights notice revised
The Office of the Tenant Advocate published a revised Tenant Bill of Rights on Sept. 25. Housing providers must give the revised notice to prospective renters when they apply and to current renters who request it once a year, starting 90 days after publication.
-
July 2026
Minimum wage rose
D.C.’s minimum hourly wage for all workers rose to $18.40 on July 1. Tipped workers’ base rate rose to $10.30.
-
May 2026
New rent caps took effect
For rent-stabilized housing, the annual increase cap became 4.1% for most tenants and 2.1% for elderly or disabled tenants. The caps cover May 2026 through April 2027.
What to watch before the next edition
Two dates to watch for D.C. jobs and rental help.
-
Nov. 20, 2026
D.C. employment update
The Bureau of Labor Statistics plans to release October state employment and unemployment figures. It will update federal jobs located in D.C. and unemployment among D.C. residents.
-
Dec. 3, 2026
Rental assistance appointments reopen at noon
D.C. plans to reopen Emergency Rental Assistance appointment scheduling at noon, until available FY27 funds are committed.
Where D.C. ranks highest and lowest
D.C. ranks against the 50 states and D.C. in every row. Each row shows its own date and unit.
| Measure | D.C. | U.S. | Rank | Latest data |
|---|---|---|---|---|
| State Distress Index 24th highest · Sept. 2026 | 54 | 24th highest | Sept. 2026 | |
| Resident unemployment, three-month average Highest · July–September 2026 | 5.7% U.S. 4.1% | 4.1% | Highest | July–September 2026 |
| Residents in poverty 3rd highest · 2024 | 16.4% U.S. 12.1% | 12.1% | 3rd highest | 2024 |
| Median household income Highest · 2024 | $109,289 U.S. $81,604 | $81,604 | Highest | 2024 |
| Median gross rent 3rd highest · 2020–24 | $1,954 U.S. $1,413 | $1,413 | 3rd highest | 2020–24 |
| Renter households paying half or more for housing 22nd highest · 2024 | 25.0% U.S. 26.1% | 26.1% | 22nd highest | 2024 |
| Owner-occupied homes Lowest · 2020–24 | 41.5% U.S. 65.2% | 65.2% | Lowest | 2020–24 |
| Auto borrowers 90+ days late Highest · Early 2025 | 16.8% U.S. 8.5% | 8.5% | Highest | Early 2025 |
| Card borrowers 90+ days late 10th highest · Early 2025 | 15.9% U.S. 13.5% | 13.5% | 10th highest | Early 2025 |
| People with debt in collections 2nd lowest · Early 2025 | 7.6% U.S. 13.2% | 13.2% | 2nd lowest | Early 2025 |
| SNAP enrollment, share of residents 2nd highest · July 2026 | 18.9% U.S. 10.5% | 10.5% | 2nd highest | July 2026 |
| Renters paying at least 30% of income Tied for 31st highest · 2020–24 | 44.3% U.S. 47.6% | 47.6% | Tied for 31st highest | 2020–24 |
| Mortgages with under 10% equity Tied for 40th highest · Q2 2026 | 2.6% U.S. 4.7% | 4.7% | Tied for 40th highest | Q2 2026 |
| Bankruptcy filings per 100,000 residents 40th highest · 2025 | 89.1 U.S. 166.3 | 166.3 | 40th highest | 2025 |
Ranks are among 51 jurisdictions, the 50 states and D.C. ACS housing estimates are five-year estimates except the severe renter-burden share, which is a one-year estimate. Download the edition CSV.
Questions about District of Columbia
Does D.C. have counties?
No. D.C. uses wards for local representation. The Census Bureau publishes estimates for all eight wards with margins of error. The State Distress Index remains a citywide score; it does not rank wards.
Which D.C. ward has the lowest median household income?
Ward 8, at $52,769 in the 2020–2024 Census estimate, with a 90% margin of error of ±$4,643. Ward 7 is $71,088. Ward 8’s estimate is clearly below the other wards.
Is D.C. expensive for renters?
Median gross rent was $1,954 in the 2020–2024 Census estimate. A separate 2024 estimate found 25.0% of renter households spent at least half their income on housing. The ward table shows how burden differs across the District.
Is mortgage mediation required in D.C.?
A lender needs a mediation certificate before a residential mortgage power-of-sale foreclosure. A homeowner has 30 days after the default notice is mailed to choose mediation by returning the election form and a $50 fee. The mediation administrator can waive these requirements for good cause. D.C. Code § 42-815.02 sets out the process.
Where can a D.C. renter get help?
The Office of the Tenant Advocate provides tenant information and services at 202-719-6560. Emergency Rental Assistance plans to reopen appointment scheduling Dec. 3, 2026, at noon, while funds last. Legal Aid DC offers housing intake at 202-628-1161.
Cite or reuse District of Columbia’s data
For reporting, public research and community work.
State Distress Index
District of Columbia
24thmost distressed
of 51 (the 50 states and D.C.)
D.C. ranks 24th of 51 (the 50 states and D.C.).
The District of Columbia scores 54, 24th of 51 (the 50 states and D.C.), on American Default Research’s State Distress Index. D.C. has the highest unemployment in the country. BLS recorded 26,900 fewer federal jobs located in the District in September 2026 than in January 2025. Census ward estimates show median household income of $144,877 in Ward 3 and $52,769 in Ward 8, each with a published margin of error.
Questions, interviews or a custom cut of the data: press@americandefault.org
Sources and method
We gather the data, run the numbers and research each state ourselves.
This edition: October 2026 · Next edition expected March 2027
- State Distress Index and historyAmerican Default Research methodologyOctober 2026 edition; history through early 2025
- Resident unemployment and federal jobs by workplaceBureau of Labor StatisticsSeptember 2026
- SNAP enrollment in D.C.U.S. Department of Agriculture, SNAP participation tablesJuly 2026
- Ward income, rent cost, tenure, poverty and labor force with margins of errorCensus Bureau, ACS five-year table-based summary files2020–2024
- Citywide poverty and incomeCensus Bureau, Small Area Income and Poverty Estimates2024
- Citywide rent and housing costsCensus Bureau, American Community Survey2024 one-year and 2020–2024 five-year
- Owner-reported home valuesCensus Bureau, QuickFacts2020–2024
- Population and movementCensus Bureau, QuickFacts and D.C. Chief Financial Officer2024–2025
- Late payments and collectionsFederal Reserve Bank of Philadelphia, Consumer Credit Explorerearly 2025
- Debt balancesFederal Reserve Bank of New York, Consumer Credit Panelend of 2025
- Bankruptcy filingsAdministrative Office of the U.S. Courts, Table F-22025
- Mortgage, tax-sale and condo-lien lawD.C. Codechecked October 2026
- Utility assistance and shutoff protectionsD.C. Department of Energy and Environment and Public Service Commissionchecked October 2026
- Help programs and contactsProvider and agency pages linked above; U.S. Department of Housing and Urban Development counselor searchchecked October 2026
The score gives equal weight to late payments, collections and bankruptcy, jobs, and renter housing costs. The parts are compared across the 50 states and D.C.; the final score ranks their combined average. Full method →.
We write with AI tools, and Ross Kilburn checks and reviews every page before it's published.
Get the next District of Columbia edition by email
One email each time a new District of Columbia edition is out; the next is expected in March 2027. Unsubscribe anytime.
Thanks, that helps.