The count of Arizonans getting SNAP fell 52.5% in a year, the largest drop of any state
Each state is shaded by how distressed its households are, from green (least) to red (most), with data through September 2026. Arizona scores 88 out of 100.
Arizona's SNAP drop was twice the next largest of any state, Nevada's. SNAP now reaches 5.6% of Arizonans, about half the share who lived in poverty in 2024. Unemployment was 4.9% in August 2026, tied for 6th highest nationally. Apache County, in the northeast corner, where 71.6% of residents are American Indian or Alaska Native, is more distressed than 90% of U.S. counties.
- Score
- 88/100
- Data through
- September 2026
- Edition
- October 2026
Next edition expected March 2027
How Arizona ranks among the states
Among the 50 states and D.C., Arizona is the 7th most distressed, though on income and poverty it sits near the middle (is Arizona poor?). Jobs are what set it apart. In August 2026, 4.9% of Arizona’s labor force was out of work, tied for 6th highest among the states, against 4.1% nationwide. But jobs aren’t what lifted Arizona’s score over the last few years. Its jobs part was already high in 2019; the climb since then came from renters’ housing costs and from collections and bankruptcy, as the cards below explain.
What drives the score
Each of the four parts below averages one or more measures, and each measure is scored from 0 to 100 by how Arizona compares with the other states. Arizona’s four parts average 71, higher than the four-part average of 44 of the other 49 states and D.C. That’s 88% of them, so Arizona’s score is 88. The score is that share, not the average of the parts.
- Jobs88The jobless rate averaged 4.9% over June, July and August 2026; the U.S. rate averaged 4.1%.
- Renters’ housing costs68In 2024, 25.1% of Arizona renter households paid half or more of their income for housing, tied for 20th highest among the states, though just under the U.S. share of 26.1%.
- Late payments67Card and car-loan borrowers were 90 or more days behind a little more often than nationwide in early 2025; mortgage borrowers a little less often.
- Collections and bankruptcy62In early 2025, 14.3% of Arizonans with a credit record had a debt in collections (U.S. 13.2%). Bankruptcy filings ran 170.0 per 100,000 residents in 2025, using the 2024 population.
Beside its neighbors
Nevada is the only one of Arizona’s neighbors that scores higher. California and New Mexico score lower, and Utah, to the north, scores far lower.
- Nevada 98
- California 78
- New Mexico 66
- Arizona 88
- Utah 24
State Distress Index score, 0 to 100. The five states fall in the same order on renters’ housing costs. In 2024, 29.4% of Nevada’s renter households paid half or more of their income for housing, against 29.0% in California, 25.7% in New Mexico, 25.1% in Arizona and 21.3% in Utah (Census Bureau). Jobs don’t follow that order: Arizona’s August 2026 unemployment rate was higher than Nevada’s and New Mexico’s (Bureau of Labor Statistics).
Since 2019, renters’ costs and collections have lifted Arizona’s score
At its worst
In the second quarter of 2010, Arizona was the 7th most distressed state, with a score of 88. Late payments, at 92, and jobs, at 81, were its two highest parts then. Its least distressed quarter in our full history, which starts in mid-2006, came in the third quarter of 2007: 30, 36th among the states.
The drop and climb since 2019
By the end of 2019, Arizona had fallen to 50, 26th among the states. A single Census estimate did most of that: it showed a smaller share of renters paying half their income for housing. The renters’ part fell from 56 to 26 in a single quarter. It slipped further by mid-2020, to 40, 31st. Jobs were already a strain then, with a jobs part of 87; unemployment averaged 4.8% in 2019, against 3.7% nationally. Renters’ housing costs helped drive the rise back: that part went from 26 at the end of 2019 to 68 today. The collections and bankruptcy part rose from 52 to 62 against the other states, though Arizona’s own collections share fell (see behind on bills).
Since the chart ends
The chart stops in the first quarter of 2025, with Arizona at 78, 12th. Today Arizona scores 88 and ranks 7th. Jobs did most of that: the part rose from 68 to 88 as unemployment climbed, while renters’ costs fell from 77 to 68 with the Census Bureau’s 2025 estimate.
Arizona went from 36th most distressed in 2007 to 7th in 2010, fell as low as 31st in 2020 and was back to 12th by early 2025
State Distress Index score from 0 to 100, by quarter, third quarter of 2006 through first quarter of 2025.
Arizona’s poorest counties, and its most distressed
Apache County, in the state’s northeast corner, is both Arizona’s poorest county and its most distressed. In 2024, 29.3% of its residents lived in poverty, the highest rate of Arizona’s 15 counties (Census Bureau, Small Area Income and Poverty Estimates). It also scores 90 on our County Distress Index, which measures how strained household finances are in every U.S. county. Navajo County, to its west, and Santa Cruz County, on the Mexico border, come next. Most of Apache County’s residents, 71.6%, are American Indian or Alaska Native, as are 42.2% of Navajo County’s, against 4.0% statewide (Census Bureau, 2020 to 2024). Greenlee County, on the New Mexico line, is the least distressed in the state. No Arizona county is among the 100 most distressed of the 3,144 counties we score (the national list).
Arizona’s four most distressed counties, in the northeast, the northwest and on the Mexico border, are home to just 6.7% of its people
Scores from 0 to 100 on our County Distress Index for each of Arizona’s 15 counties, with data through August 2026.
Loading the county map…
The county map could not be loaded. Every county is in the lists on this page.
Most distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 1 | Apache | 90 | 29.3% |
| 2 | Navajo | 89 | 22.7% |
| 3 | Santa Cruz | 88 | 17.4% |
| 4 | Mohave | 83 | 14.6% |
| 5 | Gila | 80 | 19.1% |
| 6 | La Paz | 76 | 18.7% |
| 7 | Yuma | 71 | 16.6% |
| 8 | Cochise | 71 | 14.5% |
| 9 | Pinal | 70 | 11.0% |
| 10 | Pima | 69 | 13.8% |
Least distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 11 | Coconino | 66 | 15.2% |
| 12 | Graham | 60 | 19.3% |
| 13 | Maricopa | 56 | 10.4% |
| 14 | Yavapai | 51 | 9.8% |
| 15 | Greenlee | 28 | 9.8% |
Rank in Arizona, 1 = most distressed. Ranks come from unrounded scores. Poverty: share of residents below the poverty line in 2024 (Census Bureau).
Every county, by score
Four of Arizona’s 15 counties score 80 or more. Most Arizonans live in three counties that score lower: Maricopa (Phoenix), Pinal and Pima (Tucson) hold 82.5% of residents and score from 56 to 70. No county scores between 30 and 50.
5 score 80–100
Apache, Navajo, Santa Cruz, Mohave, Gila
1 score 0–29
The third-poorest county ranks 12th on distress
The County Distress Index weighs five parts equally: late payments; collections and bankruptcy; jobs (unemployment and adults 25 to 54 not working); renters’ housing costs; and a fifth that weighs poverty, child poverty, household income, disability and health insurance. Apache and Navajo top both lists, but the order splits after that. Graham County, around Safford, has the 3rd highest poverty rate in the state, 19.3%, yet ranks 12th on distress, and it scores lower on renters’ housing costs than any of the 11 counties ranked above it. Pinal County runs the other way: its poverty rate is 4th lowest in the state, yet it ranks 9th on distress and has the highest collections-and-bankruptcy score of any Arizona county. Other sites may name a different poorest county if they use another Census survey or year; ours come from the Census Bureau’s 2024 county estimates.
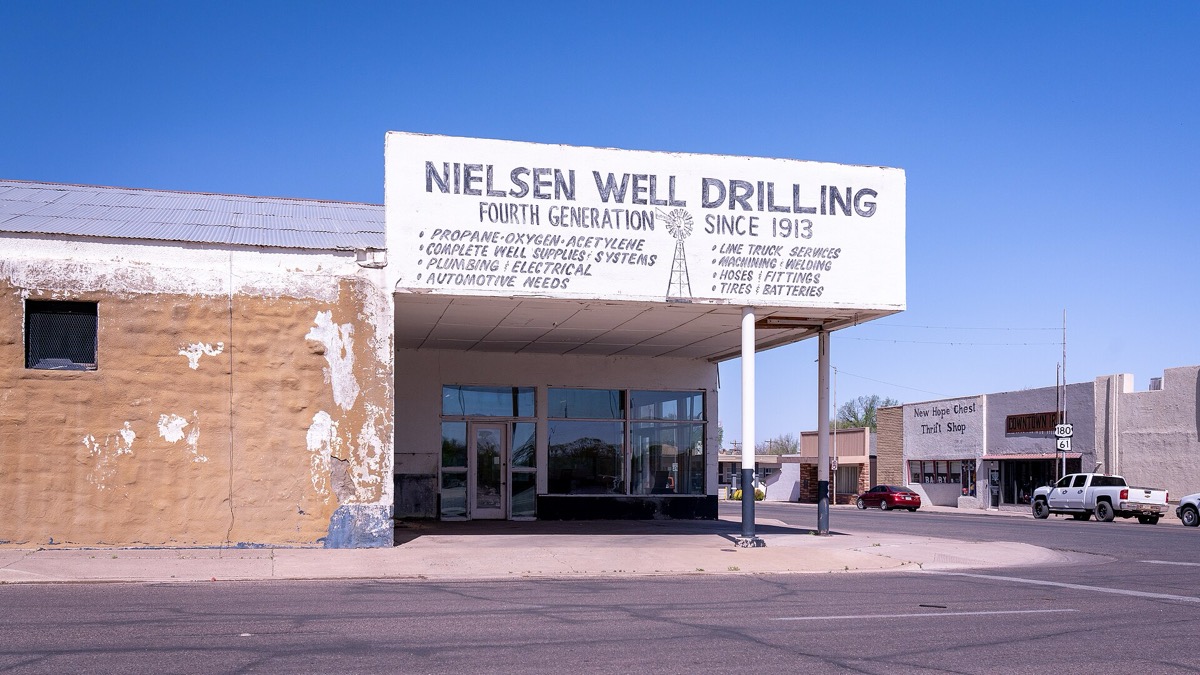
Downtown St. Johns, the seat of Apache County, in May 2022. Apache County’s typical household earned $43,939 in 2024, the lowest of Arizona’s 15 counties (Census Bureau).
Source: U.S. Census Bureau. Photo: Mobilus In Mobili, Wikimedia Commons, CC BY-SA 2.0.

In the northeast, jobs and late payments weigh most
Apache and Navajo counties score higher on late payments than any other Arizona county, and higher on jobs, a part that counts both the year’s average unemployment rate and the share of adults 25 to 54 who aren’t working. In August 2026, 8.8% of Apache County’s labor force and 7.7% of Navajo County’s were out of work, not adjusting for seasonal swings (Bureau of Labor Statistics).
American Default Research, County Distress Index; U.S. Bureau of Labor Statistics.
Arizona’s cost of living: rent runs above the U.S. median
Rent runs higher here than in most states, and incomes don’t make up for it. The median rent was $1,543 a month from 2020 to 2024, the 13th highest of the 50 states and D.C. and above the U.S. median of $1,413. Meanwhile, Arizona’s typical household income is about the same as the nation’s (U.S. Census Bureau). So rent takes a larger share of a typical income: 22.7% in Arizona, against 20.8% nationwide (our calculation). We don’t track grocery, gas or electricity prices, so we can’t rank Arizona’s overall cost of living.
Median rent, a month
$1,543
U.S. $1,413
13th highest of all states and D.C., 2020 to 2024
Renters spending at least 30% of income on housing
48.0%
U.S. 47.6%
14th highest of all states and D.C., 2020 to 2024
Renters spending at least half their income on housing
25.1%
U.S. 26.1%
Tied for 20th highest of all states and D.C., 2024
The share of Arizona renters paying half their income for housing rose from 21.9% in 2019 to 26.7% in 2023, the highest share in any year the Census Bureau published since 2005, then eased
Renter households whose rent and utilities take half or more of their income, Arizona and the U.S., each year from 2005 to 2024. The Census Bureau put out no one-year estimates for 2020.
A bare-bones budget in Arizona
The MIT Living Wage Calculator puts what one adult with no children needs for basic costs in Arizona at $50,900 a year before taxes, the 19th highest of the 50 states and D.C. overall. A family of four with two working parents needs $118,451. These budgets cover necessities only.
Electric bills aren’t in our data. Customers of Arizona Public Service (APS) are set to get a one-time credit on November bills, and APS’s request for higher base rates awaits a vote (see what changed).
Is it cheaper to live in Arizona or California?
For rent, yes: California’s median was $2,036 a month, against $1,543 in Arizona. California’s typical household earns more, too, so the gap in rent’s share of income is small. We don’t measure other prices.
| State | Rent, a month | Typical household income | Rent as share of income |
|---|---|---|---|
| Arizona Rent as share of income 22.7% | $1,543 Typical household income $81,404 | $81,404 | 22.7% |
| California Rent as share of income 24.4% | $2,036 Typical household income $100,130 | $100,130 | 24.4% |
| Nevada Rent as share of income 23.6% | $1,597 Typical household income $81,129 | $81,129 | 23.6% |
| Utah Rent as share of income 18.6% | $1,496 Typical household income $96,398 | $96,398 | 18.6% |
| New Mexico Rent as share of income 18.9% | $1,067 Typical household income $67,838 | $67,838 | 18.9% |
Rent: median gross rent a month, 2020 to 2024 (Census Bureau, American Community Survey). Income: median household income, 2024 (Census Bureau, Small Area Income and Poverty Estimates). Rent as share of income: twelve months of median rent divided by median household income, our calculation. Rent and housing costs across the U.S. →
Arizona’s unemployment rate is among the highest in the U.S.
Arizona’s unemployment rate was 4.9% in August 2026, tied for 6th highest among the 50 states and D.C. and above the U.S. rate of 4.1% (U.S. Bureau of Labor Statistics). That was up from 4.4% a year earlier. The state’s rate matched the nation’s in December 2025, then climbed, reaching its August level by June 2026 and holding there, while the U.S. rate eased.
Unemployment rate
4.9%
U.S. 4.1%
Tied for 6th highest of all states and D.C., August 2026
Jobs added over the year
22,700
September 2025 to September 2026, Arizona Office of Economic Opportunity
Fall in the labor force over the year
121,241
September 2025 to September 2026, Arizona Office of Economic Opportunity
Arizona’s unemployment rate topped the nation’s every month from July 2008 to March 2020, and has again every month since January 2026
Share of the labor force out of work, seasonally adjusted, Arizona and the U.S., each month from January 1990 to August 2026. October 2025 has no figure: none was published during the federal shutdown.
More jobs than a year ago, yet a smaller labor force
In September 2026, Arizona had 22,700 more jobs than a year before, according to the Arizona Office of Economic Opportunity, the state’s labor-market research office. Over the same year its labor force, the people working or looking for work, shrank by 121,241, or 3.2%. The office’s report doesn’t say why.
Over whole years, Arizona’s unemployment rate was above the nation’s in every year from 2009 to 2019, and the two matched in 2025 at 4.3% (Bureau of Labor Statistics yearly averages).
A fast-growing state
Arizona had 7,623,818 residents in 2025, 6.1% more than in 2020, the 8th highest growth of the 50 states and D.C. (U.S. Census Bureau).
Unemployment is highest in Yuma County
| County | Rate |
|---|---|
| Yuma | 19.0% |
| Santa Cruz | 9.0% |
| Apache | 8.8% |
| Navajo | 7.7% |
| La Paz | 7.1% |
| Pima (Tucson) | 5.7% |
| Maricopa (Phoenix) | 4.8% |
| Greenlee | 3.6% |
Unemployment rate, August 2026, not adjusted for seasonal swings: the five highest of Arizona’s 15 counties, its two largest and the lowest. Yuma County’s August rate was the 2nd highest of the 3,143 U.S. counties with a rate; over the 11 months published from September 2025 to August 2026, it averaged 14.7%. Source: U.S. Bureau of Labor Statistics.
Unemployment benefits are claimed through the Arizona Department of Economic Security. The state minimum wage is enforced by the Industrial Commission of Arizona.
Is Arizona a poor state?
No. It sits near the middle of the states. In 2024, 11.9% of Arizonans lived below the poverty line, just under the U.S. rate of 12.1% and 22nd highest among the 50 states and D.C. overall. The typical household earned $81,404, the 21st highest, almost exactly the U.S. median of $81,604 (U.S. Census Bureau, Small Area Income and Poverty Estimates). Income per person, all the income residents receive divided by the number of residents, ranks lower: $65,798, the 18th lowest, against $73,204 for the U.S. (U.S. Bureau of Economic Analysis).
Residents in poverty
11.9%
U.S. 12.1%
22nd highest of all states and D.C., 2024
Median household income
$81,404
U.S. $81,604
21st highest of all states and D.C., 2024
Children in poverty
15.2%
U.S. 15.5%
24th highest of all states and D.C., 2024
Arizona’s poverty rate topped the nation’s in every Census estimate from 1989 to 2021; it came in lower in 2022 and again in 2024
Percent of people living below the poverty line in Arizona and in the U.S., from 1989 to 2024. The Census Bureau made no state estimates for 1990 to 1992 or 1994.
More older residents, more income from benefits
From 2020 to 2024, 18.9% of Arizonans were 65 or older, tied for 12th highest among the 50 states and D.C., against 17.2% nationwide (U.S. Census Bureau). In 2024, government benefits such as Social Security and Medicare made up 20.4% of all income in Arizona, tied for 20th highest, against 18.3% for the U.S. (U.S. Bureau of Economic Analysis).
About half as many Arizonans get SNAP food benefits as a year earlier (see SNAP).
Health coverage, schooling and disability, 2020 to 2024
| Measure | Arizona | U.S. | Rank |
|---|---|---|---|
| Residents without health insurance 9th highest | 10.5% U.S. 8.4% | 8.4% | 9th highest |
| Adults without a high school diploma Tied for 13th highest | 10.6% U.S. 10.4% | 10.4% | Tied for 13th highest |
| Residents with a disability Tied for 24th highest | 13.8% U.S. 13.3% | 13.3% | Tied for 24th highest |
Rank among the 50 states and D.C., 1 = the highest share. Source: Census Bureau, American Community Survey five-year estimates. Arizona’s poorest counties →
SNAP in Arizona: half as many people get food help as a year ago
In June 2026, 421,147 Arizonans got SNAP food benefits, once called food stamps, 52.5% fewer than the 886,806 in June 2025. No other state came close: Arizona’s drop was the largest of the 50 states and D.C., twice the next largest, Nevada’s 24.3% (U.S. Department of Agriculture). SNAP now reaches 5.6% of Arizonans (2024 population), the 5th lowest share, against 10.7% nationwide.
People getting SNAP
421,147
June 2026, U.S. Department of Agriculture
Share of residents getting SNAP
5.6%
U.S. 10.7%
5th lowest of all states and D.C., June 2026 (2024 population)
Drop from a year earlier
52.5%
Largest of the 50 states and D.C., June 2025 to June 2026
The count was 875,273 in August 2025, little changed from June. It began falling in September, dropped every month to 400,641 in April 2026, then edged up in May and June (U.S. Department of Agriculture).
Why the count fell: the explanations differ
A spokesperson for the Arizona Department of Economic Security said SNAP caseloads fell after the state applied federal changes from summer 2025. Those changes included work requirements and the end of an exemption from the work rule for people in Maricopa County. The department blames a backlog of cases on a new program to cut payment errors (Arizona’s Family, May 26, 2026). ProPublica reported that its interviews suggest the state’s efforts to comply, along with cuts at the department, contributed to the drop by making it harder to apply and leading to eligible people being denied (ProPublica, April 8, 2026). The monthly counts don’t show how much of the drop each explains.
Fewer people getting SNAP isn’t the same as fewer people needing it. In an average month of 2024, 12.1% of Arizonans got SNAP, more than the 11.9% who lived below the poverty line that year (U.S. Department of Agriculture; Census Bureau). The share getting SNAP in June 2026 is about half the 2024 poverty rate.
In Yuma County and six reservation areas, USDA has waived SNAP’s three-month time limit for adults without dependents through Feb. 28, 2027 (see what changed).
Apply for SNAP through the Arizona Department of Economic Security →
What changed in Arizona in the past year
-
Oct. 8, 2026
APS customers are set to get a one-time bill credit in November
The Arizona Corporation Commission voted to return about $33.6 million from a renewable-energy fund to customers of Arizona Public Service (APS) as a credit on November 2026 bills, and to skip that fund’s monthly charge for the month. The commission puts the one-time savings for the average home at about $14.70. The charge is set to return Dec. 1. A separate APS request to raise its base rates is still before the commission (see what to watch).
-
Sept. 17, 2026
Arizona joins a settlement with a subprime car lender
Arizona and other states settled with Credit Acceptance Corporation, which lends to car buyers with weak or limited credit, for $694 million in cash and debt relief nationwide. The states alleged that the company made loans it knew or should have known buyers couldn’t afford, and that it encouraged, and failed to reasonably prevent, dealers’ packing of unwanted service contracts and other add-ons into those loans. Arizona consumers are due $3.82 million in debt relief and $1.02 million in restitution, Attorney General Kris Mayes’ office says. The settlement is set to take effect Nov. 2.
-
July 28, 2026
Paid marketplace sign-ups fall in Arizona
The number of Arizonans paying for a marketplace health plan in 2026 fell 30% from 2025, according to KFF’s analysis of federal enrollment figures. KFF notes that the drop nationwide coincided with the end of the larger federal help toward premiums after 2025. Paying the first premium is what puts a plan in force.
-
June 13, 2026
A state tax law covers tips, overtime and seniors
Gov. Katie Hobbs signed the state budget and a tax law, House Bill 4168. Arizonans can now subtract tips, overtime pay and the amount of the federal deduction for people 65 and older from their state taxable income, starting with the 2025 tax year. The state standard deduction rises to $15,750 for single filers and $31,500 for married couples filing jointly, also from 2025, and the credit for each dependent under 17 goes from $100 to $125 starting in 2026.
Office of the Governor, June 13, 2026; Arizona State Senate fact sheet, H.B. 4168
-
March 12, 2026
SNAP’s time limit is waived in Yuma County and six reservation areas
The U.S. Department of Agriculture approved Arizona’s request to set aside SNAP’s three-month time limit for adults without dependents, from March 1, 2026, through Feb. 28, 2027, in Yuma County and in the Cocopah, Hualapai, Ak-Chin, Salt River, San Carlos and Pascua Yaqui reservation areas (see SNAP). USDA’s letter calls the Ak-Chin area the Maricopa (Ak Chin) Indian Reservation; it isn’t Maricopa County.
-
Nov. 7, 2025
Arizona moves to pay full November SNAP benefits during the shutdown
During the federal government shutdown, after court action and new guidance from the U.S. Department of Agriculture, the Arizona Department of Economic Security approved sending the payment files so SNAP participants could get their full November benefits from USDA, the governor’s office said. Earlier, on Oct. 29, the governor had directed federal pandemic-relief money to the Arizona Food Bank Network and a new food voucher program.
How many Arizonans are behind on bills?
A slightly larger share than nationwide. In early 2025, 17.9% of Arizonans with a credit record had a debt 90 or more days late, 18th highest among the 50 states and D.C., against 17.2% for the U.S. (Federal Reserve Bank of Philadelphia). We calculate the national figure as an average of the states, weighted by population. This is debt people owe, not the state government’s.
Arizona’s place among the 50 states and D.C., 1 = the highest share: cards 17th highest, car loans tied for 18th highest, collections 19th highest, mortgages tied for 23rd highest. Each U.S. bar weights the states by population (our calculation).
A smaller share of Arizonans has a debt in collections than at the end of 2019, 14.3% against 18.6%, but credit reports changed in between. In 2022, the three big credit bureaus began dropping many medical debts from reports. Nationwide, the share of people with a medical collection on their record went from 14% in March 2022 to 5% in June 2023 (Consumer Financial Protection Bureau). Arizona’s collections share fell from 14.5% to 12.3% over those months and has risen since.
Counted in dollars, late card debt stands out
A second measure, from the Federal Reserve Bank of New York, counts dollars: the share of what people owe that is 90 or more days late. By that count, 13.7% of Arizona’s credit card balances were seriously late at the end of 2025, tied for 7th highest among the 50 states and D.C., against 12.4% nationwide. At the end of 2019, Arizona’s share was 3rd highest.
| Loan type | Arizona | U.S. | Arizona 2019 | U.S. 2019 |
|---|---|---|---|---|
| Credit card | 13.7% End of 2025 U.S. 12.4% Arizona 2019 10.4% · U.S. 2019 8.1% | 12.4% | 10.4% | 8.1% |
| Auto loan | 5.6% End of 2025 U.S. 5.2% Arizona 2019 5.2% · U.S. 2019 4.9% | 5.2% | 5.2% | 4.9% |
| Mortgage | 0.9% End of 2025 U.S. 0.9% Arizona 2019 0.6% · U.S. 2019 1.0% | 0.9% | 0.6% | 1.0% |
Share of balances 90 or more days past due at the end of 2025 and the end of 2019. Source: Federal Reserve Bank of New York, Consumer Credit Panel / Equifax. This counts dollars, so it doesn’t line up with the Philadelphia Fed’s count of people above, and it includes old debts lenders have written off but still report.
Homeowners with a thin cushion
In the second quarter of 2026, 7.2% of Arizona mortgages had less than 10% equity, tied for 3rd highest among the 50 states and D.C., against 4.7% nationwide (Federal Housing Finance Agency). Equity is what the home is worth minus what’s still owed on it.
| Measure | Arizona | U.S. | Rank |
|---|---|---|---|
| Underwater mortgages, worth less than what’s owed, April to June 2026 Tied for 7th highest | 0.4% U.S. 0.3% | 0.3% | Tied for 7th highest |
| Mortgages 30 to 89 days late, Sept. 2025 Tied for 28th highest | 1.5% U.S. 1.6% | 1.6% | Tied for 28th highest |
| Household debt per person with a credit report, end of 2025 11th highest | $70,850 U.S. $63,200 | $63,200 | 11th highest |
Rank among the 50 states and D.C., 1 = the highest. Underwater mortgages: Federal Housing Finance Agency. Payments 30 to 89 days late, an early stage of falling behind: Consumer Financial Protection Bureau. Debt per person: Federal Reserve Bank of New York. Late payments in every state →
Arizona’s bankruptcy filings rose to the most since 2020
Arizonans filed 12,891 bankruptcy cases in 2025, up 13.7% from 2024 and the most since 2020, when they filed 13,515 (Administrative Office of the U.S. Courts). Filings have risen every year since 2022, when there were 8,961. Measured per person, Arizona sits near the middle: 170.0 filings for every 100,000 residents (2024 population), 22nd highest of the 50 states and D.C., against 167.1 nationwide.
Most Arizonans who file use Chapter 7, which can wipe out many debts. Only 16.4% of the state’s 2025 filings were under Chapter 13, in which a filer repays part of the debts through a court-approved plan, the 8th lowest share of the 50 states and D.C., against 35.9% nationwide.
| Year | Filings |
|---|---|
| 2010 | 42,829 |
| 2019 | 16,933 |
| 2020 | 13,515 |
| 2021 | 9,884 |
| 2022 | 8,961 |
| 2023 | 9,599 |
| 2024 | 11,335 |
| 2025 | 12,891 |
Cases of every chapter filed in the U.S. Bankruptcy Court for the District of Arizona each calendar year. 2010 had more filings than any year from 2006 to 2025. Source: Administrative Office of the U.S. Courts, Table F-2. Bankruptcy filings in every state →
How foreclosure works in Arizona
In Arizona, most foreclosures happen without a court. Homes here are usually bought with a deed of trust, which lets a trustee sell the home at a trustee’s sale once a notice of sale is recorded. The sale can’t come before the 91st day after that notice (A.R.S. § 33-808). You can stop the sale by catching up on what’s due until 5 p.m. on the last business day before it (A.R.S. § 33-813). Once the sale happens it’s final: there’s no right to buy the home back (A.R.S. § 33-811). After a trustee’s sale of a one- or two-family home on 2.5 acres or less, the lender generally can’t sue for any balance left over. Some properties on loans made after 2014 are exceptions, including a home that was never finished (A.R.S. § 33-814). Federal rules generally bar the first foreclosure filing until a home loan is more than 120 days behind.
- Goes through a court
- Usually not
- Earliest sale after the notice
- 91 days
- Last day to catch up and stop the sale
- Day before sale
- Buy-back right after the sale
- None
- Lender can seek the balance after a home sale
- Usually not
- Statewide foreclosure mediation
- No
What the law says for a home you live in. Separately, Arizona’s homestead exemption protects home equity from most creditors, up to $400,000, adjusted for inflation each year since 2024 (A.R.S. § 33-1101); it doesn’t stop a mortgage lender from foreclosing. Sources: Arizona Revised Statutes §§ 33-808, 33-811, 33-813, 33-814 and 33-1101; federal rule 12 CFR 1024.41. How foreclosure works in Arizona →
Arizona received a $197.0 million award from the federal Homeowner Assistance Fund and had helped 12,573 households through early 2026 (U.S. Treasury).
What Arizona homeowners tell the CFPB about their mortgage companies
Since 2012, Arizonans have sent the Consumer Financial Protection Bureau 10,437 complaints about mortgages. The most common issue is trouble during the payment process (2,552), just ahead of loan modifications, collection and foreclosure (2,517), then loan servicing, payments or escrow (1,850).
- Oct. 12, 2026 Longbridge Financial, LLC Trouble during payment process: Trying to communicate with the company to fix an issue while managing or servicing your loan Closed with explanation
- Oct. 6, 2026 U.S. Bank Struggling to pay mortgage: An existing modification, forbearance plan, short sale, or other loss mitigation relief Closed with monetary relief
- Oct. 5, 2026 Longbridge Financial, LLC Struggling to pay mortgage: Foreclosure Closed with explanation
- Oct. 3, 2026 Ocwen / Onity Group Struggling to pay mortgage: Trying to communicate with the company to fix an issue related to modification, forbearance, short sale, deed-in-lieu, bankruptcy, or foreclosure Closed with explanation
- Oct. 2, 2026 Rocket Mortgage Struggling to pay mortgage: An existing modification, forbearance plan, short sale, or other loss mitigation relief Closed with explanation
- Oct. 2, 2026 U.S. Bank Struggling to pay mortgage: Foreclosure Closed with monetary relief
- Sept. 30, 2026 Dovenmuehle Mortgage Trouble during payment process: Payment process Closed with explanation
- Sept. 30, 2026 PennyMac Struggling to pay mortgage: Applying for or obtaining a modification, forbearance plan, short sale, or deed-in-lieu Closed with explanation
- Sept. 29, 2026 MidFirst Bank Struggling to pay mortgage: Trying to communicate with the company to fix an issue related to modification, forbearance, short sale, deed-in-lieu, bankruptcy, or foreclosure In progress
- Sept. 29, 2026 CrossCountry Mortgage Struggling to pay mortgage: Trying to communicate with the company to fix an issue related to modification, forbearance, short sale, deed-in-lieu, bankruptcy, or foreclosure In progress
The 10 most recent Arizona complaints about paying a mortgage or getting help with one, newest first, from the Consumer Financial Protection Bureau’s public complaint record as of Oct. 14, 2026. Complaints about getting a new loan, and complaints naming a credit reporting company, are left out. Each is one person’s account: the bureau doesn’t confirm what people tell it, and a complaint isn’t a finding against the company. Every Arizona mortgage complaint at the Consumer Financial Protection Bureau →
What to watch before the next edition
Four dates between now and the end of 2026, nearest first: a data release, a settlement and two steps on APS power bills.
-
Oct. 20, 2026
September jobless rates for every state
The Bureau of Labor Statistics is scheduled to publish September’s state unemployment rates. Arizona’s Office of Economic Opportunity has already put the state’s September rate at 4.9%, unchanged from August.
Bureau of Labor Statistics, State Employment and Unemployment, Sept. 18, 2026; Arizona Office of Economic Opportunity, Oct. 15, 2026
-
Nov. 2, 2026
The Credit Acceptance settlement is set to take effect
Debt relief on qualifying car loans made from Nov. 1, 2015, to Nov. 30, 2025, is due by this date under the settlement Arizona joined in September (see what changed).
-
November 2026
The APS credit is set to appear on bills
APS customers’ November bills are set to carry the one-time credit, without the monthly renewable-energy charge, which is set to return Dec. 1.
-
Dec. 31, 2026
Deadline for a vote on APS’s rate request
The Arizona Corporation Commission must vote by this date on APS’s request to raise its base rates; a judge’s recommended decision is expected by late November. If the commission approves it, new rates are expected sometime in early 2027. APS estimates a typical home using 1,000 kilowatt-hours a month would pay around $20 more a month if the request were approved as proposed.
Arizona Corporation Commission, July 10, 2026; APS rate case page
Where Arizona ranks highest and lowest
| Measure | Arizona | U.S. | Rank | Latest data |
|---|---|---|---|---|
| Mortgages with less than 10% equity Tied for 3rd highest · Apr.–June 2026 | 7.2% U.S. 4.7% | 4.7% | Tied for 3rd highest | Apr.–June 2026 |
| Unemployment rate, three-month average Tied for 8th highest · June–August 2026 | 4.9% U.S. 4.1% | 4.1% | Tied for 8th highest | June–August 2026 |
| Credit card balances 90+ days late Tied for 7th highest · End of 2025 | 13.7% U.S. 12.4% | 12.4% | Tied for 7th highest | End of 2025 |
| Population growth since 2020 8th highest · 2025 | 6.1% U.S. 3.1% | 3.1% | 8th highest | 2025 |
| Residents without health insurance 9th highest · 2024* | 10.5% U.S. 8.4% | 8.4% | 9th highest | 2024* |
| Household debt per person with a credit report 11th highest · End of 2025 | $70,850 U.S. $63,200 | $63,200 | 11th highest | End of 2025 |
| Residents 65 or older Tied for 12th highest · 2024* | 18.9% U.S. 17.2% | 17.2% | Tied for 12th highest | 2024* |
| Median rent, a month 13th highest · 2024* | $1,543 U.S. $1,413 | $1,413 | 13th highest | 2024* |
| People with a debt 90+ days late 18th highest · Early 2025 | 17.9% U.S. 17.2% | 17.2% | 18th highest | Early 2025 |
| People with a debt in collections 19th highest · Early 2025 | 14.3% U.S. 13.2% | 13.2% | 19th highest | Early 2025 |
| Median household income 21st highest · 2024 | $81,404 U.S. $81,604 | $81,604 | 21st highest | 2024 |
| Residents in poverty 22nd highest · 2024 | 11.9% U.S. 12.1% | 12.1% | 22nd highest | 2024 |
| Bankruptcy filings per 100,000 residents (2024 population) 22nd highest · 2025 | 170.0 U.S. 167.1 | 167.1 | 22nd highest | 2025 |
| Income per person 18th lowest · 2024 | $65,798 U.S. $73,204 | $73,204 | 18th lowest | 2024 |
| Residents getting SNAP food benefits (2024 population) 5th lowest · June 2026 | 5.6% U.S. 10.7% | 10.7% | 5th lowest | June 2026 |
Each rank places Arizona among the 50 states and D.C.: “highest” counts down from the top, “lowest” up from the bottom. * Census five-year survey, 2020 to 2024. Population growth: Census Bureau estimates; the U.S. figure adds up the 50 states and D.C. (our calculation). People behind or in collections: the Federal Reserve Bank of Philadelphia’s count among people with a credit record; its U.S. figure weights each state by population (our calculation). Sources for every row are in Sources and method. Download this table: CSV.
Questions about Arizona
Is Arizona a poor state?
No, it’s near the middle. In 2024, 11.9% of Arizonans lived in poverty, 22nd highest among the 50 states and D.C., and the typical household earned $81,404, the 21st highest, close to the U.S. median (U.S. Census Bureau, Small Area Income and Poverty Estimates). Income per person, $65,798 in 2024, was lower, the 18th lowest (U.S. Bureau of Economic Analysis).
What is the poorest county in Arizona?
Apache County, in the northeast. Its poverty rate, 29.3% in 2024, was the highest of Arizona’s 15 counties, and its typical household income, $43,939, the lowest (U.S. Census Bureau, Small Area Income and Poverty Estimates). It is also the most distressed county in the state on our County Distress Index.
How is Arizona’s economy doing?
Jobs are growing, but unemployment is high. The rate was 4.9% in August 2026, tied for 6th highest among the 50 states and D.C. (U.S. Bureau of Labor Statistics). In September 2026 the state had 22,700 more jobs than a year before, while its labor force shrank by 121,241 (Arizona Office of Economic Opportunity).
Is it cheaper to live in Arizona or California?
Rent is cheaper in Arizona: a median of $1,543 a month from 2020 to 2024, against $2,036 in California (U.S. Census Bureau). California’s typical household earns more, $100,130 in 2024 against $81,404, so rent took 24.4% of the typical income there and 22.7% in Arizona (our calculation). We don’t measure other prices, so we can’t compare the whole cost of living.
What is the poverty line in Arizona?
Arizona uses the federal poverty guideline, the same figures as every state except Alaska and Hawaii: for 2026, $15,960 a year for one person and $33,000 for a family of four (U.S. Department of Health and Human Services). The Census Bureau’s own poverty line, behind the 11.9% figure on this page, is a separate measure.
How much is Arizona’s homestead exemption?
State law protects equity in the home you live in from most creditors, up to $400,000, adjusted for inflation each year since 2024 (A.R.S. § 33-1101). It doesn’t stop a mortgage lender from foreclosing. How foreclosure works in Arizona →
Cite or reuse Arizona’s data
Free to quote, with credit, in news stories, research and grant applications.
State Distress Index
Arizona
7thmost distressed state
of the 50 states and D.C.
More distressed than 88% of the other states and D.C.
On American Default Research’s State Distress Index, which measures strain on household finances, Arizona ranks 7th most distressed among the 50 states and D.C. overall. Its median household income, $81,404 in 2024, was close to the U.S. median (U.S. Census Bureau). But its unemployment rate, 4.9% in August 2026, was tied for 6th highest (U.S. Bureau of Labor Statistics). The number of Arizonans getting SNAP food benefits fell 52.5% from June 2025 to June 2026, the largest drop of any state (U.S. Department of Agriculture).
For interviews or a custom cut of the data, write to press@americandefault.org
Sources and method
We gather the data, run the numbers and research each state ourselves.
This edition: October 2026 · Next edition expected March 2027
- Unemployment, state, county and national, monthly and yearlyU.S. Bureau of Labor Statistics, Local Area Unemployment StatisticsJan. 1990 to Aug. 2026
- Jobs and labor force, September 2026Arizona Office of Economic Opportunity, Arizona employment reportOct. 15, 2026
- Poverty and household incomeCensus Bureau, Small Area Income and Poverty Estimates1989 to 2024
- Renters spending at least half their income on housingCensus Bureau, American Community Survey, one-year estimates2005 to 2024
- Rent, renters’ costs, age, schooling, disability, health insuranceCensus Bureau, American Community Survey, five-year estimates2020 to 2024
- American Indian and Alaska Native residents, by countyCensus Bureau, American Community Survey, table B020012020 to 2024
- PopulationCensus Bureau, population estimates2020 to 2025
- Income per person and benefits’ share of incomeU.S. Bureau of Economic Analysis2024
- Late payments and collectionsFederal Reserve Bank of Philadelphia, Consumer Credit Explorerend of 2019 to early 2025
- Household debt and dollars behindFederal Reserve Bank of New York, Consumer Credit Panel / Equifaxend of 2019 and end of 2025
- Mortgages with little or no equityFederal Housing Finance Agency, National Mortgage Databasesecond quarter of 2026
- Mortgages 30 to 89 days late; mortgage complaints; medical debts on credit reportsConsumer Financial Protection Bureau: Mortgage Performance Trends; complaint database; Recent changes in medical collections on consumer credit recordsSept. 2025; Oct. 14, 2026; March 2022 to June 2023
- Bankruptcy filingsAdministrative Office of the U.S. Courts, Table F-22006 to 2025
- SNAPUSDA Food and Nutrition Administration; time-limit waiver letter2024 to June 2026; March 12, 2026
- Why SNAP fell: the explanationsArizona’s Family; ProPublicaMay 26, 2026; April 8, 2026
- Cost of getting byMIT Living Wage CalculatorFebruary 2026 update
- Mortgage help fundU.S. Treasury, Homeowner Assistance Fundthrough early 2026
- Foreclosure and homestead lawArizona Revised Statutes §§ 33-808, 33-811, 33-813, 33-814 and 33-1101; 12 CFR 1024.41as of 2026
- Poverty guidelineU.S. Department of Health and Human Services2026
- Housing counselorsU.S. Department of Housing and Urban DevelopmentOctober 2026
- What changed and what to watchArizona Corporation Commission, Arizona Attorney General, KFF, Office of the Governor, Arizona State Senate, APS, Bureau of Labor Statistics release, Census Bureau release schedule; each item above links its own source (see what changed)Nov. 2025 to Dec. 2026
- PhotoMobilus In Mobili, via Wikimedia Commons, CC BY-SA 2.02022
The score has four equal parts: jobs; renters’ housing costs; late payments; and collections and bankruptcy. Each measure is scored against the 50 states and D.C., and the score is the share of the other 50 whose four-part average is below Arizona’s. The full method →
We write with AI tools, and Ross Kilburn checks and reviews every page before it's published.
Get the next Arizona edition by email
One email each time a new Arizona edition is out; the next is expected in March 2027. Unsubscribe anytime.
Thanks, that helps.