Vermonters file bankruptcy at about a quarter of the U.S. rate: 43.9 per 100,000, 3rd lowest
Each state is shaded by how distressed its households are, from green (least) to red (most), with data through September 2026. Vermont scores 6 out of 100.
Housing, not debt, is where Vermont's strain shows: in 2024, 23.6% of renters gave at least half their income to rent and utilities, and that part of the score is its highest. Few Vermont debts reach a collector: in early 2025, 8.6% of Vermonters with a credit record had one in collections, among the lowest shares in the nation. Essex County, Vermont's poorest, is more distressed than 36% of U.S. counties, more than any other county in the state.
- Score
- 6/100
- Data through
- September 2026
- Edition
- October 2026
Next edition expected March 2027
How Vermont ranks among the states
Vermont is near the low end of the State Distress Index, and its collections and bankruptcy measures pull its score down most. The Federal Reserve Bank of Philadelphia found 8.6% of people with a credit record had a debt in collections in early 2025. That was among the lowest shares in the nation. Housing costs cut against the calm picture: 24.9% of Vermont owner households spent at least 30% of income on housing, above the U.S. 22.5%. Owners’ costs are context, not an input to this state index.
What drives the score
The index ranks each measure among the states and D.C. A part with several measures averages their positions; the four parts then form a combined average. The displayed Vermont score counts how many other places have a lower combined average; it does not average the four displayed part scores. On this scale, 80 would place a state above four in every five other places.
- Collections and bankruptcy6Both debts in collections and bankruptcy filings per resident sit near the bottom of the state lists.
- Late payments10Card, car-loan and mortgage borrowers were less likely to be seriously behind than borrowers nationally in early 2025.
- Jobs5This is Vermont’s lowest part. Vermont’s unemployment averaged 2.6% from June through August 2026; the national average for those months was 4.1%.
- Renters’ housing costs28This is Vermont’s highest part. 23.6% of renters spent at least half their income on housing in 2024.
Vermont’s quarterly index never reached the middle of the scale
At its highest
Vermont’s highest score in the quarterly series was 30. The state ranked 36th at that point; the chart keeps the full period visible.
At its lowest
Its lowest quarterly score was 6. A low score places Vermont near the less distressed end of this national measure.
After the chart
The history ends in the first quarter of 2025 at 8. Today’s score is 6, using later jobs and renter data; the two readings do not share one release date.
Vermont’s quarterly distress score stayed in the lower half of the scale
State Distress Index history from the first complete quarter through early 2025. Today’s score uses newer inputs.
Is Vermont expensive to live in? Rent is below the U.S. median, but many renters are strained
Vermont’s median monthly gross rent was $1,234 in the Census Bureau’s 2020–2024 survey, below the national $1,413. In its separate 2024 survey, 23.6% of Vermont renters spent at least half their income on housing and utilities. The national share was 26.1%. These measures do not cover groceries, transportation, utilities outside rent or taxes, so they are not a complete price index.
Median gross rent each month
$1,234
U.S. $1,413
Census Bureau, 2020–2024
Renters spending half their income on housing
23.6%
U.S. 26.1%
Census Bureau, 2024
Owners spending at least 30% on housing
24.9%
U.S. 22.5%
Census Bureau, 2020–2024
What the rent figure leaves out
A statewide median can sit below the U.S. figure while individual households still spend a large share of income to stay housed. The renter-burden estimate measures each household’s own payments against its income. The two estimates use different Census surveys, so dividing the medians would give the wrong answer.
Vermont’s median household income was $82,836 in the Census Bureau’s 2024 county-based estimates. In the separate five-year survey, 73.2% of homes were owner-occupied. Those figures add context, but neither says what a new renter or buyer can afford.
Vermont sets education property-tax rates statewide, while local bills vary. The Vermont Department of Taxes explains the rates; a state index or median rent cannot determine a particular bill.
Essex has Vermont’s highest poverty and distress; Lamoille has its lowest distress
Essex County had the highest poverty rate in Vermont in the Census Bureau’s 2024 Small Area Income and Poverty Estimates: 13.8%. It also has the state’s highest County Distress Index score, 36. Lamoille has the lowest distress score, 5. Washington County had the lowest poverty rate, 6.1%. Poverty and distress identify different county households, even where their extremes coincide.
The county index is darkest in Essex, Bennington and Orleans
Vermont’s 14 counties, shaded by County Distress Index score from 0 to 100.
Loading the county map…
The county map could not be loaded. Every county is in the lists on this page.
Most distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 1 | Essex | 36 | 13.8% |
| 2 | Bennington | 35 | 9.9% |
| 3 | Orleans | 33 | 11.9% |
| 4 | Rutland | 29 | 10.0% |
| 5 | Franklin | 22 | 8.8% |
| 6 | Windham | 20 | 11.4% |
| 7 | Caledonia | 20 | 11.0% |
| 8 | Grand Isle | 18 | 8.0% |
| 9 | Windsor | 15 | 9.2% |
| 10 | Orange | 12 | 9.8% |
Least distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 10 | Orange | 12 | 9.8% |
| 11 | Addison | 7 | 8.0% |
| 12 | Chittenden | 7 | 8.9% |
| 13 | Washington | 6 | 6.1% |
| 14 | Lamoille | 5 | 8.9% |
Vermont rank, with 1 the most distressed county. Scores round for display while rank uses the unrounded score. Poverty is from the U.S. Census Bureau’s 2024 county estimates.
Every county, by score
The lightest map band holds 11 of Vermont’s 14 counties. The other 3 fall between 30 and 49. No Vermont county reaches the three darker national score bands. This describes the index’s selected measures, not every household expense.
0 score 80–100
0 score 70–79
0 score 50–69
3 score 30–49
11 score 0–29
Rutland, Franklin, Windham, Caledonia, Grand Isle, Windsor, Orange, Addison, Chittenden, Washington, Lamoille
County poverty and distress do not make the same ranking
Orleans had Vermont’s second-highest poverty rate, 11.9%, but its distress score ranks 3rd. Windham’s poverty rate ranked 3rd, while its distress score ranked 6th. The index also uses debt, late payments, work and housing costs. Washington had the lowest poverty rate, 6.1%, yet Lamoille had the lowest distress score. These contrasts come from separate measures, not a claim that one caused another.
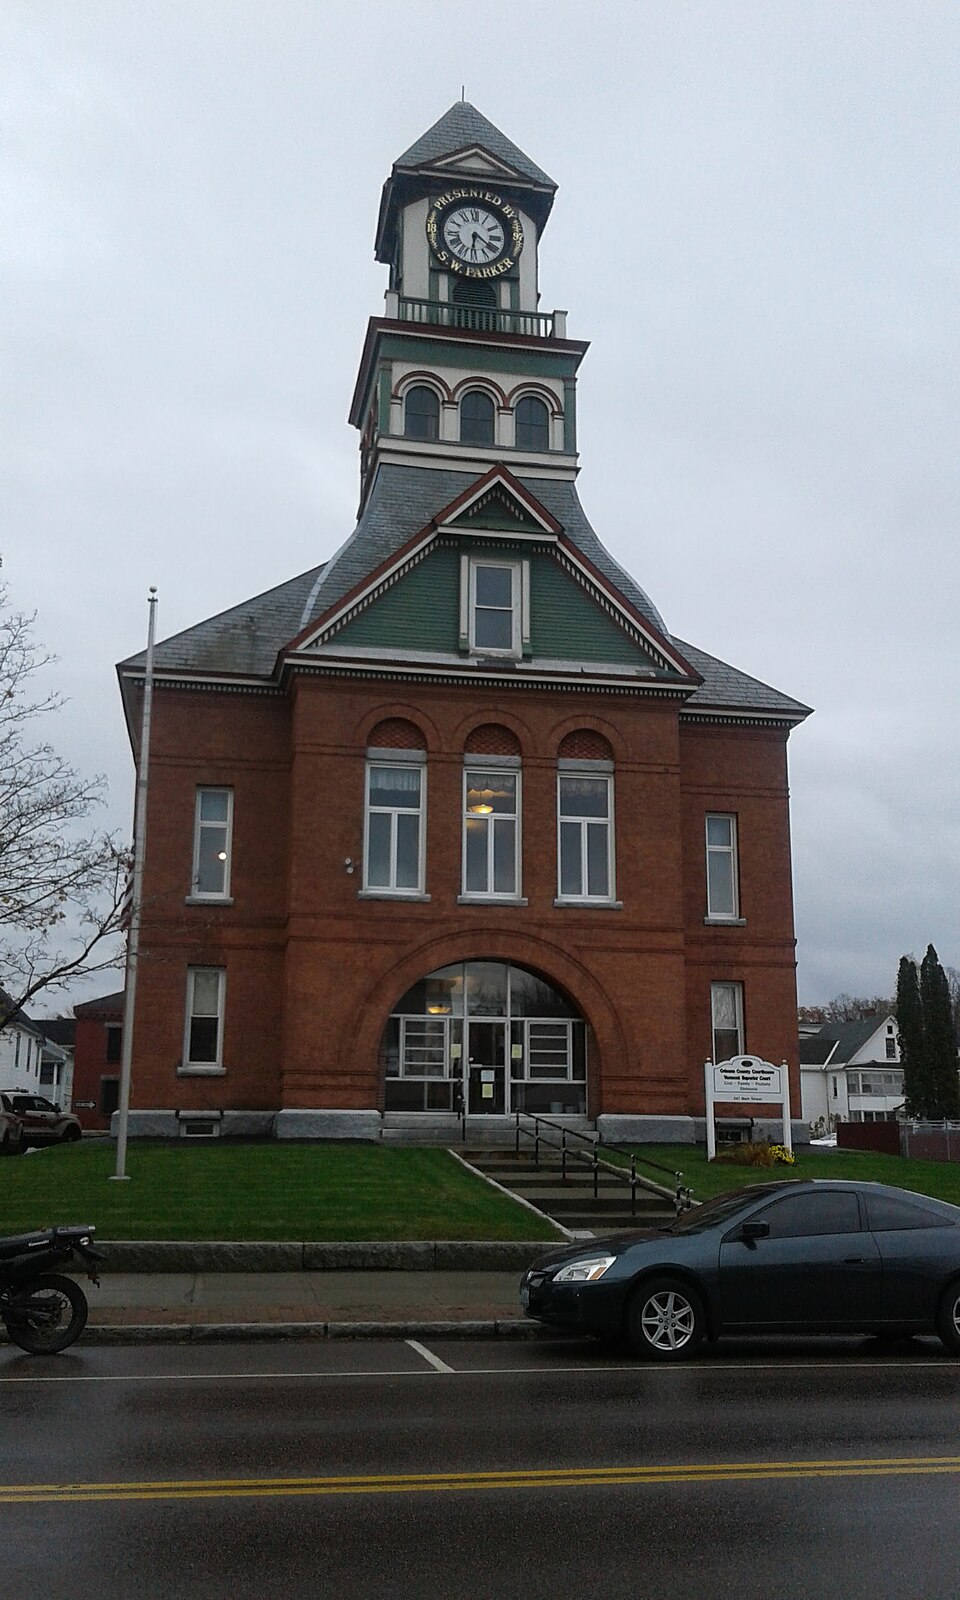
The Orleans County Courthouse in Newport. Orleans had Vermont’s second-highest county poverty rate, 11.9%, in the Census Bureau’s 2024 estimates.
Photo: Artaxerxes / Wikimedia Commons, CC BY-SA 4.0. Figure: U.S. Census Bureau.

The state score hides a small but distinct northern spread
Essex scores 36 and Orleans 33, compared with 5 in Lamoille. Essex also has Vermont’s lowest median household income, $56,992, while Grand Isle has the highest, $98,799. The county index does not treat income as a direct cause of a debt outcome.
American Default Research, County Distress Index; U.S. Census Bureau, Small Area Income and Poverty Estimates, 2024.
Vermont’s poverty rate is low nationally, but Essex County stands apart
The Census Bureau estimated Vermont’s 2024 poverty rate at 9.3%, compared with 12.1% nationwide. Only a few states had a lower poverty estimate that year: Vermont ranked tied for 5th lowest. Essex County reached 13.8%; Washington County was at 6.1%. These are Small Area Income and Poverty Estimates, not the American Community Survey poverty series used on some other sites.
Residents in poverty
9.3%
U.S. 12.1%
Tied for 5th lowest among states and D.C.; 2024
Children in poverty
9.7%
U.S. 15.5%
2024
Median household income
$82,836
U.S. $81,604
2024
The next chart follows Vermont and the U.S. poverty rates across the published Census series. Missing years are gaps in the source, not years without poverty.
Vermont’s poverty rate ends below the national rate
Census Bureau Small Area Income and Poverty Estimates, through 2024.
A poverty threshold is only one way to locate financial pressure. Vermont’s 58,465 residents receiving SNAP in USDA’s cited count and the county differences add context, but these files cannot establish whether everyone eligible receives food help.
What changed in Vermont in the past year
These dated changes affect housing costs or public benefits. The index does not attribute a score move to any one of them.
-
Oct. 1, 2026
New 3SquaresVT income guidelines took effect
Vermont’s Department for Children and Families posted its October income guidelines for 3SquaresVT, the state’s SNAP program. The published table sets gross and net monthly income limits by household size. It is a rule for potential eligibility, not a count of recipients or a prediction of benefit changes.
Vermont Department for Children and Families, October 2026 3SquaresVT income guidelines
-
Oct. 1, 2026
Some Medicaid eligibility rules changed
The Department of Vermont Health Access says federal rules narrowed Medicaid eligibility for some immigrants on this date. It says other changes for some adults are scheduled later. This change is separate from the unemployment and debt series in the state index.
-
July 1, 2026
A new education property-tax year began
Vermont’s 2026 legislature set the yields and statewide nonhomestead rate for fiscal year 2027 in Act 169. A household’s bill also depends on local rates, property value and any credit; the law’s statewide figures are not a household quote.
-
June 18, 2026
Property-transfer and valuation rules changed
Act 164 clarified when a transferred property may use the lower long-term-rental property-transfer-tax rate. The same act changed several valuation and appeal provisions. These provisions concern property administration, not the index’s measured household distress.
-
April 16, 2026
Storm damage and a power outage reached central Vermont
The National Weather Service documented a tornado near Williamstown and damaging wind in Orange County. Utilities reported power outages in the affected area. The event shows a local household disruption; no dollar-loss estimate or link to statewide distress is established here.
National Weather Service, April 2026 Williamstown tornado review
Vermont’s jobless rate is low; Essex has a higher county rate
The U.S. Bureau of Labor Statistics estimated Vermont’s seasonally adjusted August 2026 unemployment rate at 2.6%, below the U.S. 4.1%. Essex County’s county rate was 3.1%; Addison’s was 2.3%. County rates are not seasonally adjusted, so they do not use exactly the same method as the state rate.
Vermont unemployment
2.6%
U.S. 4.1%
August 2026, seasonally adjusted
Three-month average
2.6%
U.S. 4.1%
June–August 2026
Population change
0.3%
Census Bureau, 2020–2025
The unemployment chart shows the state and national paths behind today’s comparison. It gives more context than a single month without treating a short move as a lasting shift.
Vermont’s unemployment rate ends below the U.S. rate
Seasonally adjusted monthly unemployment rates through August 2026.
Unemployment measures people seeking work, not every source of household income. The Bureau of Economic Analysis estimates wages accounted for 44.7% of Vermont personal income in 2024, against 49.7% nationally. Transfers and investments make up other parts of that accounting.
Fewer Vermont borrowers are seriously late on cards and car loans
In the Federal Reserve Bank of Philadelphia’s early 2025 records, 8.8% of Vermont card borrowers were at least 90 days late, compared with a population-weighted U.S. state average of 13.5%. Car-loan and mortgage borrower rates were also below their national comparisons. These are shares of people who hold each kind of credit, not shares of all Vermonters.
Borrowers who are behind
Vermont’s gaps with the national shares appear together below for cards, auto loans, mortgages and collections. Each bar uses the Philadelphia Fed’s borrower measure; the collection share counts people with a credit record.
Dollars late are a separate measure
The Federal Reserve Bank of New York’s panel counts the share of loan dollars at least 90 days late. For Vermont card balances, the end-of-2025 share was 9.0%, against 12.4% nationally. It was 5.8% in 2019. These dollar shares do not replace the Philadelphia Fed’s borrower shares.
| Measure | Vermont | U.S. | Vermont in 2019 |
|---|---|---|---|
| Card dollars 90+ days late Vermont in 2019 5.8% | 9.0% U.S. 12.4% | 12.4% | 5.8% |
| Car-loan dollars 90+ days late Vermont in 2019 3.2% | 2.8% U.S. 5.2% | 5.2% | 3.2% |
| Mortgage dollars 90+ days late Vermont in 2019 1.1% | 0.6% U.S. 0.9% | 0.9% | 1.1% |
| Household debt per credit-file person Vermont in 2019 $46,490 | $52,910 U.S. $63,200 | $63,200 | $46,490 |
Federal Reserve Bank of New York, Consumer Credit Panel / Equifax. End-of-year values. Household debt here is what people owe, not Vermont government debt.
Vermont has one of the lowest bankruptcy filing rates
U.S. Courts recorded 283 Vermont bankruptcy filings in 2025. Using the Census Bureau’s 2025 population, the rate was 43.9 per 100,000 residents, 3rd lowest among the states and D.C. Filings are cases opened in court, not a count of households currently late on a bill.
Filings per 100,000 residents
43.9
U.S. 166.3
2025 population; 3rd lowest
All filings
283
2025
Chapter 13 share
21.9%
U.S. 35.9%
2025 filings
The filing rate and late-payment chart cover different events and populations. Vermont’s 2025 filings were above the 2024 count, but the state remained near the low end of the national per-resident list. The court’s table does not show case outcomes. Read national bankruptcy statistics →
Mortgage trouble is uncommon in the measured panel; Vermont foreclosure has its own rules
Among Vermont mortgage borrowers, 0.9% were at least 90 days late in the Philadelphia Fed’s early 2025 panel; the corresponding national share was 1.2%. The Federal Housing Finance Agency estimated 2.1% of Vermont mortgages had less than 10% equity in the second quarter of 2026. Those figures do not count foreclosure filings or identify what happens to an individual loan.
Vermont’s foreclosure process depends on the mortgage and court record. The Vermont foreclosure overview explains the general rules and points to local sources; it is not a conclusion about any one case.
What Vermont mortgage borrowers reported to the CFPB
The Consumer Financial Protection Bureau’s public database holds 740 Vermont mortgage complaints from January 2012 through the October 2026 cutoff. The newest reports about payments or mortgage help appear below. The bureau records consumer accounts; it does not verify each allegation or estimate how often a problem occurs among all borrowers.
- Oct. 5, 2026 Carrington Mortgage Payment process: fees charged In progress
- Sept. 11, 2026 Shellpoint / NewRez Payment process: paying off the loan In progress
- Aug. 31, 2026 Truist Financial Payment process: trouble reaching the company to fix a problem with the loan Closed with explanation
- Aug. 21, 2026 Freedom Mortgage Struggling to pay: applying for a modification, forbearance, short sale or deed-in-lieu Closed with explanation
- Aug. 19, 2026 CMG Financial Payment process Closed with explanation
- Aug. 17, 2026 Rocket Mortgage Payment process: escrow, taxes or insurance Closed with explanation
- Aug. 13, 2026 Truist Financial Payment process: escrow, taxes or insurance Closed with explanation
- Aug. 13, 2026 CrossCountry Mortgage Payment process: private mortgage insurance Untimely response
- July 8, 2026 Shellpoint / NewRez Payment process: paying off the loan Closed with explanation
- July 4, 2026 Rocket Mortgage Payment process: trouble reaching the company to fix a problem with the loan Closed with explanation
Latest Vermont mortgage payment and assistance complaints in the CFPB database. Each is a consumer report, not an agency finding.
The Vermont foreclosure overview lists the general process and public help sources.
What to watch before the next Vermont edition
These scheduled decisions and releases come after the October 2026 figures.
-
Nov. 20, 2026
October state unemployment report
The U.S. Bureau of Labor Statistics schedules state unemployment rates for October. Monthly estimates can be revised.
-
Jan. 1, 2027
Federal Medicaid changes for some adults
Vermont’s Department of Vermont Health Access lists work and eligibility-review changes scheduled for some adults. The final effects on enrollment are not measured in the October 2026 figures.
-
Jan. 15, 2027
State housing report due
The Vermont Legislature’s 2026 act summary schedules a report from the State Treasurer on the Off-Site Construction Accelerator Pilot Program. A due date is not a finding about homes built.
Where Vermont ranks highest and lowest
The table keeps each measure’s producer, period and direction visible. A low rank in a distress measure does not give the same reading as a low income rank.
| Measure | Vermont | U.S. | Rank | Latest data |
|---|---|---|---|---|
| Homeownership rate Tied for 3rd highest · 2020–2024* | 73.2% U.S. 65.2% | 65.2% | Tied for 3rd highest | 2020–2024* |
| Owners spending at least 30% on housing 10th highest · 2020–2024* | 24.9% U.S. 22.5% | 22.5% | 10th highest | 2020–2024* |
| Median gross rent each month 26th highest · 2020–2024* | $1,234 U.S. $1,413 | $1,413 | 26th highest | 2020–2024* |
| Renters spending half their income on housing 20th lowest · 2024 | 23.6% U.S. 26.1% | 26.1% | 20th lowest | 2024 |
| Median household income 20th highest · 2024 | $82,836 U.S. $81,604 | $81,604 | 20th highest | 2024 |
| Residents in poverty Tied for 5th lowest · 2024 | 9.3% U.S. 12.1% | 12.1% | Tied for 5th lowest | 2024 |
| Children in poverty 4th lowest · 2024 | 9.7% U.S. 15.5% | 15.5% | 4th lowest | 2024 |
| Unemployment rate, three-month average 3rd lowest · June–August 2026 | 2.6% U.S. 4.1% | 4.1% | 3rd lowest | June–August 2026 |
| People with a debt in collections Tied for 6th lowest · Early 2025 | 8.6% U.S. 13.2% | 13.2% | Tied for 6th lowest | Early 2025 |
| Card borrowers 90+ days late 4th lowest · Early 2025 | 8.8% U.S. 13.5% | 13.5% | 4th lowest | Early 2025 |
| Car-loan borrowers 90+ days late Tied for 3rd lowest · Early 2025 | 4.6% U.S. 8.5% | 8.5% | Tied for 3rd lowest | Early 2025 |
| Mortgage borrowers 90+ days late Tied for 15th lowest · Early 2025 | 0.9% U.S. 1.2% | 1.2% | Tied for 15th lowest | Early 2025 |
| Bankruptcy filings per 100,000 residents (2025 population) 3rd lowest · 2025 | 43.9 U.S. 166.3 | 166.3 | 3rd lowest | 2025 |
| Household debt per credit-file person 19th lowest · End of 2025 | $52,910 U.S. $63,200 | $63,200 | 19th lowest | End of 2025 |
Ranks compare the 50 states and D.C.; tied printed values share a rank. *Census Bureau five-year survey, 2020–2024. The renter-cost share is from its separate one-year survey. Philadelphia Fed figures count borrowers; New York Fed debt counts dollars. Sources and method names the producers. Download the table as CSV.
Questions about Vermont
Is Vermont expensive to live in?
The Census Bureau’s median monthly gross rent was $1,234 in its 2020–2024 survey, below the U.S. $1,413. Still, 23.6% of Vermont renters spent at least half their income on housing in 2024. These figures do not cover every price. Read the cost picture →
What is Vermont’s poverty rate?
The Census Bureau’s Small Area Income and Poverty Estimates put Vermont at 9.3% in 2024, against 12.1% nationwide. Essex County reached 13.8%. Other Census surveys may give different rates because their methods differ. See poverty and income →
Which is the poorest county in Vermont?
Essex County had both the highest 2024 poverty rate, 13.8%, and the lowest median household income, $56,992, in the Census Bureau’s county estimates. It also leads Vermont’s County Distress Index. The measures answer different questions. Compare the counties →
What is Vermont’s unemployment rate?
The U.S. Bureau of Labor Statistics estimated Vermont’s seasonally adjusted rate at 2.6% in August 2026. The U.S. rate was 4.1%. See jobs and the county spread →
How many Vermonters are behind on their bills?
No one dataset counts every unpaid bill. The Federal Reserve Bank of Philadelphia found 8.8% of Vermont card borrowers at least 90 days late in early 2025. Its collections measure found 8.6% of people with a credit record had a debt in collections. See both measures →
Cite or reuse Vermont’s data
The dated figures, maps and county list can be checked against their named producers.
State Distress Index
Vermont
48thmost distressed state
of the 50 states and D.C.
More distressed than 6% of the other states and D.C.
Vermont scores 6 on the State Distress Index and ranks 48th most distressed among the states and D.C. The Census Bureau’s 2024 poverty estimate was 9.3% statewide and 13.8% in Essex County. Essex also has Vermont’s highest County Distress Index score, 36.
Reporters can request an interview or a custom cut of the data at press@americandefault.org.
Sources and method
We gather the data, run the numbers and research each state ourselves.
This edition: October 2026 · Next edition expected March 2027
- Poverty and household incomeU.S. Census Bureau, Small Area Income and Poverty Estimates2024
- Rent, housing costs and homeownershipU.S. Census Bureau, American Community Survey2020–2024 and 2024
- PopulationU.S. Census Bureau, annual population estimatesthrough 2025
- UnemploymentU.S. Bureau of Labor Statistics, Local Area Unemployment Statisticsthrough August 2026
- Borrower lateness and collectionsFederal Reserve Bank of Philadelphia, Consumer Credit Explorerfirst quarter 2025
- Debt balances and late dollarsFederal Reserve Bank of New York, Consumer Credit Panel / Equifax2019 and 2025
- Bankruptcy filingsAdministrative Office of the U.S. Courts, 2025 table F-22025
- Personal incomeU.S. Bureau of Economic Analysis, state personal-income accounts2024
- SNAP enrollmentU.S. Department of Agriculture, Food and Nutrition Administrationthrough 2026
- Mortgage equityFederal Housing Finance Agency, National Mortgage Databasesecond quarter 2026
- Mortgage complaintsConsumer Financial Protection Bureau, public complaint databasethrough October 2026
- Housing counselorsU.S. Department of Housing and Urban Development, counseling rosterOctober 2026
- Vermont tax changesVermont Department of Taxes, 2026 legislative highlights2026
- Vermont health-coverage changesDepartment of Vermont Health Access, Medicaid changes2026–2027
- Vermont food-benefit changesVermont Department for Children and Families, 3SquaresVT news2025
- April storm and power outageNational Weather Service, Williamstown tornado reviewApril 2026
- Orleans County photoArtaxerxes / Wikimedia Commons, CC BY-SA 4.02017
The state index combines borrower lateness, collections and bankruptcy, unemployment and severe renter costs. It ranks each measure across states and D.C., averages measures within each part, then averages the four parts. Vermont’s score is the share of other places with a lower combined average. County scores use a broader local set of measures and rank counties nationwide. Full method →
We write with AI tools, and Ross Kilburn checks and reviews every page before it's published.
Get the next Vermont edition by email
One email each time a new Vermont edition is out; the next is expected in March 2027. Unsubscribe anytime.
Thanks, that helps.