Selene Finance hardship complaints: 43.8% of its mortgage record
Complaints about struggling to pay make up 43.8% of the CFPB mortgage record under Selene’s name. Selene is a specialty mortgage servicer. Its residential mortgage help number is 877-735-3637. Mail payments to the address on your current statement.

Next edition expected January 2027
Selene residential phone and designated written-request box
Selene separates residential and business-purpose calls. It also separates assistance mail from formal notices of error. American Default is independent of Selene and the government.
Selene residential customer service
877-735-3637This is Selene’s residential customer service number, including consumer mortgages and home-equity lines. Its commercial line is different.
Listed on selenefinance.com · checked Oct 23, 2026
Exclusive address for notices of error and requests for information
Selene Finance LP
ATTN: Customer Correspondence
PO Box 8279
Philadelphia, PA 19101-8279
Selene calls this the exclusive address for complaints, notices of error, information requests, qualified written requests and HELOC billing disputes.
Listed on selenefinance.com · checked Oct 23, 2026
Mortgage assistance mail
Selene Finance LP
PO Box 8619
Philadelphia, PA 19101-8619
This separate box is for general correspondence and mortgage assistance. Selene designates PO Box 8279 for formal written requests.
Listed on selenefinance.com · checked Oct 23, 2026
Selene also lists a mortgage-assistance fax on its contact page. Selene designates PO Box 8279 for notices of error and information requests.
The CFPB complaint label is “Selene Holdings LLC,” while the contact page names Selene Finance LP. The CFPB company label and the servicer named on a statement can differ.
Which Selene address matches the reason you are writing?
Selene lists PO Box 8619 in Philadelphia for general correspondence and mortgage assistance. For a suspected account error or request for loan information, its contact page names PO Box 8279 and “ATTN: Customer Correspondence” as the exclusive route.
Those boxes serve different purposes. Selene also lists a separate overnight correspondence address. The address printed on a current statement matters if your loan was transferred.
Pretium described Selene Finance as its wholly owned specialty servicer in a June 2026 impact report. The CFPB publishes complaints under the separate “Selene Holdings LLC” label.
What do people complain about under the Selene label?
For October 21, 2025, through October 20, 2026, the CFPB received 934 mortgage complaints under “Selene Holdings LLC.” The prior equal-length period had 618.
Selene describes itself as a specialty loan subservicer serving prime, subprime and special-servicing portfolios. Its higher hardship-complaint share is measured against a broad company group; these data do not show the payment status of loans when Selene took them on.
The company answered 934 recent complaints on time, or 100.0%. The same-period median was 100.0% among 32 other companies with at least 200 mortgage complaints.
Since May 1, 2017, 43.8% of Selene-label complaints concern “Struggling to pay mortgage.” The median is 23.1% among 74 other companies with at least 200 mortgage complaints. The chart compares those shares.
Payment-process problems account for 47.6% of Selene complaints, below the 50.8% peer median. Its larger hardship share is the category that sets this complaint mix apart.
Struggling to pay: 43.8% of Selene complaints, twice the typical rate
Selene Holdings LLC and the median of other companies; complaints since May 1, 2017
This company Median of other companies
Trouble during payment process
Struggling to pay mortgage
Applying for a mortgage or refinancing an existing mortgage
Closing on a mortgage
Incorrect information on your report
Problem with a company's investigation into an existing problem
How did the company close CFPB complaints?
For Selene complaints received from January 2025 through October 20, 2026, the CFPB lists 97.5% closures with an explanation, 0.0% with non-monetary relief and 0.0% with monetary relief. The middle peer shares for the two relief categories are 0.0% and 0.5%.
The closing category is Selene’s reported response.
How has the Selene complaint count changed by year?
Selene’s complaint series separates complete calendar years from the partial 2026 bar, which stops October 20. That last bar covers fewer months; the preceding bars cover January through December.
Selene: 670 in 2025, 781 through October 20, 2026
CFPB company label: Selene Holdings LLC; 2026 ends October 20
How did the latest 12 months compare with the prior 12 months?
The CFPB recorded 618 mortgage complaints under “Selene Holdings LLC” in the earlier equal-length window and 934 in the latest. The chart sets the two periods side by side.
Selene: 618 complaints before, 934 now
Equal 12-month windows ending October 20, 2026
When did Selene answer complaints late?
The CFPB’s timely-response field recorded 1 late answer to mortgage complaints under “Selene Holdings LLC” from January 2025 through October 2026. The chart shows monthly counts.
Selene: 1 late answer since January 2025
CFPB company label: Selene Holdings LLC; months through October 2026
What did the Oklahoma inspection-fee appeal decide?
An Oklahoma appellate court reviewed certification of a proposed class in Bank of America v. Still. Selene Finance LP was a third-party defendant. The proposed claims concerned property-inspection fees across 13 states (court opinion).
The court reversed class certification on a procedural state-law ground. The fee claims remained for trial-court proceedings. The opinion states no government penalty or borrower payout. The appellate mandate issued January 9, 2025.
How can you ask Selene about payment help?
Selene’s contact page lists a residential service number and a separate mortgage-assistance mail box. Its customer assistance page describes the information it seeks for a request. An available option depends on the loan and review.
A HUD-approved counselor can discuss Selene’s assistance materials and mortgage documents at no cost. Find a counselor. A lawyer can review a disputed inspection fee or a court paper for one loan.
-
Start with the residential line
Selene’s residential number is 877-735-3637. Its website asks callers to use the line for their loan type. The commercial and business-purpose line is not the consumer mortgage line.
Source: Selene contact page
-
Match your letter to its box
Selene prints PO Box 8619 for assistance papers and PO Box 8279 for a notice of error or information request. The company prints a separate fax for assistance and designates PO Box 8279 for formal written requests.
Source: Selene contact page
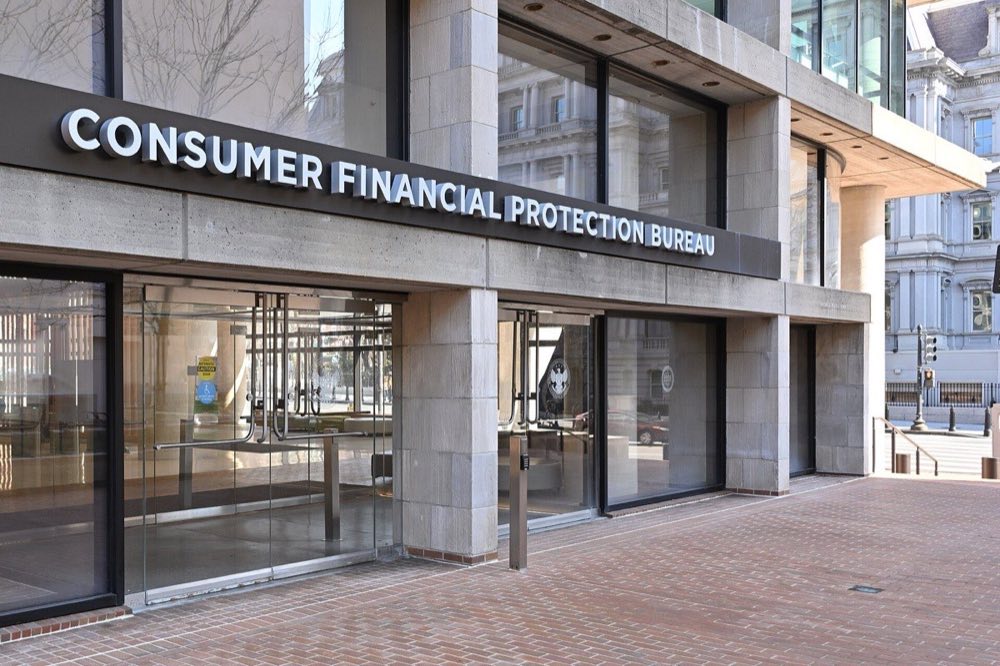
Entrance to the Consumer Financial Protection Bureau in Washington, D.C. CFPB contact page

Where can you complain about Selene?
The CFPB complaint form sends a mortgage complaint to the company for a response. A complaint is a record of the problem and the company’s reply.
Your state banking or mortgage regulator is another complaint route. The CFPB lists state regulators and complaint instructions. For help reviewing options, HUD’s local counselor search finds agencies by ZIP code or state, or call 800-569-4287.
Selene record: a HUD audit and a court ruling
A HUD audit of 14 FHA loans and an Oklahoma class-certification appeal address different questions.
-
May 16, 2024
Oklahoma Court of Civil Appeals Appellate ruling in Bank of America v. Still, No. 121129
The court reversed certification of a proposed multistate inspection-fee class. Its decision was on a procedural state-law ground, not a final ruling on the fee claims.
Admitted wrongdoing? No admission; the allegations were contested.
No state penalty or borrower restitution stated in the opinion.
Status: The appellate mandate issued January 9, 2025. · Oklahoma appellate opinion
-
Jul 28, 2016
HUD Office of Inspector General Audit report, not an enforcement order
HUD OIG reviewed 14 delinquent FHA loans. It reported that Selene did not communicate in a timely manner on seven and made repeated collection calls to one borrower under bankruptcy protection. It said Selene otherwise generally complied with the servicing requirements it reviewed.
Admitted wrongdoing? An audit finding, not a company admission or court judgment.
No penalty or borrower payment in the audit report.
Status: HUD OIG issued Audit Report 2016-FW-1005 on July 28, 2016. · HUD OIG 2016 Selene audit
What the federal rules say about account questions
Federal deadlines have exceptions; a counselor or lawyer can apply them to a particular loan.
- 1
An error notice can ask the company to investigate
A borrower can mail a notice of error to a designated address. Federal rules require acknowledgment within five business days and a response within 30 business days.
Source: CFPB notice-of-error rule
- 2
A loan-record request follows a related rule
A written request for information receives a response within 30 business days. A request for the loan owner’s identity usually has a shorter deadline.
Source: CFPB information-request rule
Get the next edition of this page by email
One email when the next edition is out, expected in January 2027. Unsubscribe anytime.
Thanks, that helps.
Questions about Selene Finance LP
What is Selene Finance’s residential mortgage number?
Selene lists 877-735-3637 as its residential service line on its contact page.
Where does Selene accept a notice of error?
Selene’s contact page names Selene Finance LP, ATTN: Customer Correspondence, PO Box 8279, Philadelphia, PA 19101-8279.
Is the mortgage-assistance address the same box?
No. Selene lists PO Box 8619 for general correspondence and mortgage assistance. The designated written-request box is PO Box 8279.
Did the Oklahoma court decide Selene’s fee claims were false?
No. The appellate opinion reversed class certification on a procedural ground. It did not decide each borrower’s fee claim.
Protect yourself from scams
The FTC and CFPB describe these warning signs and the rules behind them:
- Upfront fees for promised relief are a warning sign. Under FTC mortgage-assistance rules, most companies that sell mortgage help cannot charge until a homeowner accepts a written offer from the mortgage company or lender. A separate FTC rule covers debt-relief companies that sell by phone and ties fees to a completed debt arrangement. It bars a fee until at least one debt has been settled or changed, the customer agrees to the arrangement, and the customer has made a payment under it. The FTC describes a narrow exception for lawyers who give help as part of the practice of law and are licensed in the state where the client or dwelling is. The lawyer follows that state's rules for attorneys, and advance fees are placed in a client trust account before services begin under state trust-account rules.
- HUD-approved foreclosure-prevention counseling is free. HUD’s national counselor line is 800-569-4287. The CFPB counselor finder lists agencies and their services. If an organization charges for help described as free HUD counseling, the CFPB finder can verify the agency and its listed services before any payment.
- A request to sign over a deed is a warning sign. The CFPB identifies title-transfer schemes among foreclosure-relief scams. Signing over title can mean losing ownership of the home; a lawyer can explain what a proposed document would do.
- Foreclosure protections depend on timing and the loan. Regulation X generally bars the first foreclosure notice or filing on a principal-residence loan until the borrower is more than 120 days behind, subject to exceptions. A complete assistance application can delay some foreclosure steps, but that depends on when it arrives; it does not necessarily stop every step. The CFPB warns about promises to “save” a home.
Free help if you're behind
Housing counselors approved by the U.S. Department of Housing and Urban Development work at nonprofit agencies. The Consumer Financial Protection Bureau describes free foreclosure-avoidance counseling, including help with mortgage-company conversations and available options Source CFPB.
-
HUD-approved housing counselors
Our help directory lists 1,010 agencies approved for foreclosure counseling, by state.
-
Legal aid
Nonprofit law offices give free civil legal help to people with low incomes. Our help directory lists the 120 offices the Legal Services Corporation funds.
Every figure on this page, with its period and the CFPB filter behind it, in one file. Free to use with credit to American Default Research.
Sources and method
We gather the data, run the numbers and research each company ourselves. The CFPB publishes complaints without verifying each account. The counts and issue shares use complaints filed under “Selene Holdings LLC” during the dates shown. Each comparison takes the middle share among other mortgage companies with at least 200 complaints in the same period. Updated: October 2026 · Next review expected: January 2027.
- Consumer Financial Protection Bureau, Consumer Complaint Database Mortgage complaints about the company, received through Oct 20, 2026. Our counts from the CFPB's complaint records.
- Residential line and distinct mail boxes
- Customer assistance process
- Inspection-fee class ruling
- Selene ownership description
- State regulator complaint directory
- Local housing counseling agencies
- 2016 Selene servicing audit
- Selene servicing business
We write with assistance from AI tools. Figures come from the data and sources named on this page.