New Jersey’s typical household income ranked 3rd highest at $104,202, yet its distress score was 56
Each state is shaded by how distressed its households are, from green (least) to red (most), with data through September 2026. New Jersey scores 56 out of 100.
New Jersey’s typical household income was $104,202 in 2024, 3rd highest nationally, yet its State Distress Index score was 56. Typical rent was $1,720 a month, about a fifth above the national figure. Its jobless rate has exceeded the nation’s since late 2022, although fewer residents are behind on debts than Americans overall. Cumberland and Essex carry New Jersey’s heaviest county distress. Morris and Hunterdon sit at the low end.
- Score
- 56/100
- Data through
- September 2026
- Edition
- October 2026
Next edition expected March 2027
How New Jersey ranks among the states
New Jersey is the 23rd most distressed of the 50 states and D.C., a middle place for a state whose typical household income in 2024, $104,202, was the 3rd highest in the country (is New Jersey rich?). Its people aren’t falling behind more than most. In early 2025, 14.5% of New Jerseyans with a credit record had a debt 90 or more days late, against 17.2% nationwide (Federal Reserve Bank of Philadelphia; the U.S. share is our population-weighted average of the states). What raises the score is housing costs and the jobless rate, though the jobless rate counts for less than it did in early 2025. Homeowners’ costs, which the score doesn’t count, stand out too: 28.4% of homeowners spent at least 30% of their income on housing in 2020 to 2024, the 3rd highest share of any state (U.S. Census Bureau). Unemployment averaged 5.2% in 2025, tied for 4th highest among the states, before falling through 2026 (U.S. Bureau of Labor Statistics).
What drives the score
Every measure gets a score from 0 to 100 for where New Jersey falls among the states, and each part averages its measures. New Jersey’s four parts average 59. Of the other 49 states and D.C., 28 average lower, 56% of them, and that share is the score: a state that scores 80 is more distressed than 80% of states. So the score isn’t the average of the parts.
- Renters’ housing costs81In 2024, 26.1% of New Jersey renter households spent half or more of their income on rent and utilities, 13th highest among the states and, rounded, the same as the U.S. figure of 26.1%.
- Jobs65The jobless rate for June to August 2026 averaged 4.4%; the U.S. rate was 4.1%. In early 2025, when the rate was higher, this part stood at 91.
- Late payments48In early 2025, New Jersey borrowers were less likely than borrowers nationwide to be 90 or more days behind on credit cards or car loans, and just as likely on mortgages.
- Collections and bankruptcy43A smaller share of New Jerseyans than of all Americans had a debt in collections in early 2025, and the state had 148.4 bankruptcy filings per 100,000 residents in 2025 (2025 population), against 166.3 nationwide.
Beside its neighbors
New York and Delaware, which faces New Jersey across the Delaware River and Bay, both score higher than New Jersey. Pennsylvania scores lower.
State Distress Index score, 0 to 100. Income doesn’t explain the order: New Jersey’s typical household earned more in 2024 than those of all three neighbors, New York’s $85,768, Delaware’s $87,510 and Pennsylvania’s $77,532 (Census Bureau, Small Area Income and Poverty Estimates).
New Jersey’s score rises and falls with its jobless rate
Worst during the pandemic
New Jersey was most distressed in the second and third quarters of 2020 and the first half of 2021, scoring 86 and ranking 8th among the states each time. Jobs drove it: unemployment averaged 9.5% in 2020, against 8.1% nationwide, and the jobs part reached 95 in the summer of 2020. Its least distressed quarters since the record for all four parts begins, in mid-2006, were the first two of 2007, when it scored 40 and ranked 31st.
Up and down with jobs
From late 2011 to early 2025, New Jersey ranked anywhere from 8th to 24th most distressed. Its two lowest points in that stretch, a score of 58 in the first half of 2019 and 54, 24th, in the third quarter of 2022, came when the jobs part fell, to 38 and 48. Housing moved it too: in the third quarter of 2024, a new Census Bureau estimate lowered the renters’ part from 85 to 75.
Early 2025 to today
Where the chart stops, in the first quarter of 2025, New Jersey scored 72, 15th among the states. Today it scores 56 and ranks 23rd. Only the jobs part changed, dropping from 91 to 65 as unemployment came down from its 2025 high (see jobs). Set against the end of 2019, when it scored 82 and ranked 10th, the renters’ part is down from 91 to 81, late payments from 59 to 48, and collections and bankruptcy from 50 to 43. Those parts compare New Jersey with other states, so their fall is a fall in rank. It does not mean fewer people were behind. New Jersey’s own share of people seriously behind on a debt rose over the same years (see behind on bills).
New Jersey went from 31st most distressed in 2007 to 8th in 2020 and 2021, then eased to 15th by early 2025
New Jersey’s State Distress Index score, 0 to 100, in each quarter from mid-2006, when all four parts begin, to the first quarter of 2025.
New Jersey’s unemployment rate fell more than any other state’s this past year
New Jersey’s unemployment rate was 4.3% in August 2026, down from 5.5% a year earlier, the largest drop of any state, the U.S. Bureau of Labor Statistics reported. That left New Jersey tied for 16th highest among the 50 states and D.C. The U.S. rate was 4.1%, and BLS found no significant difference between the two. The fall followed a long climb: the yearly average rose every year from 3.9% in 2022 to 5.2% in 2025, and the monthly rate reached 5.5% from July to September 2025.
Unemployment rate
4.3%
U.S. 4.1%
Tied for 16th highest among the states, August 2026
A year earlier
5.5%
August 2025
Yearly average
5.2%
U.S. 4.3%
Tied for 4th highest among the states, 2025
New Jersey’s jobless rate ran above the U.S. rate from late 2022, peaked at 5.5% in mid-2025 and has fallen every month this year
Unemployment rate each month, seasonally adjusted, for New Jersey and the U.S., from January 1990 through August 2026. There is no October 2025 figure: the federal shutdown stopped that month’s survey.
Unemployment is highest in Cumberland County
| County | Rate |
|---|---|
| Cumberland | 7.4% |
| Salem | 6.1% |
| Essex | 5.7% |
| Cape May | 5.5% |
| Passaic | 5.5% |
| Bergen | 4.0% |
| Morris | 3.9% |
| Hunterdon | 3.7% |
Unemployment rate, August 2026, not adjusted for seasonal swings: the five highest of New Jersey’s 21 counties (Cape May and Passaic tie), Bergen, the most populous, and the two lowest. Cumberland’s rate was tied for 36th highest of 3,143 U.S. counties. Source: U.S. Bureau of Labor Statistics.
Is New Jersey a rich state?
By income, yes. The typical New Jersey household earned $104,202 in 2024, the 3rd highest of the 50 states and D.C., against $81,604 nationally. Its poverty rate, 9.2%, was tied for 3rd lowest, against 12.1% nationwide (U.S. Census Bureau, Small Area Income and Poverty Estimates). Counted per resident, income came to $84,893 in 2024, 8th highest among the states (U.S. Bureau of Economic Analysis).
The gap inside the state is wide: Morris County’s typical household earned $137,213 in 2024, about twice Cumberland County’s $66,986 (see the counties).
New Jersey’s poverty rate has stayed below the U.S. rate in every year of our data since 1989; its highest was 11.4%, in 2013
Poverty rate, New Jersey and the U.S., 1989 to 2024; our file skips 1990 to 1992, 1994 and 1996.
Layoff notices are running ahead of last year
Employers filed 115 notices of planned layoffs or closings with New Jersey’s labor department from January to early October 2026, by our count of its log, against 113 in all of 2025 (2026 notices; 2025 notices). A notice is a plan, not a confirmed job loss, and BLS found no significant change in the state’s payroll jobs from August 2025 to August 2026.
File for unemployment benefits through New Jersey’s labor department. The state minimum wage for most workers is $15.92 an hour in 2026 and is set to reach $16.48 on Jan. 1, 2027 (New Jersey labor department). Unemployment in every state →
New Jersey’s poorest and most distressed counties
Hudson County, home to Jersey City, has New Jersey’s highest poverty rate: 14.7% of its residents lived below the poverty line in 2024 (Census Bureau, Small Area Income and Poverty Estimates). On our County Distress Index, which scores household financial strain in every U.S. county, the most distressed is Cumberland County in South Jersey, home to Bridgeton and Vineland, at 92, followed by Essex County, home to Newark, at 82. Morris County, in the north, is the least distressed and has the state’s highest typical household income, $137,213 in 2024. No New Jersey county is among the 100 most or the 100 least distressed in the country.
Six counties score 70 or more, from Cumberland and Salem in the south to Essex and Passaic in the north; they hold 25.7% of New Jerseyans
Each of New Jersey’s 21 counties is shaded by its County Distress Index score, 0 to 100, with data through August 2026.
Loading the county map…
The county map could not be loaded. Every county is in the lists on this page.
Most distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 1 | Cumberland | 92 | 14.2% |
| 2 | Essex | 82 | 13.4% |
| 3 | Salem | 78 | 12.4% |
| 4 | Atlantic | 77 | 11.1% |
| 5 | Passaic | 72 | 12.1% |
| 6 | Camden | 70 | 11.4% |
| 7 | Hudson | 61 | 14.7% |
| 8 | Union | 56 | 9.7% |
| 9 | Mercer | 50 | 10.0% |
| 10 | Ocean | 44 | 9.1% |
Least distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 17 | Bergen | 25 | 6.7% |
| 18 | Monmouth | 23 | 6.9% |
| 19 | Somerset | 18 | 5.8% |
| 20 | Hunterdon | 11 | 4.5% |
| 21 | Morris | 7 | 4.7% |
Rank in New Jersey, 1 = most distressed. Ranks use unrounded scores. Poverty is the Census Bureau’s 2024 estimate of the share of residents below the poverty line.
Every county, by score
The six counties scoring 70 or more hold 2,384,585 people. Cumberland has the highest score, but it is a county of 152,326; Essex, the other county scoring 80 or more, has 851,117 residents. At the other end, six counties score under 30, from Sussex in the northwest to Monmouth on the shore, and they are home to 29.5% of New Jerseyans. Population counts here are the Census Bureau’s 2023 estimates, the ones our county index uses.
2 score 80–100
6 score 30–49
Hudson County has the highest poverty rate but isn’t the most distressed
Poverty is one of five equal parts of our county score. The others count borrowers behind on payments, debts in collections and bankruptcies, joblessness (the unemployment rate and adults aged 25 to 54 without work) and renters’ housing costs. The poverty part also weighs child poverty, income, disability and health coverage. Hudson County has the state’s highest poverty rate, 14.7%, yet ranks 7th most distressed; its jobs part, 46, is the lowest of the seven most distressed counties. Atlantic County, home to Atlantic City, goes the other way: its poverty rate is 7th highest in the state. But it ranks 4th on distress, with renters’ costs second only to Passaic’s in New Jersey and 5.4% of its labor force out of work in August 2026. Ocean County, 11th highest on poverty, ranks 10th, with renters’ costs among the highest in the state. Counted in people rather than shares, Essex and Hudson stand out: 115,332 Essex County residents and 107,427 in Hudson lived below the poverty line in 2024, against 20,754 in Cumberland (Census Bureau). Lists that name a different poorest county may use another Census survey or year.
The five poorest
| County | Poverty | Distress rank |
|---|---|---|
| Hudson | 14.7% | 7th |
| Cumberland | 14.2% | 1st |
| Essex | 13.4% | 2nd |
| Salem | 12.4% | 3rd |
| Passaic | 12.1% | 5th |
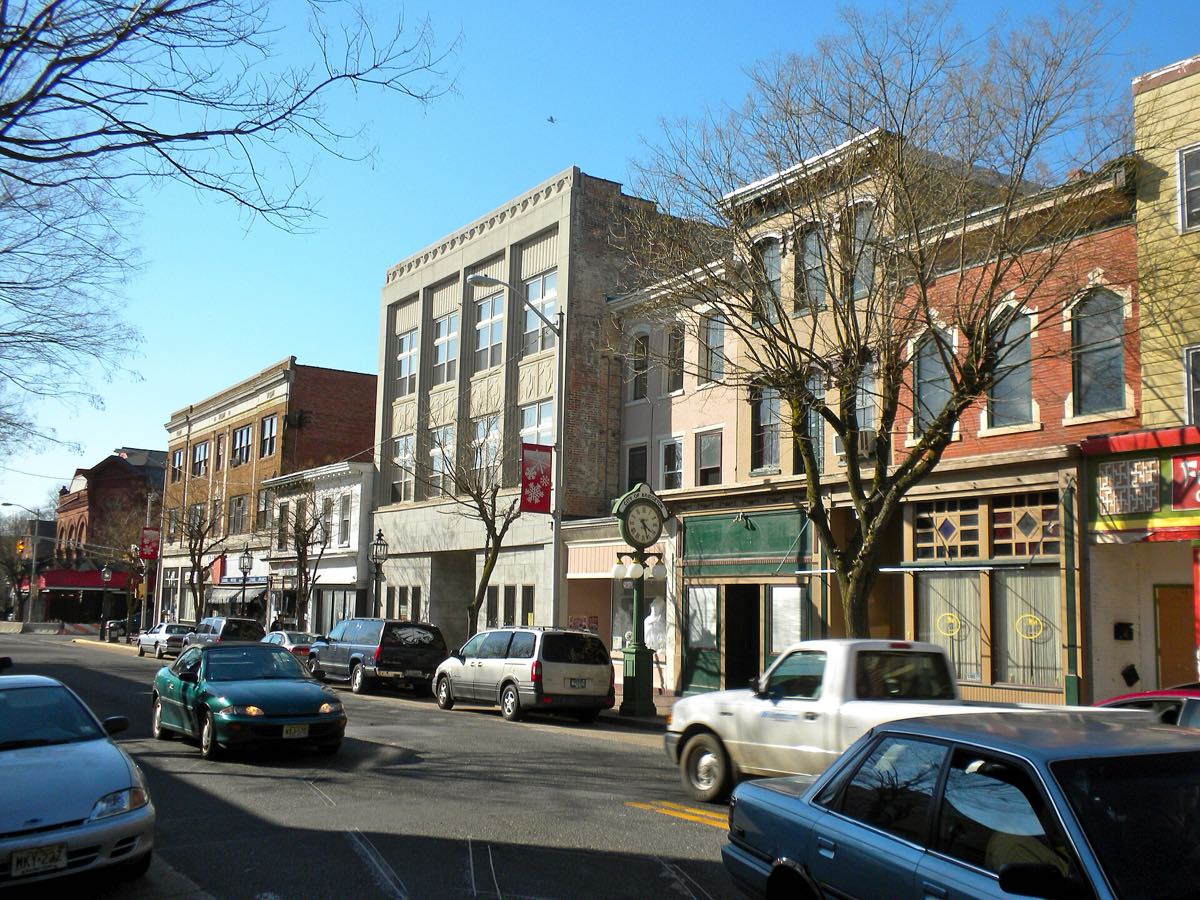
Commerce Street in Bridgeton, the Cumberland County seat, in March 2010. Cumberland scores 92 on our County Distress Index, the highest of New Jersey’s 21 counties, and its typical household earned $66,986 in 2024, the lowest in the state (U.S. Census Bureau).
Source: U.S. Census Bureau. Photo: Smallbones, via Wikimedia Commons, public domain.

South Jersey has four of the six most distressed counties
Cumberland, Salem, Atlantic and Camden counties, from the Delaware Bay to Atlantic City and the Philadelphia suburbs, are four of the six counties scoring 70 or more; Essex and Passaic, in the north, are the other two. In August 2026, 7.4% of Cumberland’s labor force and 6.1% of Salem’s were out of work, the two highest county rates in the state, not adjusted for seasonal swings (U.S. Bureau of Labor Statistics). None of the housing counselors HUD lists for New Jersey is based in Cumberland or Salem (see free help).
American Default Research, County Distress Index; U.S. Bureau of Labor Statistics; U.S. Department of Housing and Urban Development.
Is New Jersey expensive to live in?
For housing, yes. The typical rent in New Jersey was $1,720 a month across 2020 to 2024, 7th highest among the 50 states and D.C., against $1,413 for the U.S. (U.S. Census Bureau). Owners carry heavy costs too: 28.4% of homeowners spent at least 30% of their income on housing over those years, against 22.5% nationwide. Because incomes are high, a year of median rent equals 19.8% of the typical household’s income, a little less than the U.S. figure of 20.8% (our calculation). We don’t measure what food, fuel, electricity or property taxes cost, so we can’t rank the whole cost of living.
Median rent, a month
$1,720
U.S. $1,413
7th highest among the states, 2020 to 2024
Homeowners spending at least 30% of income on housing
28.4%
U.S. 22.5%
3rd highest among the states, 2020 to 2024
Basic yearly budget, one adult
$56,884
5th highest of the 50 states and D.C. (MIT Living Wage Calculator, 2025 dollars)
The share of New Jersey renters paying half their income for housing peaked at 29.6% in 2011 and by 2024 had come down to the U.S. share
Renter households spending half or more of their income on rent and utilities, New Jersey and the U.S., each year from 2005 to 2024. The gap at 2020 is a year without standard one-year Census estimates.
What a basic New Jersey budget costs
The MIT Living Wage Calculator puts the yearly cost of basic needs for one adult with no children in New Jersey at $56,884 before taxes, 5th highest among the states, and for two working parents with two children at $147,567. Its budgets cover necessities only.
Most adults polled feel the squeeze. In a Rutgers-Eagleton Poll taken in late September 2026, 32% of New Jersey adults said housing costs were very difficult to afford and 33% said somewhat difficult (Rutgers University, Oct. 7, 2026).
Property taxes and electric bills
We don’t hold property tax data. The state budget signed June 30, 2026, sets aside $2.19 billion for ANCHOR property tax relief and $756 million for Stay NJ, which pays qualifying seniors part of their property tax bill (Office of Governor Mikie Sherrill). New electricity supply prices took effect on June 1, 2026: for an average home before credits, the New Jersey Board of Public Utilities’ figures showed PSE&G bills falling 1.8% and JCP&L bills rising 1.6%. The board also ordered a one-time $25 credit for August (see what changed).
Rent takes a bigger share of income in New York than in New Jersey
New York’s typical rent takes a larger share of a typical income than New Jersey’s does; in Delaware and Pennsylvania the share is smaller. We don’t measure other prices.
| Place | Rent, a month | Typical household income | Rent as share of income |
|---|---|---|---|
| New York Rent as share of income 22.7% | $1,621 Typical household income $85,768 | $85,768 | 22.7% |
| New Jersey Rent as share of income 19.8% | $1,720 Typical household income $104,202 | $104,202 | 19.8% |
| Delaware Rent as share of income 19.2% | $1,401 Typical household income $87,510 | $87,510 | 19.2% |
| Pennsylvania Rent as share of income 18.7% | $1,209 Typical household income $77,532 | $77,532 | 18.7% |
Twelve months of the Census Bureau’s median gross rent for 2020 to 2024, divided by its 2024 median household income estimate (our calculation). Rent and housing costs in every state →
Are people leaving New Jersey?
More people move from New Jersey to other states than move in, but more arrive from abroad, so the population is still growing. In each year from July 2020 to July 2025, New Jersey lost more people to other states than it gained from them, 211,131 on balance over the five years, and only three states lost more. Over the same years, 378,925 more people arrived from other countries than left, and births outnumbered deaths by 110,548. The population grew 3.0%, to 9,548,215 in 2025, tied for 21st highest among the 50 states and D.C. and close to the U.S. figure of 3.1% (U.S. Census Bureau, population estimates). These estimates count moves, not the reasons for them, and we don’t measure why people go.
| Year to July | Net moves out to other states | Net arrivals from abroad | Births minus deaths | Change in population |
|---|---|---|---|---|
| 2021 Births minus deaths 13,857 · Change in population −3,967 | 34,314 Net arrivals from abroad 14,747 | 14,747 | 13,857 | −3,967 |
| 2022 Births minus deaths 19,840 · Change in population 31,893 | 62,174 Net arrivals from abroad 76,031 | 76,031 | 19,840 | 31,893 |
| 2023 Births minus deaths 25,234 · Change in population 96,913 | 41,714 Net arrivals from abroad 114,014 | 114,014 | 25,234 | 96,913 |
| 2024 Births minus deaths 25,594 · Change in population 111,039 | 35,501 Net arrivals from abroad 121,069 | 121,069 | 25,594 | 111,039 |
| 2025 Births minus deaths 26,023 · Change in population 41,861 | 37,428 Net arrivals from abroad 53,064 | 53,064 | 26,023 | 41,861 |
Census Bureau 2025 population estimates; each year runs from July to July. The change in population also includes a small adjustment the Census Bureau can’t assign to births, deaths or moves, so the other columns don’t add up to it exactly. The population shrank only in the year to July 2021. Where distress is heaviest in New Jersey →
How many New Jerseyans are seriously behind on their debts?
Fewer than in most states. In early 2025, 14.5% of New Jerseyans with a credit record had a debt 90 or more days late, 22nd lowest among the 50 states and D.C., against 17.2% across the U.S. (Federal Reserve Bank of Philadelphia). Our national figure averages the states by population. That share is up from 13.2% at the end of 2019, though New Jersey held the same place among the states.
Rank among the 50 states and D.C. (1 = highest): credit cards 31st highest, car loans tied for 29th highest, mortgages tied for 20th highest, collections 13th lowest. For the U.S. bars we averaged the states, giving bigger states more weight.
The share of New Jerseyans with a debt in collections fell from 15.9% at the end of 2019 to 9.4% in early 2025. But that doesn’t mean those debts were paid. Most of the drop came between early 2022 and mid-2023, from 12.8% to 8.6%, while the three big credit bureaus were taking many medical debts off credit reports. Across the U.S., the share of people with a medical collection on their report went from about 14% in March 2022 to about 5% in June 2023 (Consumer Financial Protection Bureau, April 2024). New Jersey’s share has crept up since the second half of 2023.
Credit card balances are among the highest in the country
In dollars, New Jerseyans carry more debt than most Americans. At the end of 2025, credit card balances came to $5,160 per person with a credit report, 4th highest among the 50 states and D.C. The national figure was $4,350. All household debt came to $69,550 per person, 13th highest (Federal Reserve Bank of New York). The New York Fed counts dollars rather than borrowers. At the end of 2025, 1.1% of New Jersey’s mortgage dollars were 90 or more days late, tied for 12th highest among states and above 0.9% nationally. That was down from 1.7% at the end of 2019.
| Loan type | New Jersey | U.S. | New Jersey 2019 | U.S. 2019 |
|---|---|---|---|---|
| Credit card | 11.4% End of 2025 U.S. 12.4% New Jersey 2019 7.5% · U.S. 2019 8.1% | 12.4% | 7.5% | 8.1% |
| Auto loan | 4.2% End of 2025 U.S. 5.2% New Jersey 2019 3.9% · U.S. 2019 4.9% | 5.2% | 3.9% | 4.9% |
| Mortgage | 1.1% End of 2025 U.S. 0.9% New Jersey 2019 1.7% · U.S. 2019 1.0% | 0.9% | 1.7% | 1.0% |
Share of loan balances 90 or more days late at the end of 2025 and the end of 2019 (Federal Reserve Bank of New York, Consumer Credit Panel / Equifax). This counts dollars rather than people, so it can’t be set beside the Philadelphia Fed shares above, and it keeps counting debts that lenders have written off but still report.
Few New Jersey mortgages are close to underwater
In the second quarter of 2026, 1.4% of New Jersey mortgages had less than 10% equity, 3rd lowest among the states, against 4.7% nationwide (Federal Housing Finance Agency). On those loans, the amount owed is close to the home’s value or above it.
| Measure | New Jersey | U.S. | Rank |
|---|---|---|---|
| Home loans with less than 10% equity, April to June 2026 3rd lowest | 1.4% U.S. 4.7% | 4.7% | 3rd lowest |
| Mortgages 30 to 89 days late, Sept. 2025 Tied for 25th highest | 1.6% U.S. 1.6% | 1.6% | Tied for 25th highest |
Rank among the 50 states and D.C. Equity: Federal Housing Finance Agency. Payments 30 to 89 days late, an early stage of falling behind: Consumer Financial Protection Bureau. Late payments in every state →
How many New Jerseyans receive SNAP food help?
In June 2026, 754,543 New Jerseyans received SNAP benefits, the food help once called food stamps. That is 7.9% of residents, counted against the 2025 population, 15th lowest among the 50 states and D.C.; nationwide the share was 10.6% (U.S. Department of Agriculture). That was 8.1% fewer people than in June 2025, when 821,038 got benefits. The SNAP share is below the state’s 2024 poverty rate of 9.2%, though the two count different things.
People getting SNAP
754,543
June 2026, U.S. Department of Agriculture
Share of residents getting SNAP
7.9%
U.S. 10.6%
15th lowest among the states, June 2026 (2025 population)
Change from a year earlier
−8.1%
June 2025 to June 2026
About half of the year’s fall came before New Jersey’s waiver from SNAP’s time limit ended in most of the state on Feb. 1, 2026. The count dropped by 34,180 from June 2025 to January 2026 and by 32,315 from January to June 2026 (U.S. Department of Agriculture). The biggest one-month drop of the year came in June 2026, 18,627 people. We found no source that explains it.
The work rule now reaches more New Jerseyans
The 2025 federal law raised the top age for SNAP’s work rule from 54 to 64 and narrowed the exemption for parents to those with a child under 14. Adults the rule covers can get benefits for only 3 months in 3 years unless they meet the work requirement or are exempt (New Jersey Department of Human Services). Through Jan. 31, 2026, a waiver covered every county but Morris; since Feb. 1, only Camden City and Cape May County have one, so the 3-month limit could first end benefits around May 2026, by our reading of the rule. For applications received from April 10, 2026, fewer groups of noncitizens qualify.
A smaller SNAP count isn’t proof of less need. The Census Bureau’s latest poverty figure for New Jersey, 9.2%, is for 2024, before these rule changes took hold (see Is New Jersey a rich state?).
Apply for SNAP at NJSNAP, the state’s SNAP site →
New Jersey’s bankruptcy filings are up four years running
New Jersey filers brought 14,171 bankruptcy cases in 2025, up 7.4% from 2024 and the most since 2020 (Administrative Office of the U.S. Courts). Filings have climbed each year since a low of 10,446 in 2021, and 14,843 were filed in the 12 months to June 2026. They are still well below the years before the pandemic: 2025’s total was 43% under 2019’s 24,810. Per resident, New Jersey had 148.4 filings for every 100,000 people in 2025 (2025 population), 24th highest among the 50 states and D.C., against 166.3 nationwide, and its filings grew more slowly than the nation’s 11.1%.
Just over a third of New Jersey’s 2025 cases, 36.2%, were filed under Chapter 13, in which the filer pays back part of what they owe through a court-approved plan, a little above the U.S. share of 35.9%. Most of the rest were Chapter 7 cases, which can wipe out many debts.
| Year | Filings |
|---|---|
| 2005 | 49,597 |
| 2010 | 41,365 |
| 2019 | 24,810 |
| 2020 | 14,728 |
| 2021 | 10,446 |
| 2022 | 10,661 |
| 2023 | 12,357 |
| 2024 | 13,199 |
| 2025 | 14,171 |
| July 2025 to June 2026 | 14,843 |
Cases under every chapter in the U.S. Bankruptcy Court for the District of New Jersey, by calendar year, plus the latest 12 months published. Of the years in our file, 2001 to 2025 with 2004 missing, 2005 had the most. Source: Administrative Office of the U.S. Courts, Table F-2. Bankruptcy filings across the states →
What changed in New Jersey over the past year
-
Sept. 18, 2026
Unemployment falls more than in any other state
The U.S. Bureau of Labor Statistics reported that New Jersey’s unemployment rate fell from 5.5% in August 2025 to 4.3% in August 2026, the largest decrease of any state over the year. The same release didn’t list New Jersey among the states with a significant change in payroll jobs (see jobs).
U.S. Bureau of Labor Statistics, State Employment and Unemployment, August 2026, Sept. 18, 2026
-
June 30, 2026
Regulators order a one-time electric bill credit
The New Jersey Board of Public Utilities ordered a single $25 credit in August 2026 on every home account with the state’s four electric utilities, paid for with $170.8 million from solar compliance payments and clean energy program funds. The order follows the bill reductions and credits the board ordered in 2025.
New Jersey Board of Public Utilities, Order, Docket QO26030089, June 30, 2026
-
June 30, 2026
The new state budget funds property tax relief
Gov. Mikie Sherrill signed a $60.7 billion budget for the fiscal year that began July 1, 2026. It includes $2.19 billion for ANCHOR property tax relief and $756 million for Stay NJ, which her office said was redesigned so that seniors with middle and lower incomes get the largest benefits.
-
Feb. 12, 2026
Electricity supply prices for the year from June are set
The New Jersey Board of Public Utilities certified the state’s yearly electricity supply auction, which set prices for a year starting June 1, 2026. For an average home before credits, the board’s figures showed PSE&G bills falling 1.8% and JCP&L bills rising 1.6%. The release noted that Gov. Sherrill had declared a state of emergency on utility costs when she took office on Jan. 20, 2026.
-
Feb. 1, 2026
The SNAP work-rule waiver ends in most of the state
A waiver that had spared adults in every county but Morris from SNAP’s time limit ended; only Camden City and Cape May County still have one. Adults the work rule covers can now get benefits for only 3 months in 3 years unless they meet the rule or are exempt (see SNAP).
New Jersey Department of Human Services, Federal Changes to SNAP
-
Oct. 30, 2025
Food banks get state money ahead of a SNAP gap
With the federal shutdown putting November SNAP benefits in doubt, Gov. Phil Murphy and the leaders of the Legislature sped up $42.5 million in state food and hunger grants to food banks.
How foreclosure works in New Jersey
Every New Jersey foreclosure goes through the courts: the lender files a case in the Superior Court, Chancery Division, and the courts’ Office of Foreclosure handles cases nobody contests. At least 30 days before filing, the lender must send a notice of intention to foreclose (N.J.S.A. 2A:50-56). Once you’re served, you have 35 days to answer the complaint, and you can ask for foreclosure mediation within 60 days; you pay no fee, and you take part with a counselor from a HUD-approved housing counseling agency (N.J.S.A. 2A:50-77). You can catch up on what’s past due, with costs and fees, and keep the loan in place up to the final judgment (N.J.S.A. 2A:50-57). The sheriff must hold the sale within 150 days of receiving the court’s writ (N.J.S.A. 2A:50-64). For 10 days after the sale, or until the deed is delivered, you can still pay off the judgment and redeem the home (court rule 4:65-5). If the sale leaves a balance, the lender has 3 months to sue for it (N.J.S.A. 2A:50-2). Federal rules generally bar a mortgage company from making the first foreclosure filing before a loan is more than 120 days behind.
- Goes through a court
- Yes
- Notice before the case is filed
- 30 days
- Time to answer the complaint
- 35 days
- Foreclosure mediation
- Free, on request
- Catch up and keep the loan
- Until judgment
- Sheriff’s sale after the writ
- Within 150 days
- Redeem after the sale
- 10 days
- Time to sue for the leftover balance
- 3 months
What the law says for a home you live in. Sources: N.J.S.A. 2A:50-2, 2A:50-56, 2A:50-57, 2A:50-64 and 2A:50-77; New Jersey Court Rule 4:65-5; the New Jersey Courts’ foreclosure help page; federal rule 12 CFR 1024.41. How foreclosure works in New Jersey →
The federal Homeowner Assistance Fund gave New Jersey $326.0 million for pandemic-era housing help, and 8,159 households had been helped through early 2026, U.S. Treasury figures show. The state’s program no longer takes applications (New Jersey Housing and Mortgage Finance Agency).
What New Jersey homeowners complain about to the CFPB
The Consumer Financial Protection Bureau has received 20,316 mortgage complaints from New Jersey since 2012. The most common issue is loan modification, collection or foreclosure (5,212), ahead of trouble during the payment process (4,677) and loan servicing, payments or escrow (3,744).
- Oct. 9, 2026 Navy Federal Credit Union Trouble during payment process: Payment process In progress
- Oct. 4, 2026 Carrington Mortgage Struggling to pay mortgage: Trying to communicate with the company to fix an issue related to modification, forbearance, short sale, deed-in-lieu, bankruptcy, or foreclosure In progress
- Oct. 2, 2026 PennyMac Trouble during payment process: Trying to communicate with the company to fix an issue while managing or servicing your loan Closed with explanation
- Oct. 1, 2026 FCI Lender Services Inc. Trouble during payment process: Paying off the loan Closed with explanation
- Sept. 30, 2026 Ocwen / Onity Group Struggling to pay mortgage: Trying to communicate with the company to fix an issue related to modification, forbearance, short sale, deed-in-lieu, bankruptcy, or foreclosure In progress
- Sept. 30, 2026 Rocket Mortgage Trouble during payment process: Escrow, taxes, or insurance Closed with explanation
- Sept. 30, 2026 Dollar Mutual Bancorp Trouble during payment process: Payment process Closed with explanation
- Sept. 30, 2026 JPMorgan Chase Trouble during payment process: Trying to communicate with the company to fix an issue while managing or servicing your loan Closed with explanation
- Sept. 28, 2026 Shellpoint / NewRez Struggling to pay mortgage: An existing modification, forbearance plan, short sale, or other loss mitigation relief In progress
- Sept. 28, 2026 Shellpoint / NewRez Struggling to pay mortgage: Foreclosure In progress
The ten most recent New Jersey complaints about paying a mortgage or getting help with one, newest first, as the Consumer Financial Protection Bureau’s public database listed them on Oct. 14, 2026. Complaints about taking out or closing on a loan, about credit reports and about a company’s handling of an earlier problem are left out. Each complaint tells one person’s side; the bureau doesn’t check it, and filing one doesn’t mean the company did anything wrong. All New Jersey mortgage complaints at the CFPB →
What to watch before the next edition
Two dates before the next edition, nearest first: a release that feeds one of the score’s two highest parts for New Jersey, and a higher minimum wage.
-
Oct. 20, 2026
September unemployment rates for every state
The U.S. Bureau of Labor Statistics is scheduled to publish the states’ September 2026 unemployment rates. New Jersey’s rate has fallen each month this year, to 4.3% in August (see jobs).
U.S. Bureau of Labor Statistics, August 2026 state release, Sept. 18, 2026
-
Jan. 1, 2027
The statewide minimum wage goes up
New Jersey’s minimum wage for most workers is set to rise from $15.92 to $16.48 an hour, the state’s labor department announced on Sept. 29. Seasonal and small employers and farms have lower rates.
Where New Jersey ranks highest and lowest
| Measure | New Jersey | U.S. | Rank | Latest data |
|---|---|---|---|---|
| Median household income 3rd highest · 2024 | $104,202 U.S. $81,604 | $81,604 | 3rd highest | 2024 |
| Homeowners spending at least 30% of income on housing 3rd highest · 2024* | 28.4% U.S. 22.5% | 22.5% | 3rd highest | 2024* |
| Credit card debt per person with a credit report 4th highest · End of 2025 | $5,160 U.S. $4,350 | $4,350 | 4th highest | End of 2025 |
| Basic yearly budget, one adult 5th highest · 2025 | $56,884 U.S. — | — | 5th highest | 2025 |
| Median rent, a month 7th highest · 2024* | $1,720 U.S. $1,413 | $1,413 | 7th highest | 2024* |
| Income per person 8th highest · 2024 | $84,893 U.S. $73,204 | $73,204 | 8th highest | 2024 |
| Renters spending at least 30% of income on housing 9th highest · 2024* | 49.1% U.S. 47.6% | 47.6% | 9th highest | 2024* |
| Household debt per person with a credit report 13th highest · End of 2025 | $69,550 U.S. $63,200 | $63,200 | 13th highest | End of 2025 |
| Unemployment rate, three-month average Tied for 14th highest · June–August 2026 | 4.4% U.S. 4.1% | 4.1% | Tied for 14th highest | June–August 2026 |
| Population growth since 2020 Tied for 21st highest · 2025 | 3.0% U.S. 3.1% | 3.1% | Tied for 21st highest | 2025 |
| Bankruptcy filings per 100,000 residents (2025 population) 24th highest · 2025 | 148.4 U.S. 166.3 | 166.3 | 24th highest | 2025 |
| People with a debt 90+ days late 22nd lowest · Early 2025 | 14.5% U.S. 17.2% | 17.2% | 22nd lowest | Early 2025 |
| Residents getting SNAP food benefits (2025 population) 15th lowest · June 2026 | 7.9% U.S. 10.6% | 10.6% | 15th lowest | June 2026 |
| People with a debt in collections 13th lowest · Early 2025 | 9.4% U.S. 13.2% | 13.2% | 13th lowest | Early 2025 |
| Residents in poverty Tied for 3rd lowest · 2024 | 9.2% U.S. 12.1% | 12.1% | Tied for 3rd lowest | 2024 |
“Highest” and “lowest” count from opposite ends of one list of the 50 states and D.C. * Census five-year survey, 2020 to 2024. Basic yearly budget: MIT Living Wage Calculator, in 2025 dollars, with no U.S. figure. Population growth: Census Bureau estimates for July 2020 to July 2025; the U.S. column is our total for the 50 states and D.C. combined. Debts 90+ days late and in collections count people who have a credit record (Federal Reserve Bank of Philadelphia). For the U.S. column we weighted the states by population. Sources and method lists each row’s source. Download this table: CSV.
Questions about New Jersey
How is New Jersey’s economy doing?
Its unemployment rate fell to 4.3% in August 2026 from 5.5% a year earlier, the largest drop of any state, and BLS found no significant difference between it and the U.S. rate of 4.1% (U.S. Bureau of Labor Statistics). That came after the yearly rate rose every year from 2022 to 2025, reaching 5.2%. BLS found no significant change in the state’s payroll jobs over the year to August 2026.
Is New Jersey expensive to live in?
For housing, yes. Its median rent, $1,720 a month in 2020 to 2024, was the 7th highest of the 50 states and D.C., and 28.4% of homeowners spent at least 30% of their income on housing, the 3rd highest share (U.S. Census Bureau). The MIT Living Wage Calculator puts a single adult’s basic yearly costs at $56,884. We don’t track other prices or property taxes, so we can’t rank the full cost of living.
Why are people leaving New Jersey?
Census estimates count people moving, not their reasons, and we don’t measure why either. They show 211,131 more people moving from New Jersey to other states than arriving from them between July 2020 and July 2025, the 4th highest net loss of any state. Arrivals from abroad more than made up for it, and the population grew 3.0% over those years (U.S. Census Bureau).
What is the poorest county in New Jersey, and the richest?
By the Census Bureau’s 2024 estimates, Hudson County has the highest poverty rate, 14.7%, and Morris County the highest typical household income, $137,213 (Small Area Income and Poverty Estimates). On our County Distress Index, Cumberland County is the most distressed and Morris the least.
What is New Jersey’s poverty line?
Most aid programs use the federal poverty guidelines. In 2026, they are $15,960 a year for one person and $33,000 for a family of four. New Jersey uses the same figures as other states outside Alaska and Hawaii (U.S. Department of Health and Human Services). The 9.2% poverty rate on this page is the Census Bureau’s, a separate measure.
Cite or reuse New Jersey’s data
Use these figures in news stories, research or grant applications, with credit to American Default Research.
State Distress Index
New Jersey
23rdmost distressed state
of the 50 states and D.C.
More distressed than 56% of the other states and D.C.
On American Default Research’s State Distress Index, New Jersey is the 23rd most distressed among the 50 states and D.C. overall. Yet its typical household income was $104,202 in 2024, the 3rd highest in the country (U.S. Census Bureau). Its unemployment rate fell from 5.5% in August 2025 to 4.3% in August 2026, the largest drop of any state (U.S. Bureau of Labor Statistics). In 2020 to 2024, 28.4% of New Jersey homeowners spent at least 30% of their income on housing, the 3rd highest share of any state (U.S. Census Bureau).
Reporters can reach us at press@americandefault.org for interviews or a custom cut of the data.
Sources and method
We gather the data, run the numbers and research each state ourselves.
This edition: October 2026 · Next edition expected March 2027
- Monthly and yearly jobless rates for New Jersey, its counties and the U.S.U.S. Bureau of Labor Statistics, Local Area Unemployment Statistics; State Employment and Unemployment, August 2026Jan. 1990 to Aug. 2026
- Poverty and household income, and county poverty countsCensus Bureau, Small Area Income and Poverty Estimates1989 to 2024
- Renters whose housing costs take half their income or moreCensus Bureau, American Community Survey, one-year estimates2005 to 2024
- Rent, renters’ and homeowners’ housing costsCensus Bureau, American Community Survey, five-year estimates2020 to 2024
- Population and where its change came fromCensus Bureau, population estimates, 2025 estimatesJuly 2020 to July 2025
- Income per personU.S. Bureau of Economic Analysis2024
- Late payments and collectionsFederal Reserve Bank of Philadelphia, Consumer Credit ExplorerEnd of 2019 to early 2025
- Household debt and dollars behindFederal Reserve Bank of New York, Consumer Credit Panel / EquifaxEnd of 2019 and end of 2025
- Mortgages with little equityFederal Housing Finance Agency, National Mortgage DatabaseSecond quarter of 2026
- Mortgages 30 to 89 days late; mortgage complaints; medical debts on credit reportsConsumer Financial Protection Bureau: Mortgage Performance Trends; complaint database; Recent changes in medical collections on consumer credit recordsSept. 2025; Oct. 14, 2026; March 2022 to June 2023
- Bankruptcy filingsAdministrative Office of the U.S. Courts, Table F-22001 to June 2026
- SNAPU.S. Department of Agriculture Food and Nutrition AdministrationJune 2025 to June 2026
- SNAP rules in New JerseyNew Jersey Department of Human Services: Federal Changes to SNAP; work requirements and time limits; food and hunger grants, Oct. 30, 2025Oct. 2025 to 2026
- Cost of getting byMIT Living Wage Calculator2025 dollars
- What residents find hard to affordRutgers-Eagleton PollSept. 24 to 27, 2026
- Mortgage help fundU.S. Treasury, Homeowner Assistance Fund; New Jersey Housing and Mortgage Finance AgencyThrough early 2026
- Foreclosure lawNew Jersey Fair Foreclosure Act, N.J.S.A. 2A:50-53 to 2A:50-68; N.J.S.A. 2A:50-77; N.J.S.A. 2A:50-2; New Jersey Courts; 12 CFR 1024.41As of 2026
- Minimum wage, unemployment claims and layoff noticesNew Jersey labor department: minimum wage release, Sept. 29, 2026; unemployment benefits; 2026 WARN notices and 2025 WARN notices, our count2025 to Jan. 2027
- Electricity prices and bill creditsNew Jersey Board of Public Utilities: auction results, Feb. 12, 2026; bill credit order, June 30, 2026Feb. to Aug. 2026
- State budget and property tax reliefOffice of Governor Mikie SherrillJune 30, 2026
- Poverty guidelineU.S. Department of Health and Human Services2026
- Housing counselorsU.S. Department of Housing and Urban DevelopmentOctober 2026
- Census release datesCensus Bureau, 2025 American Community Survey release scheduleupdated Oct. 13, 2026
- PhotoSmallbones, via Wikimedia Commons, public domain2010
The score has four equal parts: renters’ housing costs, late payments, collections and bankruptcy, and jobs. Each measure is scored against all 50 states and D.C., and New Jersey’s score is the percentage of the other 50 places with a lower four-part average. The full method →
We write with AI tools, and Ross Kilburn checks and reviews every page before it's published.
Get the next New Jersey edition by email
One email each time a new New Jersey edition is out; the next is expected in March 2027. Unsubscribe anytime.
Thanks, that helps.