Washington is the least distressed of the states with unemployment as high as its 4.9%
Each state is shaded by how distressed its households are, from green (least) to red (most), with data through September 2026. Washington scores 40 out of 100.
In August 2026, 4.9% of Washington's labor force was out of work, tied for 6th highest nationally. Its borrowers rarely fall far behind; the share of residents with a debt 90 or more days late was the 8th lowest in early 2025. No state has a wider gap between its job market part and its late payments part. The strain runs highest in Grays Harbor County, on the Pacific coast, which is more distressed than 77% of U.S. counties.
- Score
- 40/100
- Data through
- September 2026
- Edition
- October 2026
Next edition expected March 2027
How Washington ranks among the states
Washington is the 31st most distressed of the 50 states and D.C. on our State Distress Index, in the less distressed half of the country even though its job market is among the weakest. Every other place with unemployment of 4.7% or more in August 2026 scores 54 or more; Washington scores 40. No other state has a wider gap between its job-market part and its behind-on-payments part: 73 points. Two things argue against reading too much into that. The late-payment figures come from the first quarter of 2025, and unemployment kept climbing afterward, so credit reports may not show the strain yet. And the jobless rate counts only people looking for work. The state’s Employment Security Department says part of its recent fall came from a shrinking labor force, meaning fewer people working or looking for work (see unemployment below). One possibility, which we haven’t tested, is that high incomes and few people with low credit scores (9.1%, tied for 4th lowest) keep late payments down even among people who are out of work.
What drives the score
Each part scores 0 to 100 from measures ranked against the other states, and a higher score means more distress. The job market and renters’ costs rest on one measure each; the other two parts average theirs. Washington’s four parts average 45. That average is more distressed than the average for 20 of the other 50 places (49 states and D.C.), or 40% of them. That share is the score, so the score isn’t the average of the parts.
- Job market88Unemployment averaged 5.0% from June to August 2026, against 4.1% nationwide
- Renters’ housing costs52In 2024, the Census one-year survey found 23.8% of renters paid half or more of their income for housing
- Collections and bankruptcy24Fewer people with unpaid debt sent to a collector than in most states, and a bankruptcy rate below the middle
- Behind on payments16Few borrowers 90 or more days late on cards, mortgages or car loans; this part is tied for 7th lowest
Beside its neighbors
Oregon is more distressed than Washington; Idaho is less.
State Distress Index score, 0 to 100. Oregon had nearly the same jobless rate in August 2026, 5.1%, but scores far higher; more of its renters paid half or more of their income for housing in 2024 (26.6%, Census one-year survey). Idaho’s rate was 3.6%.
How the score has changed since 2006
Its highest score
25th most distressed, with a score of 52, in the fourth quarter of 2006, the first quarter of 2007 and the second quarter of 2012
Before the pandemic and since
A score of 30 at the end of 2019 and 34 in the first quarter of 2025. Today it scores 40 and ranks 31st.
What pushed it up since 2019
The job market: that part climbed from 69 at the end of 2019 to 88 now, while the other three parts moved far less
Washington’s score bottomed out at 24 in 2021 and has risen since
State Distress Index score, 0 to 100, each quarter, third quarter of 2006 to first quarter of 2025
Is Washington a poor state? Poverty and income
No. In 2024, 10.0% of Washingtonians lived in poverty, tied for 10th lowest among the 50 states and D.C., against 12.1% nationwide. The typical household earned $99,309, 8th highest, against $81,604 (Census Bureau, Small Area Income and Poverty Estimates). Among children, the poverty rate was 11.5%.
Residents in poverty
10.0%
U.S. 12.1%
Tied for 10th lowest of the 50 states and D.C., 2024
Median household income
$99,309
U.S. $81,604
8th highest of the 50 states and D.C., 2024
Income per person
$85,187
U.S. $73,204
7th highest, 2024 (Bureau of Economic Analysis)
Washington’s poverty rate has stayed under the U.S. rate in every year of Census estimates since 1989
Share of residents in poverty, Washington and the United States, 1989 to 2024 (no estimates for 1990 to 1992 or 1994)
What weighs on Washington’s economy
Mostly jobs, not poverty. The jobless rate reached its highest since 2021 in spring 2026 (see unemployment below). Paychecks matter more here than in most states. In 2024, wages made up 53.1% of all personal income, 4th highest, and government benefits such as Social Security and Medicaid only 14.6%, 5th lowest (Bureau of Economic Analysis). We haven’t tested whether a state where more income comes from wages feels a hiring slump sooner. One caution: the Bureau of Economic Analysis counts a wage in the county where the job is, not the one where the worker lives.
Food help and the poverty line
In July 2026, 832,201 Washingtonians got SNAP food benefits (formerly food stamps), 10.4% of residents, against 10.5% nationwide (U.S. Department of Agriculture). Federal SNAP work rules changed under the 2025 budget law; the state applies them at each household’s next review (Department of Social and Health Services).
Programs that ask about “the poverty level” use the federal poverty guideline. For 2026 it is $15,960 a year for a single person and $33,000 for four people (U.S. Department of Health and Human Services). The poverty rate above uses the Census Bureau’s thresholds, a separate measure.
Washington’s unemployment rate and economy
Washington’s unemployment rate was 4.9% in August 2026, against 4.1% nationwide (U.S. Bureau of Labor Statistics). That was tied for 6th highest of the 50 states and D.C. Both rates are seasonally adjusted, which smooths out regular seasonal swings. The August rate is down from its spring peak. This page uses the Bureau of Labor Statistics’ August figures so every state is measured the same way; the state’s own September figure, below, is preliminary. Over all of 2025 the rate averaged 4.7%, tied for 8th highest, up from 4.2% in 2019.
Unemployment rate
4.9%
U.S. 4.1%
Tied for 6th highest, August 2026
Unemployment, yearly average
4.7%
U.S. 4.3%
Tied for 8th highest, 2025
Washington’s unemployment rate rose to 5.2% in spring 2026, its highest since June 2021
Unemployment rate each month, Washington and the United States, seasonally adjusted, January 1990 to August 2026
The state’s preliminary September rate dipped, partly because the labor force shrank
Washington’s Employment Security Department put the September rate at 4.8% on Oct. 14, a preliminary figure, and said the state lost jobs that month, most of them in government and in education and health services.
Anneliese Vance-Sherman, the department’s chief labor economist, said the fall partly reflected fewer unemployed workers. She said it also reflected “an overall reduction in the size of the labor force,” meaning fewer people working or looking for work (Employment Security Department, Oct. 14, 2026).
Layoff notices: the department’s WARN database lists them by company. Unemployment benefits are filed with the Employment Security Department.
Behind on bills: household debt in Washington
Washington residents with a credit report owed an average of $85,880 in household debt at the end of 2025, 4th highest, against $63,200 nationwide (Federal Reserve Bank of New York). Few of them fall far behind. In the first quarter of 2025, 11.6% of residents with a credit report had a debt 90 or more days late, 8th lowest. The U.S. figure, our average of the states weighted by population, was 17.2% (Federal Reserve Bank of Philadelphia). This is money households owe, not the state government’s debt.
Among the 50 states and D.C.: card, tied for 7th lowest; collections, tied for 10th lowest; auto, tied for 13th lowest; mortgage, tied for 3rd lowest. The U.S. figure here is our own population-weighted average across the states.
Washington’s card borrowers have slipped since 2019: 9.3% were 90 or more days late in early 2025, against 6.9% at the end of 2019. Debt in collections went the other way. It fell from 14.7% at the end of 2019 to 11.5% in early 2022, then to 8.4% by mid-2023, when the credit bureaus dropped most medical debts from credit reports. Nationally, the share of people with a credit record who had a medical debt in collections fell from about 14% in March 2022 to about 5% in June 2023 (Consumer Financial Protection Bureau). Much of that drop reflects what credit reports count, not fewer people struggling.
A second measure: the share of dollars owed that is late
The New York Fed counts money, not people, so the two Fed measures count different things and similar-looking figures are not the same figure. On this measure too, Washington’s late share is lower than the U.S. share on cards, car loans and mortgages. Debt per person grew 27% from the end of 2019 to the end of 2025, against 23% nationwide (our calculation).
| Loan type | Wash. | U.S. | Wash. 2019 | U.S. 2019 |
|---|---|---|---|---|
| Credit card | 9.3% End of 2025 U.S. 12.4% Wash. 2019 5.8% · U.S. 2019 8.1% | 12.4% | 5.8% | 8.1% |
| Auto loan | 3.8% End of 2025 U.S. 5.2% Wash. 2019 2.6% · U.S. 2019 4.9% | 5.2% | 2.6% | 4.9% |
| Mortgage | 0.6% End of 2025 U.S. 0.9% Wash. 2019 0.5% · U.S. 2019 1.0% | 0.9% | 0.5% | 1.0% |
Share of balances 90 or more days past due, end of 2025 and end of 2019. Source: Federal Reserve Bank of New York, Consumer Credit Panel / Equifax. It counts dollars, not people, so it doesn’t match the Philadelphia Fed figures above, and the New York Fed’s figures keep old debts that lenders have written off but still report.
Bankruptcy
Washington residents filed 9,346 bankruptcy cases in 2025, or 116.8 for every 100,000 people (based on 2025 population). That rate was 31st highest of the 50 states and D.C.; the U.S. rate was 166.3 (Administrative Office of the U.S. Courts). That is up from 5,162 cases in 2022. Chapter 13 repayment plans, where filers pay debts back over several years, were 19.7% of cases, against 35.9% nationwide.
Is Washington expensive? Cost of living for renters
For rent, yes; set against incomes, about average. The typical rent over 2020 to 2024 was $1,760 a month, 6th highest of the 50 states and D.C., against $1,413 nationwide. Because incomes are high too, 47.5% of renter households spent 30% or more of their income on housing, close to the U.S. share of 47.6% (Census Bureau, American Community Survey).
Median rent
$1,760
U.S. $1,413
6th highest, 2020 to 2024
Renters spending 30%+ of income on housing
47.5%
U.S. 47.6%
16th highest, 2020 to 2024
Homeowners spending 30%+ of income on housing
24.2%
U.S. 22.5%
14th highest, 2020 to 2024
What it takes to get by
MIT’s Living Wage Calculator puts a year’s basic costs for one adult with no children in Washington at $55,316. Among the 50 states and D.C., that is 7th highest. Two working parents with two children need $140,915 combined.
MIT Living Wage Calculator, 2025 dollars.
What this page doesn’t measure
We don’t track prices for food, child care, gas, insurance or taxes, so we can’t rank Washington’s overall cost of living, and we have no city figures for Seattle. Homelessness counts and pay by job aren’t here either.
Beside Oregon and Idaho
Rent takes about the same share of income in Washington as in Oregon, and more than in Idaho.
| State | Rent | Income | Rent share | Own homes |
|---|---|---|---|---|
| Washington | $1,760 Rent Income $99,309 Rent share 21.3% · Own homes 63.8% | $99,309 | 21.3% | 63.8% |
| Oregon | $1,525 Rent Income $84,897 Rent share 21.6% · Own homes 63.3% | $84,897 | 21.6% | 63.3% |
| Idaho | $1,238 Rent Income $80,852 Rent share 18.4% · Own homes 72.1% | $80,852 | 18.4% | 72.1% |
Rent is the median monthly rent, and Own homes the share of homes lived in by their owners: Census Bureau, American Community Survey, 2020 to 2024. Median household income: Census Bureau, 2024. Rent share: a year’s median rent against median household income, our calculation.
What changed in Washington in the past year
Changes that reached household budgets between last fall and the October 2026 figures, newest first. Each item links to the page it came from.
-
Oct 1, 2026
Apple Health narrowed for many lawfully present immigrants
Under the federal budget law signed on July 4, 2025, Apple Health, the state’s Medicaid program, now covers fewer lawfully present noncitizens. The Department of Social and Health Services projects that about 11,000 Washington residents will lose coverage; a new court order protects Apple Health coverage for more than 800 Washingtonians.
Washington State Department of Social and Health Services, DSHS benefits and H.R. 1
-
Apr 7, 2026
Disaster aid for the December storms
The Federal Emergency Management Agency declared a major disaster for the storms, floods and landslides of Dec. 5 to 19, 2025, and opened aid for households in 10 counties, Grays Harbor, King and Pierce among them. As of October 2026, FEMA’s data show it has approved $17.17 million for 1,551 applications. The main window to apply has closed.
-
Mar 30, 2026
A new tax on the highest incomes signed into law
Gov. Bob Ferguson signed Senate Bill 6346, the tax on income over $1 million a year, often called the “millionaires tax.” It is set to apply from 2028, and voters decide on Nov. 3 whether to repeal it (details in the taxes section below).
-
Jan 1, 2026
Higher Puget Sound Energy bills
State regulators approved new rates for Puget Sound Energy, the utility for much of Central and Western Washington: a rise of roughly 12% for electricity, or about $17 a month for an average home using 800 kilowatt-hours, and roughly 7% for natural gas.
Washington Utilities and Transportation Commission, Dec. 31, 2025
-
Jan 1, 2026
Minimum wage up again
The state minimum wage rose to $17.13 an hour, the highest of any of the 50 states. State law ties it to inflation each year, and cities can set more.
Washington State Labor & Industries (L&I); Washington State Standard, Oct. 1, 2026
The poorest county in Washington state, and the most distressed
Whitman County, on the Idaho border, had the highest poverty rate in Washington in 2024: 23.0% of its residents, the Census Bureau estimates. On our County Distress Index, Grays Harbor County on the Pacific coast is the most financially distressed, with a score of 77, and Chelan County, around Wenatchee, is the least distressed, at 20.
Washington’s five most distressed counties are on the coast and east of the Cascades
County Distress Index score, 0 to 100, for Washington’s 39 counties, data through August 2026.
Loading the county map…
The county map could not be loaded. Every county is in the lists on this page.
Most distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 1 | Grays Harbor | 77 | 15.9% |
| 2 | Yakima | 69 | 16.7% |
| 3 | Adams | 68 | 14.4% |
| 4 | Grant | 62 | 16.8% |
| 5 | Okanogan | 60 | 21.7% |
| 6 | Lewis | 56 | 10.6% |
| 7 | Mason | 53 | 12.2% |
| 8 | Columbia | 52 | 12.4% |
| 9 | Pierce | 51 | 9.4% |
| 10 | Cowlitz | 51 | 10.6% |
Least distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 35 | Skamania | 27 | 10.3% |
| 36 | Kitsap | 27 | 7.8% |
| 37 | King | 23 | 8.8% |
| 38 | San Juan | 21 | 10.6% |
| 39 | Chelan | 20 | 10.2% |
Rank in Washington, 1 = most distressed. Ranks use unrounded scores, so Pierce and Cowlitz both show 51 yet rank 9th and 10th. Poverty: share of residents in poverty, Census Bureau, 2024.
Every county, by score
Most Washington counties score in the 30s and 40s: 21 of the 39. Grays Harbor alone scores 70 or more, and none reaches 80.
0 score 80–100
1 score 70–79
11 score 50–69
Yakima, Adams, Grant, Okanogan, Lewis, Mason, Columbia, Pierce, Cowlitz, Garfield, Pacific
Poorest isn’t the same as most distressed
A poverty rate looks at income alone. Our county score adds late payments, collections and bankruptcy, jobs and housing costs. Whitman, the county with the most poverty, ranks only 27th of 39 on distress. Grays Harbor is the sixth poorest county, yet it tops the distress list. Pierce County, south of Seattle, has the 4th highest median household income in the state and the 7th lowest poverty rate of the 39 counties (33rd highest). Even so, it ranks 9th most distressed, with renters’ housing costs weighing most.
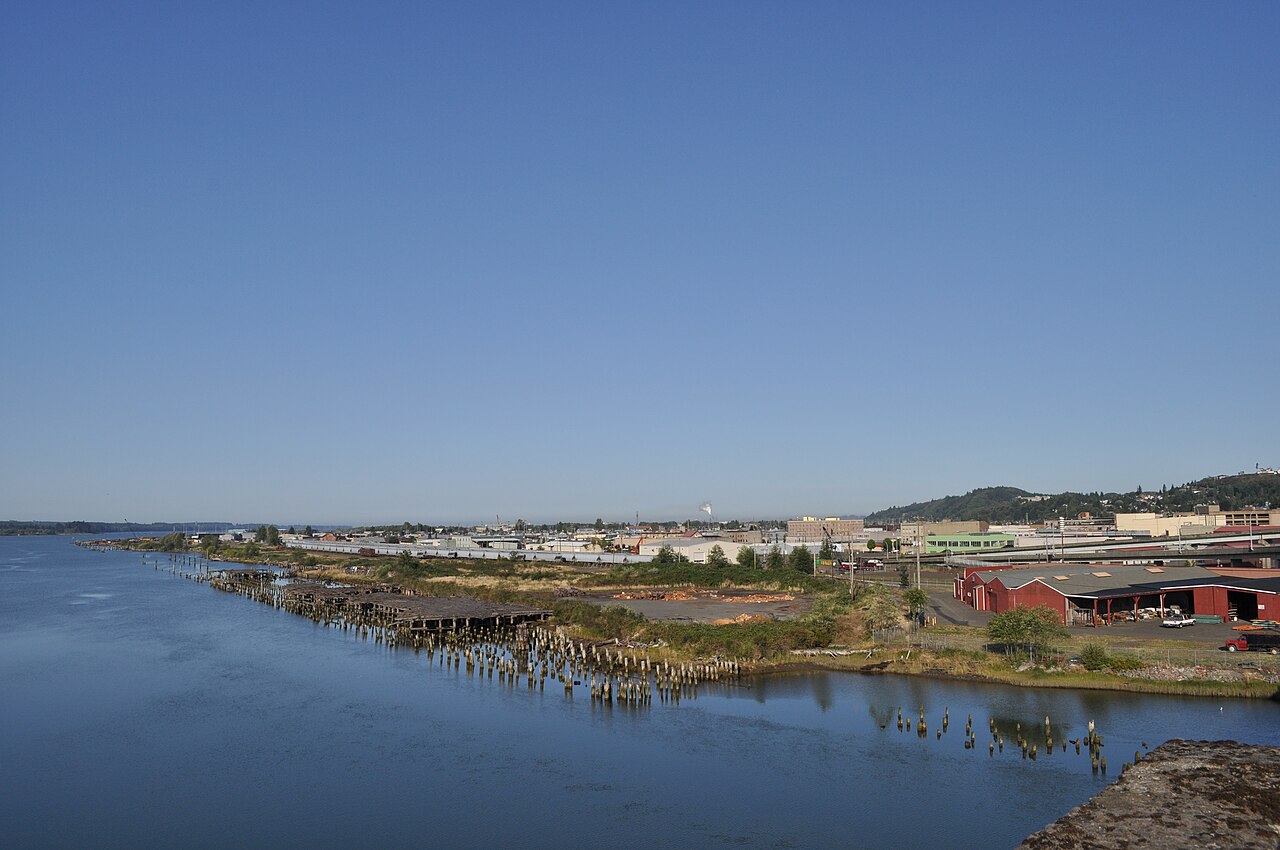
Downtown Aberdeen and the Chehalis River in 2009. Aberdeen is in Grays Harbor County, the most distressed county in the state on our index and one of those where FEMA offered aid to households after the storms of December 2025.
Source: FEMA, disaster DR-4906-WA. Photo: Joe Mabel, via Wikimedia Commons, CC BY-SA 3.0.

King County: the highest incomes, and among the least distressed
King County, home to Seattle, had the highest median household income of any Washington county in 2024, $121,984. It scores 23 on our index; only San Juan and Chelan score lower.
Census Bureau, Small Area Income and Poverty Estimates, 2024; American Default Research, County Distress Index.
Ferry, Wahkiakum and Pacific had the highest county jobless rates
In August 2026, unemployment ran highest in Ferry County, 6.8%, then Wahkiakum, 6.5%, and Pacific, 6.1%. County rates aren’t adjusted for seasonal swings, so they can’t be set beside the statewide rate.
U.S. Bureau of Labor Statistics, Local Area Unemployment Statistics, August 2026.
Washington foreclosure laws: most sales skip the courtroom
Most Washington home loans are secured by a deed of trust (the paper that lets a neutral trustee sell the home if payments stop). Under the Deeds of Trust Act (RCW 61.24), the trustee can sell the home without a lawsuit. Before it sells, the lender has to try to reach the homeowner by letter and phone, then send a notice of default. The notice of sale has to be recorded at least 90 days before the sale. The wait is 120 days when the lender was required to send a first contact letter (RCW 61.24.031 and 61.24.040).
After a notice of default, a housing counselor or a lawyer can refer the homeowner to the state’s foreclosure mediation program; homeowners can’t sign themselves up (RCW 61.24.163). After a trustee’s sale of a home, the lender generally can’t sue for the leftover balance (RCW 61.24.100).
- Usual route
- No court
- Notice of sale before the auction
- 90 days or more
- Mediation
- By referral
- Suit for the leftover balance
- Generally barred
What the law says for a home you live in. Sources: RCW 61.24.031, 61.24.040, 61.24.100 and 61.24.163. How foreclosure works in Washington →
Washington received $173.2 million from the federal Homeowner Assistance Fund, which paid housing bills for homeowners who fell behind, and had helped 6,835 households with it through the first quarter of 2026 (U.S. Treasury).
Washington mortgage complaints sent to the Consumer Financial Protection Bureau
People in Washington have filed 10,389 mortgage complaints with the Consumer Financial Protection Bureau since 2012. The largest group, 2,666, is about loan modification, collection or foreclosure; trouble during the payment process follows with 2,458.
- Oct. 8, 2026 M&T Bank Struggling to pay: applying for a modification, forbearance, short sale or deed-in-lieu Closed with explanation
- Oct. 5, 2026 PennyMac Payment process: escrow, taxes or insurance Closed with non-monetary relief
- Oct. 4, 2026 Rocket Mortgage Payment process: paying off the loan Closed with explanation
- Oct. 4, 2026 M&T Bank Struggling to pay: trouble reaching the company about a modification, forbearance or foreclosure Closed with explanation
- Oct. 3, 2026 Rocket Mortgage Payment process: paying off the loan Closed with explanation
- Oct. 2, 2026 Idaho Housing and Finance Association Struggling to pay: trouble reaching the company about a modification, forbearance or foreclosure In progress
- Oct. 2, 2026 Rocket Mortgage Payment process: fees charged Closed with explanation
- Oct. 2, 2026 Shellpoint / NewRez Payment process: escrow, taxes or insurance Untimely response
- Oct. 1, 2026 M&T Bank Payment process: escrow, taxes or insurance Closed with explanation
- Oct. 1, 2026 Guild Mortgage Payment process In progress
The latest ten Washington complaints about paying a mortgage or getting help with one, newest first, from the Consumer Financial Protection Bureau’s public database as of October 2026. A forbearance is a pause on payments; a deed-in-lieu hands the home back to the lender to avoid foreclosure; a short sale sells for less than is owed. “Closed with explanation” means the company replied with an explanation; “Untimely response” means it missed the bureau’s deadline. Complaints about taking out a new loan are left out, as are those naming a credit bureau. Each is one person’s account, which the bureau doesn’t verify. Every Washington mortgage complaint at the CFPB →
Washington state taxes: the new tax on the highest incomes and the vote on it
Washington doesn’t tax wages today. In 2026 the Legislature passed, and Gov. Bob Ferguson signed on March 30, Senate Bill 6346: a 9.9% tax on income over $1 million a year (often called the “millionaires tax”), with a married couple counted as one household. It is set to apply from Jan. 1, 2028, with the first payments due in 2029, so nobody owes it yet. The Department of Revenue expected about 21,000 filers to pay it (Washington State Standard).
The same law widens the Working Families Tax Credit to an estimated 810,000 households, from 350,000, and is set to end sales tax on diapers, some personal-care products and over-the-counter medicines on Jan. 1, 2029.
The tax’s future is open. On Nov. 3, 2026, voters decide Initiative IP26-645, which would repeal the tax. The Office of Financial Management estimates repeal would cost the state $11.4 billion in revenue over state fiscal years 2027 to 2031 (see dates to watch below). In May the state Supreme Court turned down a first challenge, over the law’s clause blocking a referendum (KUOW). A separate lawsuit over whether the tax is constitutional was still in court as of July 2026 (OPB). Washington already taxes some capital gains (Washington Secretary of State, Voters’ Pamphlet).
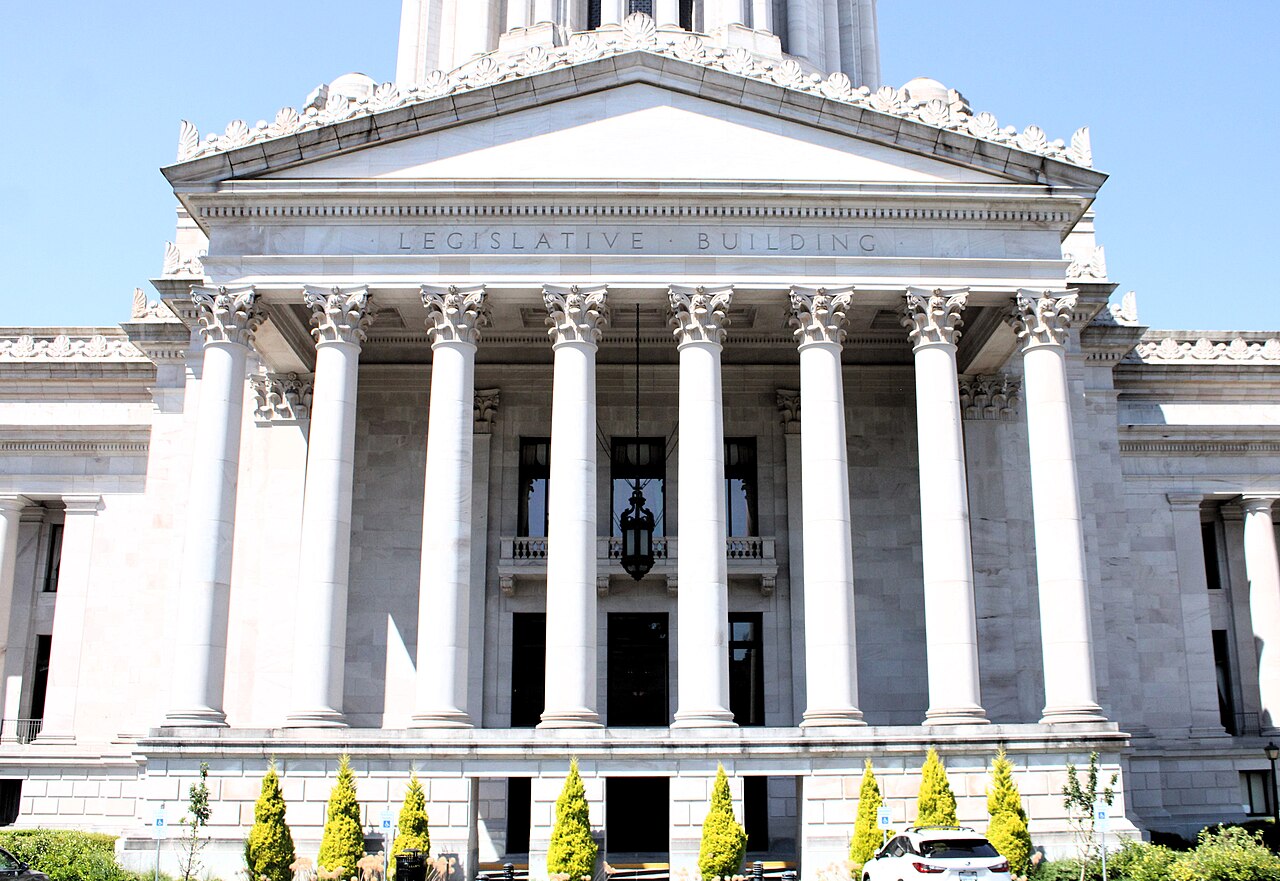
The Legislative Building in Olympia, where lawmakers passed the tax in 2026.
Source: Washington State Standard. Photo: Farragutful, via Wikimedia Commons, CC BY-SA 4.0.

What to watch before the next edition
Dates already set, nearest first.
-
Nov 3, 2026
Vote on repealing the new tax on the highest incomes
Voters decide Initiative IP26-645. A simple majority would repeal the tax (see the taxes section below) and bar state and local taxes on personal income; the credits and sales-tax breaks passed with it would stay. If approved, the measure takes effect Dec. 3, 2026.
Washington Secretary of State, 2026 General Election Voters’ Pamphlet
-
Nov 16, 2026
New state revenue forecast
The Economic and Revenue Forecast Council’s revenue forecast is set for Nov. 16. The council says its dates can change.
Washington State Economic and Revenue Forecast Council, 2026 meeting schedule
-
Nov 20, 2026
State jobless rates for October
The Bureau of Labor Statistics releases state unemployment rates for October at 10 a.m. Eastern.
-
Jan 1, 2027
Minimum wage and paid-leave premium set to rise
The minimum wage is set to reach $17.73 an hour for most workers. The same day, the Paid Family and Medical Leave premium is set to rise to 1.2% of wages, from 1.13%; employees pay most of it.
Washington State Standard, Oct. 1, 2026; Employment Security Department, Oct. 16, 2026
-
Jan 1, 2027
Apple Health work rules set to begin
Federal work requirements for Apple Health adults aged 19 to 64 are set to start, and their coverage renewals are set to come every six months instead of every year. The state may ask for a waiver to start the work rule as late as Dec. 31, 2028. Apple Health covers nearly 2 million people.
Washington State Health Care Authority, Impacts of H.R. 1 on Apple Health
Where Washington ranks highest and lowest
Washington’s place among the 50 states and D.C. on the measures people search for. “Highest” and “lowest” mean among all 51.
| Measure | Wash. | U.S. | Rank | Latest data |
|---|---|---|---|---|
| State Distress Index score 31st highest · Aug 2026 | 40 U.S. — | — | 31st highest | Aug 2026 |
| Unemployment rate, three-month average Tied for 5th highest · June–August 2026 | 5.0% U.S. 4.1% | 4.1% | Tied for 5th highest | June–August 2026 |
| Residents in poverty Tied for 10th lowest · 2024 | 10.0% U.S. 12.1% | 12.1% | Tied for 10th lowest | 2024 |
| Children in poverty 11th lowest · 2024 | 11.5% U.S. 15.5% | 15.5% | 11th lowest | 2024 |
| Median household income 8th highest · 2024 | $99,309 U.S. $81,604 | $81,604 | 8th highest | 2024 |
| Income per person 7th highest · 2024 | $85,187 U.S. $73,204 | $73,204 | 7th highest | 2024 |
| Household debt per person with a credit report 4th highest · End of 2025 | $85,880 U.S. $63,200 | $63,200 | 4th highest | End of 2025 |
| People with any debt 90+ days late 8th lowest · Early 2025 | 11.6% U.S. 17.2% | 17.2% | 8th lowest | Early 2025 |
| Card borrowers 90+ days late Tied for 7th lowest · Early 2025 | 9.3% U.S. 13.5% | 13.5% | Tied for 7th lowest | Early 2025 |
| Median rent 6th highest · 2024* | $1,760 U.S. $1,413 | $1,413 | 6th highest | 2024* |
| Renters spending 30% or more of income on housing 16th highest · 2024* | 47.5% U.S. 47.6% | 47.6% | 16th highest | 2024* |
| Residents getting SNAP Tied for 22nd highest · July 2026 | 10.4% U.S. 10.5% | 10.5% | Tied for 22nd highest | July 2026 |
| Bankruptcy filings per 100,000 31st highest · 2025 | 116.8 U.S. 166.3 | 166.3 | 31st highest | 2025 |
* Census five-year survey, 2020 to 2024. Sources for each measure are in Sources and method. The U.S. figures for late payments are our average of the states, weighted by population. Download this table: CSV.
Questions about Washington
Where does Washington rank in poverty?
Among the lowest. In 2024, 10.0% of Washington residents lived below the poverty line, tied for 10th lowest of the 50 states and D.C.; the U.S. rate was 12.1% (U.S. Census Bureau, Small Area Income and Poverty Estimates). Poverty and income →
What is the poorest county in Washington state?
Whitman County, by the Census Bureau’s 2024 estimates: 23.0% of its residents lived in poverty, ahead of Okanogan County at 21.7%. On our County Distress Index, the most distressed county is Grays Harbor. Washington’s counties →
What is the unemployment rate in Washington state?
It was 4.9% in August 2026, seasonally adjusted, tied for 6th highest of the 50 states and D.C.; the U.S. rate was 4.1% (U.S. Bureau of Labor Statistics). The state’s own Employment Security Department put September at 4.8%, a preliminary figure. Jobs →
Is Washington state expensive to live in?
For renters, the rent is high: $1,760 a month at the median over 2020 to 2024, 6th highest (U.S. Census Bureau). Incomes are high too, so the share of renters spending 30% or more of income on housing, 47.5%, is close to the U.S. share. We don’t measure food, child care, gas or insurance prices. Cost of living →
Does Washington have a state income tax?
Not on wages. A 9.9% tax on income over $1 million a year was signed on March 30, 2026, and is set to apply from Jan. 1, 2028. Voters decide on Nov. 3, 2026 whether to repeal it (Initiative IP26-645), and a lawsuit over whether it is constitutional was still in court as of July 2026 (Washington Secretary of State; OPB). Taxes →
Cite or reuse Washington’s data
For grant applications, policy memos and news stories.
State Distress Index
Washington
31stmost distressed state
of the 50 states and D.C.
More distressed than 40% of the other states and D.C.
Washington is the 31st most distressed of the 50 states and D.C. on the State Distress Index, American Default Research’s measure of household financial distress. Its unemployment rate was 4.9% in August 2026, against 4.1% nationwide (U.S. Bureau of Labor Statistics). Yet in the first quarter of 2025, only 11.6% of residents with a credit report had a debt 90 or more days late (Federal Reserve Bank of Philadelphia). The U.S. figure, our average of the states weighted by population, was 17.2%.
Questions, interviews or a custom cut of the data: press@americandefault.org
Sources and method
We gather the data, run the numbers and research each state ourselves.
This edition: October 2026 · Next edition expected March 2027
- Unemployment, state and countyU.S. Bureau of Labor Statistics: state release for August 2026, Local Area Unemployment StatisticsAug 2026
- September unemployment, jobs, layoff notices, paid-leave premiumWashington State Employment Security Department: Oct. 14, 2026 release, WARN database, Oct. 16, 2026 releaseSept and Oct 2026
- Poverty and incomeCensus Bureau, Small Area Income and Poverty Estimates2024
- Rent, housing costs, homeownershipCensus Bureau, American Community Survey2020 to 2024; renters paying half or more: 2024
- Income per person, wages, government benefitsU.S. Bureau of Economic Analysis2024
- Late payments, collections, credit scoresFederal Reserve Bank of Philadelphia, Consumer Credit Explorerfirst quarter of 2025
- Household debt and dollars behindFederal Reserve Bank of New York, Consumer Credit Panel / Equifaxend of 2025
- Medical debt on credit reportsConsumer Financial Protection Bureau, Recent changes in medical collections on consumer credit recordsMarch 2022 to June 2023
- Bankruptcy filingsAdministrative Office of the U.S. Courts, Table F-22025
- SNAPU.S. Department of Agriculture, SNAP dataJuly 2026
- Poverty guidelineU.S. Department of Health and Human Services2026
- Cost of getting byMIT Living Wage Calculator2025 dollars
- Mortgage complaintsConsumer Financial Protection Bureau, Consumer Complaint DatabaseOct 2026
- Mortgage help fundU.S. Treasury, Homeowner Assistance Fundthrough the first quarter of 2026
- Foreclosure lawRevised Code of Washington, chapter 61.24, the Deeds of Trust Actas of Sept 2026
- Housing counselorsU.S. Department of Housing and Urban DevelopmentOct 2026
- What changed in the past yearWashington State Department of Social and Health Services; FEMA and OpenFEMA; Washington State Standard on the income tax and the minimum wage; Washington Utilities and Transportation Commission; Washington State Labor & Industries (L&I)Dec 2025 to Oct 2026
- Tax on income over $1 millionKUOW; OPBMay to July 2026
- What to watchWashington Secretary of State, 2026 Voters’ Pamphlet; Economic and Revenue Forecast Council; Bureau of Labor Statistics, November 2026 calendar; Washington State Health Care AuthorityApr to Oct 2026
The score has four equal parts: late payments; collections and bankruptcy; jobs; and renters’ housing costs. Each measure is ranked against the 50 states and D.C., and the score is the share of the other 50 places (49 states and D.C.) that Washington is more distressed than. The full method →
We write with AI tools, and Ross Kilburn checks and reviews every page before it's published.
Get the next Washington edition by email
One email each time a new Washington edition is out; the next is expected in March 2027. Unsubscribe anytime.
Thanks, that helps.