Ohio's jobless rate fell to 3.3%, mostly because fewer people were counted as looking for work
Each state is shaded by how distressed its households are, from green (least) to red (most), with data through September 2026. Ohio scores 46 out of 100.
The drop in Ohio's jobless rate isn't a hiring wave. From February 2025 to August 2026 the labor force shrank by 112,864 people, so the rate fell mostly because fewer Ohioans were counted as looking for work. Collections and bankruptcy remain the highest part of the score, even though Ohioans owe less per person than people in most states. Scioto County, on the Ohio River, is more distressed than 92% of U.S. counties, the most of Ohio's 88.
- Score
- 46/100
- Data through
- September 2026
- Edition
- October 2026
Next edition expected March 2027
How Ohio ranks among the states
Ohio lands in the middle today after swinging from near the top of the list. From mid-2006 through 2007 it was the 3rd most distressed state. In early 2025 it was still tied for 13th. It fell to 28th as unemployment dropped from 4.9% in February 2025 to 3.3% in August 2026 (U.S. Bureau of Labor Statistics). Collections and bankruptcy remain its highest-scoring part. Ohioans owe less per person than people in most states, yet more have a debt with a collector or file for bankruptcy (see behind on bills).
What drives the score
Each part runs from 0 to 100 and says where Ohio stands among the 50 states and D.C. on the measures inside it; a higher number means more strain. Ohio’s four parts average 51. The State Distress Index score is figured differently: it counts the other 49 states and D.C. with a lower combined measure. That is 23 of them, or 46%, so Ohio scores 46. A state scoring 80 would be more distressed than 80% of the others.
- Collections and bankruptcy73In 2025 Ohioans filed 219.4 bankruptcy cases for every 100,000 residents (2025 population), against 166.3 nationally, and early in 2025, 14.6% of Ohioans with a credit record had a debt with a collector, against 13.2%.
- Late payments57Early in 2025, 13.8% of Ohio card borrowers and 9.0% of car-loan borrowers were 90 days or more behind, slightly above the U.S. shares; mortgage borrowers, at 1.1%, were slightly below.
- Renters’ housing costs46In 2024, 24.6% of Ohio’s renter households spent half or more of their income on rent and utilities, under the U.S. share of 26.1%.
- Jobs26Unemployment averaged 3.4% from June through August 2026, against 4.1% for the nation.
Ohio beside its neighbors
All five of Ohio’s neighbors score higher. Michigan, to the north, is the most distressed of them and one of the most distressed states in the country. Pennsylvania and Indiana come closest.
State Distress Index score, 0 to 100. Michigan stands 5th for distress among the 50 states and D.C.; Kentucky is 15th and Indiana 26th. In August 2026 Ohio and Indiana both had an unemployment rate of 3.3%, against 4.7% in Kentucky and 5.0% in Michigan (U.S. Bureau of Labor Statistics).
Ohio’s score has risen and fallen with its jobless rate, from near the top of the states to the middle
At its worst
From the third quarter of 2006 through the third quarter of 2007, Ohio scored 96, the 3rd most distressed state in the quarterly State Distress Index history since 2006.
At its best
Ohio’s lowest score, 44, came in the first quarter of 2015, when it ranked 29th, its least distressed place. The biggest drop before that came in the third quarter of 2014, when the score fell from 60 to 46, mostly because the renters’ part fell with that year’s Census renter figures.
Since the chart ends
Our quarterly history stops at the first quarter of 2025, when Ohio was tied for 13th with a score of 74. Today it is 28th, with 46. Nearly all of that change is the jobs part, which fell from 87 to 26. The renters’ part rose from 42 to 46 with the Census Bureau’s 2025 figures, collections and bankruptcy slipped from 75 to 73, and late payments from 59 to 57.
Ohio was the 3rd most distressed state from mid-2006 through 2007, 29th at its best in 2015 and tied for 13th in early 2025
Ohio’s State Distress Index score in each quarter, on a scale of 0 to 100, starting in the third quarter of 2006, when all four parts were first available, and ending in the first quarter of 2025.
What is Ohio’s unemployment rate? The lowest in decades, but fewer Ohioans are working
In August 2026, 3.3% of Ohio’s labor force was out of work, tied for 13th lowest among the 50 states and D.C. The national rate was 4.1% (U.S. Bureau of Labor Statistics, seasonally adjusted). That is the lowest monthly rate for Ohio in the bureau’s figures, which start in 1976, though August’s number is preliminary and can be revised. As recently as February 2025 the rate was 4.9%, and over 2025 as a whole it averaged 4.6%, above the U.S. average of 4.3%.
Filing for unemployment benefits? Claims go through Ohio’s job and family services department →
Unemployment rate
3.3%
U.S. 4.1%
Tied for 13th lowest of the states and D.C. for August 2026
Yearly average unemployment rate
4.6%
U.S. 4.3%
2025, U.S. Bureau of Labor Statistics
Fewer Ohioans in the labor force
112,864
February 2025 to August 2026, our calculation from U.S. Bureau of Labor Statistics figures
The drop isn’t a hiring wave. From February 2025 to August 2026, the number of Ohioans counted as unemployed fell by 94,874, but the number with a job fell too, by 17,990. The labor force shrank by 112,864. So the rate fell mostly because fewer people were counted as looking for work, not because more of them found it. The share of Ohioans 16 and older with a job slipped from 59.8% to 59.2% (U.S. Bureau of Labor Statistics, seasonally adjusted; the differences are our calculation). The state estimates don’t say why people dropped out of the count.
Ohio’s unemployment rate fell from 4.9% in February 2025 to 3.3% in August 2026, while the U.S. rate barely moved
Share of the labor force out of work and looking, Ohio and the U.S., seasonally adjusted, each month from January 1990 through August 2026. The bureau skipped October 2025, when the federal shutdown stopped its survey, so that month has no point.
Ohio’s yearly rate was above the nation’s every year from 2003 through 2010, again from 2016 through 2020, and every year from 2022 through 2025. The monthly rate has been under the U.S. rate since February 2026, a gap the bureau counted as statistically significant in August, and that turn is what moved Ohio down the State Distress Index (see how it ranks).
Unemployment is highest in Pike County and lowest in Holmes County
| County | Rate |
|---|---|
| Pike (Waverly) | 5.7% |
| Meigs (Pomeroy) | 5.6% |
| Noble (Caldwell) | 5.4% |
| Scioto (Portsmouth) | 5.3% |
| Trumbull (Warren) | 5.3% |
| Hamilton (Cincinnati) | 3.7% |
| Franklin (Columbus) | 3.5% |
| Cuyahoga (Cleveland) | 3.5% |
| Holmes (Millersburg) | 2.6% |
Average unemployment rate over the 11 months the bureau published from September 2025 through August 2026 (it published none for October 2025), not adjusted for seasonal swings; the averages are ours. Shown: the five highest of Ohio’s 88 counties (Scioto and Trumbull share a rate), the three biggest counties, and Holmes, the lowest, with county seats in parentheses. We use the average because the bureau’s August county rates are preliminary. Source: U.S. Bureau of Labor Statistics.
Ohio’s minimum wage rises with prices every January
Ohio’s minimum wage is $11.00 an hour in 2026 for most workers and $5.50 plus tips for tipped workers, up 2.8% from 2025. Voters added it to the state constitution in 2006, with a raise each Jan. 1 to match inflation. Businesses with yearly gross receipts of $405,000 or less, and workers 14 and 15 years old, are held to the federal minimum, $7.25 (Ohio’s commerce department). The state’s 2027 poster lists $11.40 (see what to watch). The poorest and most distressed counties →
Which Ohio counties are poorest, and which are most distressed?
Athens County, home of Ohio University, is the poorest by the Census Bureau’s Small Area Income and Poverty Estimates: in 2024, 25.3% of its people were below the poverty line, the highest rate of Ohio’s 88 counties. The most distressed on our County Distress Index, which measures how strained household budgets are in every U.S. county, is Scioto County, on the Ohio River, at 92, followed by its neighbors Pike and Adams. No Ohio county ranks among the 100 most distressed in the country (see the national list), while Mercer, Delaware, Putnam, Geauga and Union rank among the 100 least distressed. Mercer County, in western Ohio, is the state’s least distressed and the 40th least distressed of all 3,144.
Ohio’s distress is deepest in the Appalachian south and around Youngstown and Toledo, and lightest in the Columbus suburbs and the western farm counties
Each of Ohio’s 88 counties colored by its County Distress Index score, 0 to 100, with data through August 2026.
Loading the county map…
The county map could not be loaded. Every county is in the lists on this page.
Most distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 1 | Scioto | 92 | 19.1% |
| 2 | Pike | 90 | 19.1% |
| 3 | Adams | 88 | 17.4% |
| 4 | Jackson | 88 | 15.5% |
| 5 | Mahoning | 81 | 19.3% |
| 6 | Ross | 81 | 13.4% |
| 7 | Gallia | 80 | 20.1% |
| 8 | Lucas | 79 | 16.8% |
| 9 | Meigs | 79 | 14.9% |
| 10 | Clark | 78 | 14.1% |
Least distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 84 | Union | 2 | 5.3% |
| 85 | Geauga | 2 | 5.7% |
| 86 | Delaware | 1 | 4.3% |
| 87 | Putnam | 1 | 6.0% |
| 88 | Mercer | 1 | 8.0% |
Rank among Ohio’s counties, 1 = most distressed. We rank on unrounded scores, so counties showing the same score, such as Mahoning and Ross, can hold different ranks. Poverty is the Census Bureau’s 2024 rate for each county.
Every county, by score
Scioto, Pike, Adams, Jackson, Ross and Gallia in the southern hills, and Mahoning, home to Youngstown, are the only counties that score 80 or more. Together they hold 4.2% of Ohioans. Of the 31 counties that score 60 or more, 23 are on the Appalachian Regional Commission’s list of Appalachian counties (see Appalachian Ohio).
11 score 70–79
Lucas, Meigs, Clark, Lawrence, Ashtabula, Trumbull, Marion, Cuyahoga, Jefferson, Athens, Montgomery
22 score 50–69
Columbiana, Belmont, Vinton, Brown, Harrison, Fayette, Guernsey, Coshocton, Perry, Hamilton, Franklin, Hocking, Muskingum, Richland, Allen, Morgan, Summit, Crawford, Highland, Huron, Clinton, Hardin
Athens has Ohio’s highest poverty rate but not its highest distress
Our County Distress Index gives five parts equal weight: late payments; collections and bankruptcy; jobs; renters’ housing costs; and a fifth made from the poverty rate, child poverty, median household income, disability and the share without health insurance. Poverty is one of many inputs, so the poverty and distress rankings part ways. Athens County has the state’s highest poverty rate and its 3rd lowest median household income, $54,806, yet ranks 17th of 88 on distress: its renters’ costs score high, while its late payments and collections score below the middle. Athens is home to Ohio University, and the Census Bureau notes that college students living off campus are counted in poverty estimates, which can lift a college town’s rate. In its 2012 to 2016 survey figures, the bureau found that leaving those students out cut Athens County’s poverty rate from 31.2% to 22.2% (Census Bureau); it has published no such figure for 2024. Ross County, around Chillicothe, runs the other way: its poverty rate, 13.4%, is 34th highest in the state, yet it scores 81, the same as Mahoning, with collections and late-payment scores among Ohio’s highest. Scioto and Pike, tied for 4th highest on poverty, are the two most distressed. Lists built on the bureau’s American Community Survey, or on an older year, can name a different poorest county; every county rate here is from the 2024 Small Area Income and Poverty Estimates.
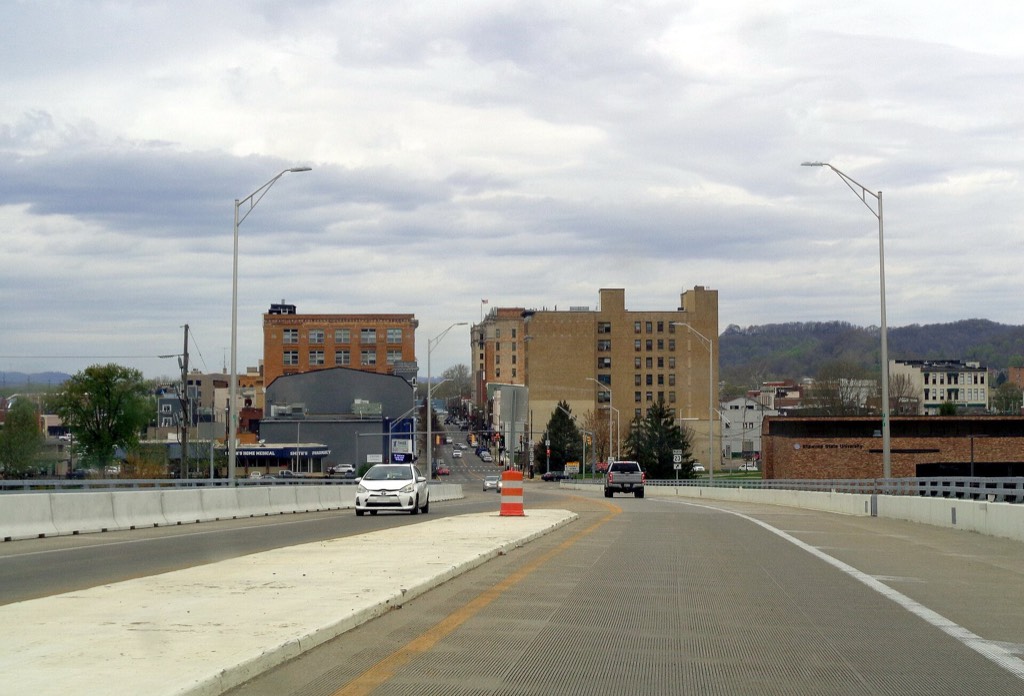
Downtown Portsmouth, the seat of Scioto County, seen from the U.S. Grant Bridge. Scioto, Ohio’s most distressed county at 92, counted 74,008 residents in the 2020 Census, 85% of the 86,565 it counted in 1940 (Census Bureau; the percentage is our calculation).
Source: U.S. Census Bureau. Photo: Vasiliymeshko, Wikimedia Commons, CC BY 4.0.

Appalachian Ohio and the three biggest counties
To see where strain sits once each county counts by its population, we grouped Ohio’s counties. The 32 that the Appalachian Regional Commission lists as Appalachian, across the south and east, hold 16.7% of Ohioans and average 65, and 23 of the 31 counties scoring 60 or more are among them. Their strain leans on jobs: their jobs part averages 63. Cuyahoga County, home to Cleveland, scores 72; Franklin, home to Columbus, 60; and Hamilton, home to Cincinnati, 61. In those three the jobs parts are low, 29 to 39, and the renters’ parts high, 76 to 80. The 14 other counties of 150,000 people or more average 44, and the remaining 39 smaller counties, mostly in the west and north, 36. These averages locate the strain; they don’t explain it.
American Default Research, County Distress Index; populations from the Census figures the index uses; Appalachian counties from the Appalachian Regional Commission. We chose the groups and computed their averages.
Is Ohio a poor state? Poorer than most, and above the U.S. poverty rate since 2007
Somewhat. In 2024, 12.6% of Ohioans lived below the poverty line, tied for 16th highest among the 50 states and D.C. The U.S. rate was 12.1%. Ohio’s typical household earned $72,259, 12th lowest, against $81,604 nationwide (Census Bureau, Small Area Income and Poverty Estimates). Spread across every resident, Ohioans’ total income came to $64,464 a person, 14th lowest (U.S. Bureau of Economic Analysis).
Residents in poverty
12.6%
U.S. 12.1%
Tied for 16th highest of the states and D.C. for 2024
Children in poverty
16.4%
U.S. 15.5%
17th highest of the states and D.C. for 2024
Median household income
$72,259
U.S. $81,604
12th lowest of the states and D.C. for 2024
Ohio’s poverty rate ran below the U.S. rate through 2006 and has been above it in every Census estimate since 2007
Ohioans and all Americans below the poverty line, in percent, 1989 to 2024. The bureau made no state estimates for 1990, 1991, 1992 or 1994.
Two Census measures, two poverty rates
Ohio’s Legislative Service Commission puts the state’s 2024 poverty rate at 12.7%, the 14th highest of the 50 states, using the Census Bureau’s American Community Survey. This page uses the bureau’s Small Area Income and Poverty Estimates, which it makes every year for each state and county, so the state and county rates here share one source. Programs that decide who qualifies for help use yet another yardstick, the federal poverty guideline, which the U.S. Department of Health and Human Services sets each year.
The richest counties are among the least distressed
By median household income, Delaware County, north of Columbus, was Ohio’s richest in 2024, at $136,215, followed by Union, at $119,133, and Warren, between Cincinnati and Dayton, at $113,333 (Census Bureau). Delaware and Union are two of the five least distressed counties, and Warren ranks 80th of 88. In Cuyahoga County, home to Cleveland, the typical household earned $66,081. The poorest and most distressed counties →
What changed in Ohio in the past year
-
April 24, 2026
A parts maker put off part of two plant closings in northwest Ohio
First Brands Group told the state on Feb. 27 that it would close its TMD plants in Tiffin, in Seneca County, and Bowling Green, in Wood County, for good on April 30, affecting 407 and 302 workers. On April 24 it said it now expected to keep 345 of the Tiffin workers and 263 in Bowling Green through May 31 while it tried to sell some of its U.S. plants; the others would leave on the original date. These are the company’s own notices; we didn’t check what happened after May 31.
First Brands Group notices to Ohio’s job and family services department: Tiffin; Bowling Green
-
April 1, 2026
Regulators cut AEP Ohio’s yearly revenue under new delivery rates
The Public Utilities Commission of Ohio approved a settlement giving AEP Ohio $11 million more a year in base delivery revenue, against the $97 million it asked for. With about $105 million returned to customers over 18 months for a federal tax change, the company’s yearly revenue falls by about $58.7 million. The order covers the part of the bill that pays for poles, wires and upkeep, not the power itself.
-
March 20, 2026
A law limiting school property tax growth took effect
The governor signed House Bill 186 on Dec. 19, 2025, and it took effect March 20, 2026. As the legislature describes it, the law lets school district property taxes that are held at a minimum rate, known as the floor, be reduced so they grow no faster than inflation, and it changes property tax reductions for homes. The bill’s official page gives no estimate of what it saves a household.
-
Jan. 25, 2026
Fewer noncitizens qualify for SNAP under the federal budget law
The federal budget law signed July 4, 2025, narrowed which noncitizens can get SNAP, the federal food benefit. Ohio’s job and family services department ended, from Nov. 1, 2025, benefits for noncitizens who no longer qualified, but its shutdown-era benefit runs put many of them back on; its Dec. 4 notice to caseworkers said its system would apply the change from Jan. 25, 2026, with some cases ending Feb. 28. Nothing changed for U.S. citizens (see SNAP).
Ohio Department of Job and Family Services, Food Assistance Change Transmittal 106-A, Dec. 4, 2025
-
Jan. 1, 2026
The minimum wage rose with inflation
Ohio’s minimum wage went from $10.70 to $11.00 an hour, and to $5.50 plus tips for tipped workers, a 2.8% increase set by the yearly inflation adjustment in Ohio’s constitution (see the minimum wage).
Ohio commerce department, Dec. 31, 2025; U.S. Department of Labor state table, July 1, 2026
-
Nov. 19, 2025
New delivery rates for FirstEnergy’s three Ohio utilities
The utility commission set delivery rates that raise the three companies’ combined yearly revenue by about $34 million, against the $190 million they sought. Cleveland Electric Illuminating’s revenue rises by $75.9 million, while Ohio Edison’s falls by $17.4 million and Toledo Edison’s by $24.4 million. The commission told the utilities to file rates carrying out the order; we didn’t confirm the date they took effect. FirstEnergy has since asked for more (see what to watch).
Is Ohio cheap to live in? Rent is well below the U.S. median
For housing, yes. Half of Ohio’s renters paid less than $1,034 a month in the Census Bureau’s 2020 to 2024 survey, 12th lowest among the 50 states and D.C., against a U.S. median of $1,413. A full year of that rent equals 17.2% of what the typical Ohio household earned in 2024; for the U.S. it equals 20.8% (our calculation). We hold no prices for food, gas or electricity and no figures for single cities, so we can’t rank Ohio’s whole cost of living.
Median rent, a month
$1,034
U.S. $1,413
12th lowest of the states and D.C. for 2020 to 2024
Renters spending at least 30% of income on housing
42.4%
U.S. 47.6%
15th lowest of the states and D.C. for 2020 to 2024
Homeowners spending at least 30% of income on housing
17.7%
U.S. 22.5%
Tied for 6th lowest of the states and D.C. for 2020 to 2024
On renters’ housing costs, Ohio sits in the middle of the states. In 2024, 24.6% of Ohio renter households paid half or more of their income for rent and utilities, 25th highest among the states. The U.S. share was 26.1% that year. Ohio’s share has been under the national share in every Census estimate since 2011.
Every year since 2011, a smaller share of Ohio renters than of all U.S. renters has spent half their income on housing
Renter households whose rent and utilities take half or more of their income, Ohio and the U.S., in percent, from the Census Bureau’s one-year surveys, 2005 to 2024. The bureau released no standard one-year figures for 2020.
What MIT puts a bare-bones Ohio budget at
The MIT Living Wage Calculator estimates that one adult with no children in Ohio needs $43,674 a year before taxes for basic needs. That is 9th lowest among the 50 states and D.C. in 2025 dollars. Two working parents with two children need $113,101. MIT counts only necessities, with nothing put aside.
Electric bills depend on the utility. The state’s utility commission set new delivery rates for FirstEnergy’s three Ohio companies in November 2025 and for AEP Ohio in April 2026, and FirstEnergy has asked for more from 2027 (see what changed).
Rent costs less in Ohio than in three of its five neighbors
Kentucky and West Virginia are the two neighbors where median rent is lower. Set against income, rent takes a smaller share in Ohio than in any neighbor but West Virginia, where it is tied.
| State | Rent, a month | Median household income | Rent as share of income |
|---|---|---|---|
| Pennsylvania Rent as share of income 18.7% | $1,209 Median household income $77,532 | $77,532 | 18.7% |
| Michigan Rent as share of income 18.7% | $1,129 Median household income $72,336 | $72,336 | 18.7% |
| Indiana Rent as share of income 17.7% | $1,062 Median household income $71,958 | $71,958 | 17.7% |
| Ohio Rent as share of income 17.2% | $1,034 Median household income $72,259 | $72,259 | 17.2% |
| Kentucky Rent as share of income 18.0% | $967 Median household income $64,481 | $64,481 | 18.0% |
| West Virginia Rent as share of income 17.2% | $872 Median household income $60,662 | $60,662 | 17.2% |
Rent: median gross rent a month over 2020 to 2024 (Census Bureau, American Community Survey). Income: median household income in 2024 (Census Bureau, Small Area Income and Poverty Estimates). The share is ours: a year of median rent divided by median household income. Rent and housing costs by state →
Are Ohioans behind on their bills? A little more often than Americans, though they owe less
A little more than the country. Early in 2025, 17.4% of Ohioans with a credit record had a debt 90 or more days late. That was 20th highest among the 50 states and D.C. in the Philadelphia Fed figures. The U.S. share was 17.2%, our population-weighted average of the states (Federal Reserve Bank of Philadelphia). That comes with lighter borrowing: at the end of 2025 Ohioans with a credit report owed $46,780 each in household debt, 7th lowest among the states, against $63,200 nationwide (Federal Reserve Bank of New York). These are households’ debts; the state government’s own borrowing isn’t counted.
Counting from the largest share among the 50 states and D.C., Ohio is 17th on collections, 18th on cards, tied for 21st on car loans and tied for 23rd on mortgages. Each U.S. bar is our average of the states, with bigger states weighted more.
Card trouble has grown since 2019: the share of Ohio card borrowers 90 or more days late went from 9.5% at the end of 2019 to 13.8% early in 2025. Collections moved the other way, from 23.1% to a low of 13.6% at the end of 2023, and have edged up since. More of that drop came after early 2022, when the share stood at 18.9%, than before it. That stretch is when the three big credit bureaus stopped reporting many medical debts, and a debt left off a credit report hasn’t necessarily been paid. Nationwide, the share of people with a medical collection on their report went from about 14% in March 2022 to about 5% in June 2023 (Consumer Financial Protection Bureau).
Counted in dollars, a smaller share of Ohio card balances is late than across the U.S.
The Federal Reserve Bank of New York measures the share of dollars owed that is 90 or more days late, not the share of people. At the end of 2025, 11.1% of Ohio’s credit card balances were that far behind, tied for 29th highest among the 50 states and D.C., against 12.4% for the U.S., and up from 7.4% at the end of 2019. Auto and mortgage dollars ran about level with the nation’s.
| Loan type | Ohio | U.S. | Ohio 2019 | U.S. 2019 |
|---|---|---|---|---|
| Credit card | 11.1% End of 2025 U.S. 12.4% Ohio 2019 7.4% · U.S. 2019 8.1% | 12.4% | 7.4% | 8.1% |
| Auto loan | 5.3% End of 2025 U.S. 5.2% Ohio 2019 4.6% · U.S. 2019 4.9% | 5.2% | 4.6% | 4.9% |
| Mortgage | 1.0% End of 2025 U.S. 0.9% Ohio 2019 0.9% · U.S. 2019 1.0% | 0.9% | 0.9% | 1.0% |
Share of balances 90 or more days past due at the end of 2025 and the end of 2019. Source: Federal Reserve Bank of New York, Consumer Credit Panel / Equifax. It counts dollars, not people, so it doesn’t line up with the Philadelphia Fed chart above, and it includes old debts lenders have written off but still report.
Early mortgage trouble is a bit more common in Ohio
In September 2025, 1.8% of Ohio mortgages were 30 to 89 days late, tied for 16th highest among the 50 states and D.C., against 1.6% nationwide (Consumer Financial Protection Bureau). Few Ohio owners are close to owing more than the home is worth. In the second quarter of 2026, just 3.6% of Ohio mortgages had under 10% equity, compared with 4.7% nationally (Federal Housing Finance Agency).
| Measure | Ohio | U.S. | Rank |
|---|---|---|---|
| Household debt per person with a credit report, end of 2025 7th lowest | $46,780 U.S. $63,200 | $63,200 | 7th lowest |
| Card balances per person with a credit report, end of 2025 13th lowest | $3,560 U.S. $4,350 | $4,350 | 13th lowest |
Rank among the 50 states and D.C. Debt per person adds every kind of household debt together (Federal Reserve Bank of New York). Late payments in every state →
Bankruptcy in Ohio: more filings per person than in most states, and fewer under Chapter 13
Ohioans filed 26,110 bankruptcy cases in 2025, 219.4 for every 100,000 residents (2025 population), 13th highest among the 50 states and D.C., against 166.3 nationwide (Administrative Office of the U.S. Courts). Filings rose 5.4% from 2024, less than the 11.1% rise across the country. They have climbed every year since 2022, the year with the fewest in U.S. Courts records since 2001, and 2025 brought the most since 2020, when Ohioans filed 26,751.
Only 23.5% of Ohio’s cases in 2025 were filed under Chapter 13, 20th lowest among the states, against 35.9% nationally. Chapter 13 sets up a court-approved plan, usually three to five years, to repay part of the debts, and filers usually keep their property. In Chapter 7, the kind most Ohioans file, many debts are wiped out and property the law doesn’t protect can be sold.
| Year | Filings |
|---|---|
| 2005 | 135,640 |
| 2010 | 70,641 |
| 2019 | 37,411 |
| 2020 | 26,751 |
| 2021 | 20,818 |
| 2022 | 18,262 |
| 2023 | 21,140 |
| 2024 | 24,769 |
| 2025 | 26,110 |
Cases under every chapter in Ohio’s two federal bankruptcy courts, for the Northern and Southern districts, in selected years and each year since 2019. Administrative Office of the U.S. Courts records run from 2001 to 2025, missing 2004; the peak, 2005, is the year the stricter federal bankruptcy law took effect, in October. Source: Administrative Office of the U.S. Courts, Table F-2. Bankruptcy filings in every state →
SNAP in Ohio: the count has dropped since late 2025
SNAP, the federal food benefit once known as food stamps, reached 1,317,208 Ohioans in June 2026, by the U.S. Department of Agriculture’s count. That is 11.1% of the state’s 2025 population, tied for 16th highest among the 50 states and D.C., against 10.6% nationwide. The count was 119,904 fewer people than in June 2025, a drop of 8.3%, and fewer than the 1,374,426 Ohio averaged from October 2019 to February 2020, before the pandemic.
People getting SNAP
1,317,208
June 2026, U.S. Department of Agriculture
Share of residents getting SNAP
11.1%
U.S. 10.6%
Tied for 16th highest of the states and D.C. for June 2026 (2025 population)
Change from a year earlier
−8.3%
June 2025 to June 2026
Nearly all of the fall came after October 2025. The count held close to its October level of 1,426,605 for most of the year before, then dropped by 40,684 in November alone and by 109,397 in all by June 2026 (U.S. Department of Agriculture; the differences are our calculation).
Two federal changes came in the same months
During the federal shutdown, Ohio’s job and family services department said on Nov. 10, 2025, that federal guidance cut each household’s November maximum by 35%. Nearly all recipients would get less than 65% of their usual benefit (Nov. 10, 2025 release). Then the 2025 federal budget law narrowed which noncitizens qualify, a change Ohio first applied in November 2025 and fully from Jan. 25, 2026 (see what changed). We found no source that splits the drop between the two, and a smaller count isn’t proof of less need: the newest Census poverty figures are for 2024. Is Ohio poor? →
How foreclosure works in Ohio
Every home foreclosure in Ohio goes before a judge in the Court of Common Pleas of the county where the home sits; the state has no foreclosure without a court. Federal servicing rules generally keep a lender from starting foreclosure on a home the owner lives in until the loan is more than 120 days behind (12 CFR 1024.41). Once served with the lender’s complaint, the owner ordinarily has 28 days to file an answer (Ohio Civil Rule 12).
If the court orders a sale, notice must run in a local newspaper once a week for at least three weeks in a row. Written notice of the date goes to the parties in the case (Ohio Revised Code § 2329.26). Until the court confirms the sale, the owner can still redeem the home by paying the full judgment, interest and costs (§ 2329.33). The lender can seek a judgment for any balance the sale didn’t cover, but on a home for one or two families it can’t collect that balance more than two years after the court confirms the sale (§ 2329.08).
The Supreme Court of Ohio offers courts a model for foreclosure mediation, and each court decides whether and how to use it, so mediation varies from county to county (Supreme Court of Ohio). Cuyahoga County’s Court of Common Pleas, for one, runs a free foreclosure mediation program that homeowners can ask to join with a request form (court form). Save the Dream Ohio, the state’s program paid for by the federal Homeowner Assistance Fund, stopped taking applications for mortgage help on Oct. 31, 2023 (Ohio Housing Finance Agency).
- Goes through a court
- Always
- Time to answer the complaint
- 28 days
- Sale advertised beforehand
- 3 weeks
- Redeem the home
- Until the sale is confirmed
- Lender can seek the balance left after the sale
- Yes
- Mediation
- Up to each court
What the law says for a home you live in. Sources: Ohio Revised Code §§ 2323.07, 2329.08, 2329.26 and 2329.33; Ohio Civil Rule 12; federal rule 12 CFR 1024.41; Supreme Court of Ohio. How foreclosure works in Ohio →
Ohio was awarded $280.8 million from the federal Homeowner Assistance Fund and had helped 34,755 households with it through early 2026 (U.S. Treasury).
Ohio mortgage complaints: what homeowners tell the CFPB
Since 2012, the Consumer Financial Protection Bureau has received 11,848 mortgage complaints from Ohio. The most common issues are trouble during the payment process (2,859); loan modification, collection or foreclosure (2,757); and problems with loan servicing, payments or escrow (2,333).
- Oct. 5, 2026 Bank of America Payment process: paying off the loan In progress
- Oct. 3, 2026 Freedom Financial Network Payment process In progress
- Oct. 3, 2026 First Merchants Corporation Payment process: private mortgage insurance In progress
- Oct. 3, 2026 Dovenmuehle Mortgage Payment process: private mortgage insurance Closed with explanation
- Oct. 1, 2026 Planet Home Lending Struggling to pay: trouble reaching the company about a modification, forbearance or foreclosure In progress
- Oct. 1, 2026 Huntington Bank Payment process: trouble reaching the company to fix a problem with the loan Closed with explanation
- Sept. 30, 2026 Selene Finance Struggling to pay: applying for a modification, forbearance, short sale or deed-in-lieu In progress
- Sept. 30, 2026 MidFirst Bank Struggling to pay: trouble reaching the company about a modification, forbearance or foreclosure Closed with explanation
- Sept. 29, 2026 Shellpoint / NewRez Payment process In progress
- Sept. 29, 2026 Wells Fargo Struggling to pay: an existing modification, forbearance or other relief In progress
Ohio’s 10 newest complaints about paying a mortgage or getting help with one, newest first, from the Consumer Financial Protection Bureau’s public database as of Oct. 14, 2026. Complaints about taking out a new loan, and any naming a credit bureau, are left out. Each is one person’s account, which the bureau doesn’t verify, and a complaint isn’t proof the company did anything wrong. Every Ohio mortgage complaint at the Consumer Financial Protection Bureau →
What to watch before the next edition
Coming up before the next edition, nearest first: a jobs report that could revise Ohio’s low August rate, a Medicaid work rule, the next minimum wage and a request for higher electric rates.
-
Oct. 20, 2026
September unemployment rates for the states
The Bureau of Labor Statistics is scheduled to publish state unemployment rates for September. Ohio’s August rate, 3.3%, was its lowest in the bureau’s figures going back to 1976, and it is preliminary, so the next release can revise it.
Bureau of Labor Statistics, State Employment and Unemployment, August 2026 release
-
Jan. 1, 2027
A Medicaid work rule for adults covered through the expansion
Adults 19 to 64 who have Medicaid because their income is at or below 138% of the federal poverty level will have to show 80 hours a month of work, school, job training or community service unless they are exempt, Ohio’s Medicaid department says. Renewals for them move from once a year to every six months.
-
Jan. 1, 2027
The minimum wage is set to rise again
The commerce department’s 2027 poster lists a minimum wage of $11.40 an hour, and $5.70 plus tips for tipped workers. Employers grossing less than $419,000 a year, and workers under 16, stay at the federal $7.25.
-
From 2027, if approved
FirstEnergy’s request for higher delivery rates
FirstEnergy’s three Ohio utilities have asked the utility commission to raise delivery rates in three yearly steps from 2027 (case 26-0347-EL-AIR). The Office of the Ohio Consumers’ Counsel, the state’s advocate for residential customers, estimates from the companies’ filing that each step would add about $4.26 to $5.30 a month for a home using 1,000 kilowatt-hours. Hearing dates hadn’t been set as of Oct. 17.
Office of the Ohio Consumers’ Counsel, FirstEnergy rate case
Where Ohio ranks highest and lowest
| Measure | Ohio | U.S. | Rank | Latest data |
|---|---|---|---|---|
| Bankruptcy filings per 100,000 residents (2025 population) 13th highest · 2025 | 219.4 U.S. 166.3 | 166.3 | 13th highest | 2025 |
| Share of income from government benefits Tied for 13th highest · 2024 | 21.1% U.S. 18.3% | 18.3% | Tied for 13th highest | 2024 |
| Residents with a disability Tied for 15th highest · 2024* | 14.4% U.S. 13.3% | 13.3% | Tied for 15th highest | 2024* |
| Residents getting SNAP food benefits (2025 population) Tied for 16th highest · June 2026 | 11.1% U.S. 10.6% | 10.6% | Tied for 16th highest | June 2026 |
| Mortgages 30 to 89 days late Tied for 16th highest · Sept. 2025 | 1.8% U.S. 1.6% | 1.6% | Tied for 16th highest | Sept. 2025 |
| Residents in poverty Tied for 16th highest · 2024 | 12.6% U.S. 12.1% | 12.1% | Tied for 16th highest | 2024 |
| People with a debt in collections 17th highest · Early 2025 | 14.6% U.S. 13.2% | 13.2% | 17th highest | Early 2025 |
| Children in poverty 17th highest · 2024 | 16.4% U.S. 15.5% | 15.5% | 17th highest | 2024 |
| Card borrowers 90+ days late 18th highest · Early 2025 | 13.8% U.S. 13.5% | 13.5% | 18th highest | Early 2025 |
| Unemployment rate, three-month average Tied for 15th lowest · June–August 2026 | 3.4% U.S. 4.1% | 4.1% | Tied for 15th lowest | June–August 2026 |
| Median household income 12th lowest · 2024 | $72,259 U.S. $81,604 | $81,604 | 12th lowest | 2024 |
| Median rent, a month 12th lowest · 2024* | $1,034 U.S. $1,413 | $1,413 | 12th lowest | 2024* |
| Income per person 14th lowest · 2024 | $64,464 U.S. $73,204 | $73,204 | 14th lowest | 2024 |
| Household debt per person with a credit report 7th lowest · End of 2025 | $46,780 U.S. $63,200 | $63,200 | 7th lowest | End of 2025 |
Each rank counts across the 50 states and D.C., from the top or from the bottom as the row says; states that print the same value share a rank. * Census Bureau five-year survey, 2020 to 2024. Collections and card borrowers count people with a credit record (Federal Reserve Bank of Philadelphia); their U.S. figures are our population-weighted average of the states. Debt per person: Federal Reserve Bank of New York. Sources and method names where each row comes from. Download the table: CSV.
Questions about Ohio
Is Ohio a poor state?
Somewhat poorer than most. In 2024 the Census Bureau put Ohio’s poverty rate at 12.6%, against 12.1% for the U.S., and its median household income at $72,259, against $81,604 (Small Area Income and Poverty Estimates). On our State Distress Index, a measure of strain on household finances, it ranks 28th of the 50 states and D.C. Is Ohio poor? →
What is the poorest county in Ohio?
Athens County, home to Ohio University: 25.3% of its residents lived below the poverty line in 2024, the highest rate of Ohio’s 88 counties (U.S. Census Bureau, Small Area Income and Poverty Estimates). Scioto County, on the Ohio River, is the most distressed on our County Distress Index. The poorest and most distressed counties →
What is Ohio’s unemployment rate?
It was 3.3% in August 2026, against 4.1% for the U.S., and the lowest in the U.S. Bureau of Labor Statistics’ figures for Ohio back to 1976; August’s figure is preliminary. The rate fell mostly because the labor force shrank: from February 2025 to August 2026 it lost 112,864 people, and the number with jobs fell by 17,990. Jobs and unemployment →
What is the minimum wage in Ohio?
It is $11.00 an hour in 2026 for most workers and $5.50 plus tips for tipped workers, and the state’s 2027 poster lists $11.40. Businesses with yearly gross receipts of $405,000 or less, and workers 14 and 15 years old, are held to the federal $7.25 (Ohio’s commerce department). Ohio’s minimum wage →
Is Ohio a judicial foreclosure state?
Yes. Every home foreclosure goes through the Court of Common Pleas in the county where the home sits, and the owner can redeem the home by paying the full judgment until the court confirms the sale (Ohio Revised Code § 2329.33). How foreclosure works in Ohio →
Is there still help paying a mortgage in Ohio?
Save the Dream Ohio, the state’s federally funded mortgage help program, stopped taking applications for mortgage help on Oct. 31, 2023 (Ohio Housing Finance Agency). Housing counselors approved by the U.S. Department of Housing and Urban Development still help at little or no cost, and five regional legal aid groups cover all 88 counties. Free help in Ohio →
Cite or reuse Ohio’s data
Quote or reuse any figure here, crediting American Default Research.
State Distress Index
Ohio
28thmost distressed state
of the 50 states and D.C.
More distressed than 46% of the other states and D.C.
Ohio is the 28th most distressed of the 50 states and D.C. on American Default Research’s State Distress Index. It was tied for 13th in the first quarter of 2025. Its unemployment rate fell to 3.3% in August 2026 (U.S. Bureau of Labor Statistics). The Census Bureau put Ohio’s 2024 poverty rate at 12.6%, against 12.1% for the U.S. Scioto County is the state’s most distressed county, with a County Distress Index score of 92.
Reporters who want an interview or a custom cut of the data can write to press@americandefault.org
Sources and method
We gather the data, run the numbers and research each state ourselves.
This edition: October 2026 · Next edition expected March 2027
- Unemployment rates by month and year: Ohio, its counties, the nationU.S. Bureau of Labor Statistics, Local Area Unemployment Statistics and Current Population SurveyJan. 1976 to Aug. 2026
- Ohio’s labor force, employment and unemployed countU.S. Bureau of Labor Statistics, Local Area Unemployment Statistics, seasonally adjusted state seriesFeb. 2025 and Aug. 2026
- Poverty and median household income for Ohio and each countyCensus Bureau, Small Area Income and Poverty Estimates1989 to 2024
- Poverty on the American Community SurveyOhio Legislative Service Commission, Poverty in Ohio, June 20262024
- College students in poverty estimatesCensus BureauOct. 2018
- Renter households paying half or more of income for housingCensus Bureau, American Community Survey, one-year estimates2005 to 2024
- Rent, housing costs and disabilityCensus Bureau, American Community Survey, five-year estimates2020 to 2024
- Scioto County population by censusCensus Bureau, decennial census1940 and 2020
- Income per person and benefit incomeU.S. Bureau of Economic Analysis2024
- Late payments and collectionsFederal Reserve Bank of Philadelphia, Consumer Credit Explorerend of 2019 to early 2025
- Household debt and dollars behindFederal Reserve Bank of New York, Consumer Credit Panel / Equifaxend of 2019 and end of 2025
- Mortgages with little equityFederal Housing Finance Agency, National Mortgage Databasesecond quarter of 2026
- Mortgages 30 to 89 days late; mortgage complaints; medical debts on credit reportsConsumer Financial Protection Bureau: Mortgage Performance Trends; complaint database; Recent changes in medical collections on consumer credit recordsSept. 2025; Oct. 14, 2026; March 2022 to June 2023
- Bankruptcy filingsAdministrative Office of the U.S. Courts, Table F-22001 to 2025
- SNAPU.S. Department of Agriculture Food and Nutrition Administration; Ohio’s job and family services departmentthrough June 2026; Nov. 2025
- Cost of getting byMIT Living Wage Calculator2025 dollars
- Minimum wageOhio commerce department, Dec. 31, 2025; 2027 poster2026 and 2027
- Mortgage help fundU.S. Treasury, Homeowner Assistance Fund; Ohio Housing Finance Agencythrough early 2026
- Foreclosure lawOhio Revised Code, Chapter 2329; § 2323.07; Ohio Rules of Civil Procedure; Supreme Court of Ohio, foreclosure mediation; Cuyahoga County Court of Common Pleas; 12 CFR 1024.41as of 2026
- Poverty guidelineU.S. Department of Health and Human Services2026
- Appalachian countiesAppalachian Regional Commissionas of Oct. 2026
- Housing counselorsU.S. Department of Housing and Urban DevelopmentOctober 2026
- What changed and what to watchFirst Brands Group notices, Public Utilities Commission of Ohio, April 1, 2026, Public Utilities Commission of Ohio, Nov. 19, 2025, Ohio Legislature, House Bill 186, Food Assistance Change Transmittal 106-A, Ohio’s Medicaid department, Office of the Ohio Consumers’ Counsel, Bureau of Labor Statistics release. Each item links the page it was read on (see what changed)Nov. 2025 to 2027
- PhotoVasiliymeshko, via Wikimedia Commons, CC BY 4.0April 2024
The score has four parts with equal weight: jobs, late payments, collections and bankruptcy, and renters’ housing costs. For each state we average the four, then score it by the percentage of the other 49 states and D.C. whose average is lower, so a state scoring 80 is more distressed than 80% of the rest. The full method →
We write with AI tools, and Ross Kilburn checks and reviews every page before it's published.
Get the next Ohio edition by email
One email each time a new Ohio edition is out; the next is expected in March 2027. Unsubscribe anytime.
Thanks, that helps.