North Carolina: low unemployment, yet 15.6% of card borrowers seriously behind, 13th highest
Each state is shaded by how distressed its households are, from green (least) to red (most), with data through September 2026. North Carolina scores 44 out of 100.
In early 2025, 10.9% of North Carolina's car-loan borrowers were 90 or more days behind, the 8th highest share in the country. Of the bankruptcies filed in the state in 2025, 63.5% were Chapter 13 repayment plans, the 4th highest share nationally. Low unemployment is what keeps the score down; the jobs part is the lowest of the state's four. Edgecombe, Halifax and Robeson counties, in the east, are in the nation's top 100 for distress; Camden County, in the northeast corner, is the least distressed in the state.
- Score
- 44/100
- Data through
- September 2026
- Edition
- October 2026
Next edition expected March 2027
How North Carolina ranks among the states
North Carolina is a middle-of-the-pack state on distress whose borrowers still fall badly behind more often than most. In early 2025, 10.9% of its car-loan borrowers were 90 or more days late, 8th highest among the 50 states and D.C., against 8.5% for the country (Federal Reserve Bank of Philadelphia). Mortgages are the exception: 1.1% of mortgage borrowers were that far behind, against 1.2% nationwide. Low unemployment is what keeps the score down. The jobs part, at 34, is the state’s lowest, and unemployment has run under the U.S. rate every month with data since May 2023 (see jobs).
What drives the score
Each part below runs from 0 to 100 and is built from measures that place North Carolina among the states. The State Distress Index score is not the average of the four. North Carolina’s parts average 46; the score asks how many of the other 49 states and D.C. have a lower average. The answer is 22 of those 50, or 44%, so North Carolina scores 44. On the same rule, a state with a score of 80 is more distressed than 80% of the rest.
- Late payments70In early 2025, 15.6% of North Carolina card borrowers and 10.9% of car-loan borrowers were at least 90 days behind, against 13.5% and 8.5% nationwide.
- Renters’ housing costs34Renter households spending half their income or more on rent and utilities made up 24.9% of North Carolina renters in 2024, against 26.1% for the U.S.; in 2019 the state’s share was 21.7%.
- Collections and bankruptcy46More people have a debt in collections than nationwide, 15.2% against 13.2% in early 2025, but fewer file for bankruptcy: 87.9 filings per 100,000 residents in 2025 (2025 population), against 166.3.
- Jobs34Unemployment averaged 3.6% from June through August 2026, under the U.S. average of 4.1%.
North Carolina beside its four neighbors
Georgia and South Carolina, the two neighbors to the south, both score far higher. Tennessee scores a few points above North Carolina and Virginia a few points below, so Virginia is the only neighbor with a lower score.
State Distress Index score, 0 to 100. Of the 50 states and D.C., Georgia is the 11th most distressed and South Carolina the 9th. Unemployment in August 2026 was 3.5% in North Carolina, 3.2% in Georgia, 4.1% in South Carolina, 3.4% in Tennessee and 3.6% in Virginia (U.S. Bureau of Labor Statistics).
North Carolina was among the 10 most distressed states in 2012; one quarter in 2013 moved it to the middle
At its worst
In the second quarter of 2012, North Carolina scored 84 and ranked 9th, its highest point on our chart, which starts in mid-2006. It ranked in the top 10 in 8 of the 75 quarters shown, all in 2006 and 2007 or 2011 and 2012. Its lowest score, 40, came in the first half of 2024, when it ranked 31st.
The 2013 drop, and what stayed high
Between the second and third quarters of 2013 the score fell from 76 to 52, and the state went from 13th to 25th. Two parts moved: jobs, from 81 to 60, and renters’ housing costs, from 56 to 42. Late payments did not. That part has been 66 or higher in every quarter on the chart, and it is 70 now.
Since the chart ends
The chart’s last quarter is the first of 2025, when North Carolina scored 42 and ranked 30th. Today it scores 44 and is 29th. The renters’ part held at 34 with the Census Bureau’s 2025 estimate, and the jobs part fell from 46 to 34.
North Carolina ranked 9th for distress at its 2012 peak and 31st at its 2024 low
North Carolina’s State Distress Index score each quarter, 0 to 100, from the third quarter of 2006, the first with all four parts, to the first quarter of 2025.
North Carolina’s poorest and most distressed counties are in the east
Robeson County, around Lumberton, is the poorest county in North Carolina: 23.7% of its people lived below the poverty line in 2024, the highest rate among the state’s 100 counties, the Census Bureau estimates. Edgecombe County, around Tarboro, is the most distressed on our County Distress Index, which measures the strain on household budgets in every U.S. county. It scores 99 and ranks 30th of 3,144 counties nationwide; Halifax and Robeson also make the national top 100 (see the national list). Camden County, in the state’s northeast corner, is the least distressed, at 3.
The most distressed counties run from the northeast down the coastal plain to the South Carolina line; the least distressed sit around Raleigh, southeast of Charlotte and in the far northeast
Each of the 100 counties shaded by its County Distress Index score (0 to 100); data run through August 2026.
Loading the county map…
The county map could not be loaded. Every county is in the lists on this page.
Most distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 1 | Edgecombe | 99 | 21.1% |
| 2 | Halifax | 98 | 18.8% |
| 3 | Robeson | 97 | 23.7% |
| 4 | Washington | 96 | 19.9% |
| 5 | Vance | 96 | 18.1% |
| 6 | Bladen | 95 | 20.6% |
| 7 | Northampton | 95 | 22.5% |
| 8 | Scotland | 94 | 22.9% |
| 9 | Richmond | 93 | 21.5% |
| 10 | Hertford | 93 | 22.9% |
Least distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 96 | Dare | 17 | 8.4% |
| 97 | Union | 15 | 7.6% |
| 98 | Chatham | 11 | 8.7% |
| 99 | Currituck | 9 | 8.1% |
| 100 | Camden | 3 | 7.5% |
Rank in North Carolina, 1 = most distressed. Ranks use scores before rounding, which is why Washington ranks ahead of Vance, Bladen ahead of Northampton and Richmond ahead of Hertford though each pair prints the same score, here and in the full list below. Poverty is each county’s 2024 Census Bureau rate.
Every county, by score
Of North Carolina’s 100 counties, 23 score 80 or more, and 13.6% of the state’s people live in them. All but one of the 23 lie outside the big metro areas, the coast and the western mountains as we group them; the exception is Cumberland, home to Fayetteville, (see the regions).
23 score 80–100
Edgecombe, Halifax, Robeson, Washington, Vance, Bladen, Northampton, Scotland, Richmond, Hertford, Anson, Bertie, Cumberland, Hyde, Wilson, Lenoir, Warren, Pitt, Columbus, Sampson, Martin, Cleveland, Wayne
12 score 70–79
Chowan, Jones, Hoke, Duplin, Graham, Rutherford, Greene, Rockingham, Gaston, Tyrrell, Nash, Gates
27 score 50–69
Person, Rowan, Beaufort, Granville, Pasquotank, Franklin, Randolph, Swain, Burke, Montgomery, Surry, Guilford, Alleghany, McDowell, Caswell, Caldwell, Onslow, Forsyth, Wilkes, Craven, Madison, Alamance, Harnett, Lee, Davidson, Jackson, Haywood
The five poorest counties all rank among the 10 most distressed; Watauga is the clearest exception
Each of five parts is a fifth of our County Distress Index. They are late payments; collections and bankruptcy; jobs; renters’ housing costs; and a part built from the poverty rate, child poverty, median household income, the share of people with a disability and the share without health insurance. So poverty is only one piece, yet here the poverty and distress rankings agree at the top. Robeson, Scotland, Hertford, Northampton and Richmond have the five highest poverty rates, and each is among the 10 most distressed. Edgecombe, the most distressed, is tied for 7th on poverty with Duplin, which ranks 27th on distress. Watauga County, home to Boone, has the 9th highest poverty rate in the state, 20.8%. But Watauga ranks 85th of 100 on distress, because few of its people are behind on loans or have debts in collections. Sites that use the Census Bureau’s American Community Survey may print different county poverty rates; ours are its 2024 Small Area Income and Poverty Estimates.
The five poorest counties
| County | Poverty | Distress rank |
|---|---|---|
| Robeson | 23.7% | 3rd |
| Scotland | 22.9% | 8th |
| Hertford | 22.9% | 10th |
| Northampton | 22.5% | 7th |
| Richmond | 21.5% | 9th |
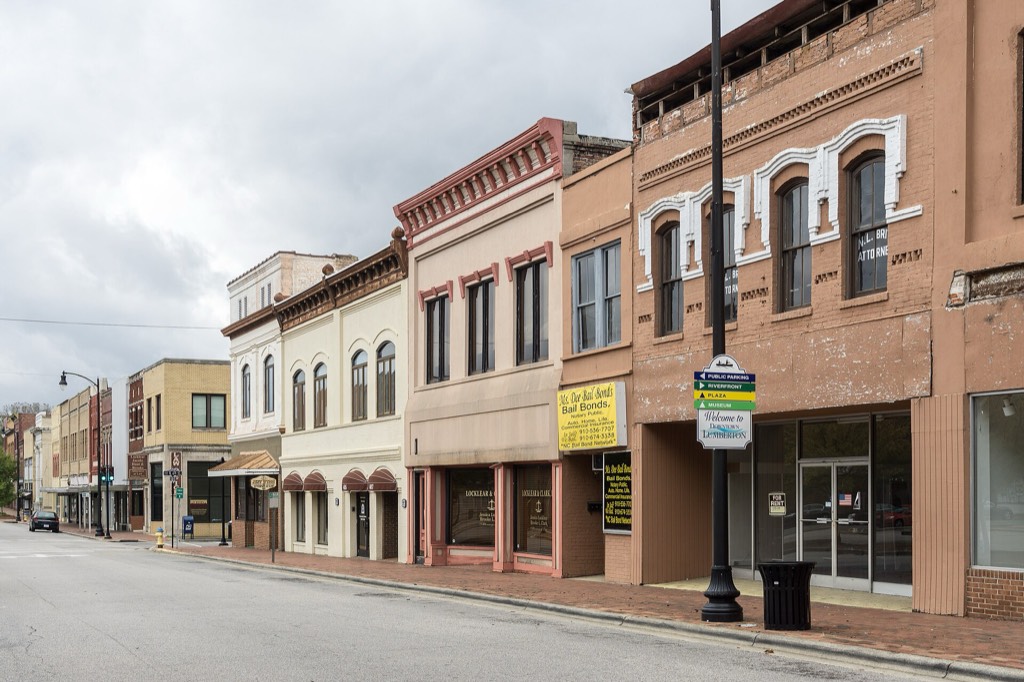
North Elm Street in downtown Lumberton, the seat of Robeson County, in October 2017. Robeson had the highest poverty rate of any North Carolina county in 2024, 23.7% (Census Bureau), and it ranks 90th of 3,144 U.S. counties on our County Distress Index.
Source: U.S. Census Bureau; American Default Research. Photo: Kenneth C. Zirkel, Wikimedia Commons, CC BY-SA 4.0.

Hurricane Helene’s mountain counties sit near the middle of our index
After Hurricane Helene in September 2024, the Federal Emergency Management Agency approved aid to households in 39 North Carolina counties. The 23 of them in the mountains and western foothills, our grouping, hold 10.8% of the state’s people and average 49 on the County Distress Index, weighted by population, against 51 for all 100 counties. Buncombe County, home to Asheville, scores 45 and ranks 67th of 100; Graham, at 77, is the highest of the group. Our index tracks unemployment, late payments, collections, rent and income, so it doesn’t measure storm damage itself. By the end of 2025, the state had processed more than 36,000 storm-related unemployment claims and paid $96.6 million in benefits, North Carolina’s commerce department reported.
Federal Emergency Management Agency, disaster declaration 4827; North Carolina’s commerce department, Jan. 7, 2026; American Default Research, County Distress Index; group averages are our calculation.
Is eastern North Carolina worse off than Raleigh and Charlotte?
Yes, by a wide margin. The six Triangle counties around Raleigh, Durham and Chapel Hill hold 19.2% of the state’s people and average 26 on our County Distress Index, weighted by population. The 51 counties outside the big metro areas, the coast and the western mountains hold 24.6% and average 69, and 22 of them score 80 or more. Our Fayetteville group, Cumberland and Hoke, averages 87.
| Area (our grouping) | Counties | Share of residents | Average score | Poverty rate, 2024 |
|---|---|---|---|---|
| Triangle: Wake, Durham, Orange, Johnston, Chatham, Franklin Average score 26 · Poverty rate, 2024 9.6% | 6 Share of residents 19.2% | 19.2% | 26 | 9.6% |
| Coast: New Hanover, Brunswick, Pender, Onslow, Carteret, Craven, Dare Average score 45 · Poverty rate, 2024 10.9% | 7 Share of residents 8.2% | 8.2% | 45 | 10.9% |
| Charlotte area: Mecklenburg, Union, Cabarrus, Gaston, Iredell, Lincoln Average score 44 · Poverty rate, 2024 10.1% | 6 Share of residents 20.2% | 20.2% | 44 | 10.1% |
| Mountains and western foothills hit by Helene Average score 49 · Poverty rate, 2024 13.8% | 23 Share of residents 10.8% | 10.8% | 49 | 13.8% |
| Triad: Guilford, Forsyth, Davidson, Randolph, Alamance Average score 59 · Poverty rate, 2024 13.1% | 5 Share of residents 13.3% | 13.3% | 59 | 13.1% |
| Every other county Average score 69 · Poverty rate, 2024 16.4% | 51 Share of residents 24.6% | 24.6% | 69 | 16.4% |
| Fayetteville area: Cumberland, Hoke Average score 87 · Poverty rate, 2024 16.5% | 2 Share of residents 3.6% | 3.6% | 87 | 16.5% |
Our grouping of all 100 counties, least distressed first; shares may not add to 100% because of rounding. Average score and poverty rate are averages of the county figures, weighted by each county’s population (County Distress Index; Census Bureau, Small Area Income and Poverty Estimates). The western group is the 23 mountain and foothill counties among the 39 that FEMA approved for household aid after Helene. A group average hides spread inside it: Cumberland scores 89 and Hoke 78.
Raleigh’s and Charlotte’s home counties differ, too. Wake County scores 17 and has the second-highest median household income in the state, $107,083. Mecklenburg County scores 49, near the state’s middle, because its late-payment and renters’ costs parts run well above Wake’s. Our scores locate the strain; they don’t explain it. The east and the metros also differ in age, jobs and who lives there, and we haven’t measured those here. The poorest counties →
Is North Carolina a poor state?
Somewhat poorer than the typical state, by the Census Bureau’s estimates. In 2024, 12.6% of North Carolinians lived below the poverty line, tied for 16th highest among the 50 states and D.C., against 12.1% nationwide. The median household earned $74,055, 15th lowest, against $81,604 for the whole country (Census Bureau, Small Area Income and Poverty Estimates). Income per person in 2024, all the income residents get divided by the number of residents, was $65,634, 17th lowest, against $73,204 for the U.S. (U.S. Bureau of Economic Analysis).
Residents in poverty
12.6%
U.S. 12.1%
Tied for 16th highest of the states and D.C. for 2024
Children in poverty
16.6%
U.S. 15.5%
16th highest of the states and D.C. for 2024
Median household income
$74,055
U.S. $81,604
15th lowest of the states and D.C. for 2024
North Carolina’s poverty rate has topped the nation’s in every Census estimate since 1998, though the gap is far smaller than in 2012
Percent of people below the poverty line in North Carolina and the whole U.S., 1989 to 2024. The Census Bureau made no state estimates for 1990 to 1992 or for 1994.
Health insurance and benefit income in North Carolina
From 2020 to 2024, 9.9% of North Carolinians had no health insurance (U.S.: 8.4%), the 11th highest share among the 50 states and D.C. (Census Bureau, American Community Survey). Those years mostly predate the state’s Medicaid expansion, which began on Dec. 1, 2023 (NC Medicaid). In 2024, government benefits such as Social Security, Medicare, Medicaid and veterans’ benefits made up 21.1% of all the income North Carolinians received, tied for 13th highest, against 18.3% for the U.S. (Bureau of Economic Analysis). These figures describe the state; they don’t explain its distress.
Union and Wake have the highest incomes
Union County, southeast of Charlotte, had the highest median household income in North Carolina in 2024, $107,681, and Wake County, home to Raleigh, came second, at $107,083 (Census Bureau). Robeson had the lowest, $46,927. Camden County had the lowest poverty rate, 7.5%. The poverty rate on this page is the Census Bureau’s; for the federal poverty guideline that programs use, see the questions below. The poorest and most distressed counties →
What changed in North Carolina in the past year
-
Oct. 1, 2026
Medicaid now covers fewer groups of noncitizens
From this date, the state health department said in September, only some noncitizens qualify for North Carolina Medicaid: lawful permanent residents; children under 19 and pregnant women or new mothers who are lawfully present; Cuban and Haitian entrants; and citizens of Micronesia, the Marshall Islands and Palau. The department ties the new rules to the 2025 federal budget law and to changes in state law.
North Carolina’s health and human services department, Sept. 1, 2026
-
July 7, 2026
The state got its first full budget in more than two years
Gov. Josh Stein signed Senate Bill 257, North Carolina’s first full state budget in more than two years, his office said. The governor’s statement says the budget fully funds Medicaid for the year and pays for raises for teachers and law enforcement; it gives no dollar figures, and we have not read the bill’s totals.
-
Feb. 1, 2026
SNAP stopped covering refugees and asylees by that status alone
SNAP eligibility for noncitizens narrowed to lawful permanent residents, Cuban and Haitian entrants and citizens of Micronesia, the Marshall Islands and Palau. Refugees, asylees and most parolees no longer qualify on that status alone and can qualify again only once they become permanent residents, the state’s human services department told county offices in May.
-
Dec. 10, 2025
Medicaid payment cuts to doctors and hospitals were reversed
Court rulings required the state to undo the cuts in what Medicaid pays doctors, hospitals and other providers that began Oct. 1, 2025, and to restore the Sept. 30 rates, the state Medicaid program told providers. The cuts were to payments, not to patients’ coverage. The program also said it was underfunded by $319 million and could run out of money early in 2026.
-
Dec. 1, 2025
SNAP’s work rule began to cover adults up to 64
Adults without dependents now face SNAP’s work rule through age 64 instead of 54, and living with a child exempts adults only if the child is under 14 instead of under 18. Adults the rule covers who don’t meet it or qualify for an exemption can get benefits for only three months in a 36-month period. Both changes come from the 2025 federal budget law (see SNAP).
Are North Carolinians behind on their bills? On cars and cards, more than in most states
Yes, on most kinds of loans. In early 2025, 19.5% of North Carolinians with a credit record had debt 90 or more days late, 14th highest among the 50 states and D.C., against 17.2% nationally, our population-weighted average of the states (Federal Reserve Bank of Philadelphia). These are household debts, not the state government’s.
North Carolina’s rank among the 50 states and D.C., 1 the highest share: 13th for card borrowers, 15th for collections, 8th for car loans and tied for 23rd for mortgages. The U.S. bars are our population-weighted average of the states.
Card trouble has grown. The share of card borrowers 90 or more days late went from 11.1% at the end of 2019 to 15.6% in early 2025. Collections fell over the same years, from 26.4% to 14.5% by mid-2023, and have stayed close to that since (15.2% in early 2025). Much of that fall came after early 2022, when the share stood at 21.8% and the three big credit bureaus announced they would drop many medical debts from credit reports. A debt removed from a report hasn’t necessarily been paid. Nationwide, the share of people with a medical collection on their report went from about 14% in March 2022 to about 5% in June 2023 (Consumer Financial Protection Bureau).
Counted in dollars, car loans show the widest gap with the U.S.
The Federal Reserve Bank of New York counts the share of dollars owed that is 90 or more days late, a different measure from the people counted above. At the end of 2025, 6.1% of North Carolina car-loan balances were that far behind, tied for 10th highest among the 50 states and D.C., against 5.2% nationwide. Card balances were close to the U.S. share and mortgage balances level with it.
| Loan type | North Carolina | U.S. | N.C. 2019 | U.S. 2019 |
|---|---|---|---|---|
| Auto loan | 6.1% End of 2025 U.S. 5.2% N.C. 2019 5.7% · U.S. 2019 4.9% | 5.2% | 5.7% | 4.9% |
| Credit card | 12.5% End of 2025 U.S. 12.4% N.C. 2019 8.2% · U.S. 2019 8.1% | 12.4% | 8.2% | 8.1% |
| Mortgage | 0.9% End of 2025 U.S. 0.9% N.C. 2019 0.9% · U.S. 2019 1.0% | 0.9% | 0.9% | 1.0% |
Share of balances 90 or more days past due at the end of 2025 and the end of 2019. Source: Federal Reserve Bank of New York, Consumer Credit Panel / Equifax. It counts dollars, not people, so it doesn’t match the Philadelphia Fed bars above, and it includes old debts that lenders have written off but still report.
Thin home equity is a bit more common than nationwide
In the second quarter of 2026, 5.3% of North Carolina mortgages had less than 10% equity, meaning the owner would keep less than a tenth of the home’s value after paying off the loan. That ranks 14th highest among the 50 states and D.C.; the U.S. share is 4.7% (Federal Housing Finance Agency).
| Measure | North Carolina | U.S. | Rank |
|---|---|---|---|
| Mortgages 30 to 89 days late, Sept. 2025 Tied for 21st highest | 1.7% U.S. 1.6% | 1.6% | Tied for 21st highest |
| Household debt per person with a credit report, end of 2025 22nd highest | $61,070 U.S. $63,200 | $63,200 | 22nd highest |
Rank among the 50 states and D.C. Mortgages 30 to 89 days late, an early sign of falling behind: Consumer Financial Protection Bureau. Debt per person, every kind of household debt combined: Federal Reserve Bank of New York. Late payments in every state →
North Carolina’s economy: unemployment under the nation’s, and one of the biggest job gains of any state
North Carolina’s unemployment rate was 3.5% in August 2026, tied for 18th lowest among the 50 states and D.C., against 4.1% for the U.S. (U.S. Bureau of Labor Statistics). The bureau counts that gap as statistically significant, and also the drop from 3.9% in August 2025. Over the same year the state added 65,600 payroll jobs, the third-largest gain of any state after Texas and California, in the bureau’s preliminary count.
Filing for unemployment benefits? That goes through the state’s Division of Employment Security →
Unemployment rate
3.5%
U.S. 4.1%
Tied for 18th lowest of the states and D.C. for August 2026
Yearly average unemployment rate
3.8%
U.S. 4.3%
2025; it was 3.9% in 2019, against 3.7% for the U.S.
Highest county rate, Edgecombe County
5.4%
August 2026, not adjusted for seasonal swings
North Carolina has had a lower unemployment rate than the U.S. in every month with data since May 2023
Share of the labor force out of work and looking for a job, North Carolina and the U.S., seasonally adjusted, monthly from January 1990 through August 2026. October 2025 is missing because the federal government shutdown halted data collection.
Unemployment is highest in Edgecombe County and lowest in Currituck County
| County | Rate |
|---|---|
| Edgecombe (Tarboro) | 5.4% |
| Halifax (Halifax) | 5.3% |
| Robeson (Lumberton) | 5.1% |
| Mecklenburg (Charlotte) | 3.7% |
| Wake (Raleigh) | 3.1% |
| Currituck (Currituck) | 2.7% |
Unemployment rate, August 2026, not adjusted for seasonal swings: the three highest of North Carolina’s 100 counties, the two largest counties, and Currituck, the lowest, with county seats in parentheses. Source: U.S. Bureau of Labor Statistics.
North Carolina’s minimum wage is the federal floor
The state minimum wage is $7.25 an hour, the same as the federal minimum. Employers may pay tipped workers as little as $2.13 an hour if tips make up the difference, the state labor department says (minimum wage in North Carolina). Rent and the cost of living →
Is North Carolina expensive to live in? Rent is below the U.S. median, but more renters are stretched than in 2019
Rent is cheaper than nationwide. The median rent in North Carolina was $1,228 a month from 2020 to 2024, 25th lowest among the 50 states and D.C., against $1,413 for the U.S. (U.S. Census Bureau). A year of that rent equals 19.9% of the median household’s 2024 income, against 20.8% nationwide (our calculation). We don’t track prices for groceries, gas or power, so this page can’t rank North Carolina’s whole cost of living.
Median rent, a month
$1,228
U.S. $1,413
25th lowest of the states and D.C. for 2020 to 2024
Renters spending at least 30% of income on housing
44.7%
U.S. 47.6%
25th lowest of the states and D.C. for 2020 to 2024
Homeowners spending at least 30% of income on housing
19.3%
U.S. 22.5%
Tied for 17th lowest of the states and D.C. for 2020 to 2024
The share of North Carolina renters paying half their income for housing rose from 21.7% in 2019 to 24.9% in 2024, faster than nationwide
Renter households paying half or more of their income for rent and utilities, North Carolina and the U.S., one-year Census estimates, 2005 to 2024. The Census Bureau published no one-year estimate for 2020.
A bare-bones budget in North Carolina
The MIT Living Wage Calculator puts the yearly cost of basic needs for a single adult with no children in North Carolina at $46,745 before taxes, 23rd lowest among the 50 states and D.C. overall. For two working parents with two children it is $106,196. Both figures cover necessities and leave nothing for savings.
Wages at the bottom are low: the state minimum is $7.25 an hour (see jobs and wages).
Rent sits between South Carolina’s and Georgia’s
Median rent in North Carolina is a little higher than in South Carolina and Tennessee and well below Georgia and Virginia. Against income, North Carolina’s rent takes about the same bite as its neighbors’.
| State | Rent, a month | Median household income | Rent as share of income |
|---|---|---|---|
| South Carolina Rent as share of income 19.5% | $1,180 Median household income $72,507 | $72,507 | 19.5% |
| Tennessee Rent as share of income 19.8% | $1,189 Median household income $72,007 | $72,007 | 19.8% |
| North Carolina Rent as share of income 19.9% | $1,228 Median household income $74,055 | $74,055 | 19.9% |
| Georgia Rent as share of income 20.9% | $1,393 Median household income $79,912 | $79,912 | 20.9% |
| Virginia Rent as share of income 20.6% | $1,579 Median household income $92,116 | $92,116 | 20.6% |
Rent: median gross rent a month, 2020 to 2024 (Census Bureau, American Community Survey). Income: median household income, 2024 (Census Bureau, Small Area Income and Poverty Estimates). Rent as share of income: 12 months of median rent divided by median household income, our calculation. Rent and housing costs by state →
How many North Carolinians get SNAP food benefits?
In June 2026, 1,245,356 North Carolinians got SNAP, the federal food benefit once called food stamps, the U.S. Department of Agriculture reports. That is 11.1% of the state’s 2025 population, tied for 16th highest among the 50 states and D.C., against 10.6% nationwide, and the count fell 7.8% from June 2025.
To apply for food benefits, called Food and Nutrition Services in North Carolina, or to check a case, use the state’s ePASS site →
People getting SNAP
1,245,356
June 2026, U.S. Department of Agriculture
Share of residents getting SNAP
11.1%
U.S. 10.6%
Tied for 16th highest of the states and D.C. for June 2026 (2025 population)
Change from a year earlier
−7.8%
June 2025 to June 2026
The count has been shrinking for years. It averaged 1,575,156 people a month in 2022 and 1,384,342 in 2025, lower every year in between (U.S. Department of Agriculture; the yearly averages are our calculation). The slide started long before SNAP’s wider work rule took effect on Dec. 1, 2025. The June 2026 count was 1,245,356. No source we’ve read splits the past year’s drop by cause. Fewer people on SNAP doesn’t mean less need: the Census Bureau’s poverty rate for North Carolina was 12.6% in 2024 (see poverty).
The new SNAP rules in North Carolina
Two federal changes reached North Carolina’s SNAP rolls this past year. The work rule for adults without dependents now runs through age 64, and the child exemption now stops at 14; noncitizen eligibility narrowed on Feb. 1, 2026. Dates and details are in what changed. The poorest counties →
North Carolinians file for bankruptcy less often than most Americans, and mostly under Chapter 13
North Carolinians filed 9,847 bankruptcy cases in 2025, or 87.9 for every 100,000 residents (2025 population), 11th lowest among the 50 states and D.C., against 166.3 nationwide (Administrative Office of the U.S. Courts). Filings rose 11.2% from 2024, close to the national rise of 11.1%. They have gone up every year since 2022, and 2025 brought the most filings since 2019, when there were 13,531.
Chapter 13 cases made up 63.5% of North Carolina filings in 2025, against 35.9% nationwide, a share that ranks 4th highest of the 50 states and D.C. overall. Under Chapter 13, people usually keep their property and pay back part of what they owe through a court-approved plan lasting several years. Under Chapter 7, the more common choice across the country, many debts are erased and property the law doesn’t protect can be sold.
| Year | Filings |
|---|---|
| 2005 | 43,014 |
| 2006 | 17,241 |
| 2010 | 26,674 |
| 2019 | 13,531 |
| 2020 | 8,909 |
| 2021 | 6,577 |
| 2022 | 6,188 |
| 2023 | 7,452 |
| 2024 | 8,859 |
| 2025 | 9,847 |
Cases under every chapter filed in North Carolina’s three federal bankruptcy districts, Eastern, Middle and Western, in selected years and every year since 2019. 2005 is the most in the available series, which run from 2001 to 2025 with 2004 missing. Source: Administrative Office of the U.S. Courts, Table F-2. Bankruptcy filings in every state →
How foreclosure works in North Carolina
Most North Carolina home loans are secured by a deed of trust with a power of sale, so a foreclosure usually doesn’t need a lawsuit. It does need a hearing before any sale. The clerk of superior court in the home’s county must find a valid debt and a loan in default. The clerk must also find that the lender has the right to foreclose and that required notices went out (G.S. 45-21.16). For a home loan on the home you live in, your mortgage company must mail you a notice at least 45 days before it files for that hearing (G.S. 45-102).
At the hearing on an owner-occupied home, the clerk asks what has been done to resolve the missed payments. The clerk must postpone the hearing for up to 60 days when more time or other steps are reasonably likely to fix them (G.S. 45-21.16C). After the auction, anyone may file a higher bid, called an upset bid, within 10 days, and each new bid restarts that period (G.S. 45-21.27). Paying the full debt and costs before the period ends stops the sale (G.S. 45-21.20). A lender that wants the balance left after a sale has one year from the foreclosure deed to sue for it (G.S. 1-54). That right generally does not apply to a loan the seller made for part of the purchase price (G.S. 45-21.38). Under federal servicing rules, a mortgage company generally can’t begin a foreclosure on the home you live in until you are more than 120 days behind.
- Usually goes through a court
- No; a clerk’s hearing
- Notice before the hearing is filed
- 45 days
- Hearing can be postponed for talks
- Up to 60 days
- Upset-bid period after the sale
- 10 days
- Time to sue for the balance
- One year
What the law says for a home you live in. Sources: North Carolina General Statutes, Chapter 45 (G.S. 45-21.16, 45-21.16C, 45-21.20, 45-21.27, 45-21.38 and 45-102) and G.S. 1-54; federal rule 12 CFR 1024.41. How foreclosure works in North Carolina →
The state was awarded $273.3 million from the federal Homeowner Assistance Fund, and through early 2026 the fund had helped 17,974 North Carolina households (U.S. Treasury). For free foreclosure counseling, the state housing finance agency’s help line is 888-442-8188 (North Carolina Housing Finance Agency).
Mortgage problems North Carolina homeowners have taken to the CFPB
From 2012 through mid-October 2026, the Consumer Financial Protection Bureau logged 13,937 mortgage complaints from North Carolina. The issue raised most often is loan modification, collection or foreclosure (3,389), one complaint ahead of trouble during the payment process (3,388); loan servicing, payments or escrow comes third (2,225).
- Oct. 12, 2026 Alabama Housing Finance Authority Struggling to pay: trouble reaching the company about a modification, forbearance or foreclosure Closed with explanation
- Oct. 5, 2026 Dovenmuehle Mortgage Payment process: escrow, taxes or insurance Closed with explanation
- Oct. 1, 2026 Truist Financial Payment process: private mortgage insurance Closed with monetary relief
- Sept. 29, 2026 Shellpoint / NewRez Payment process: trouble reaching the company to fix a problem with the loan In progress
- Sept. 29, 2026 MidFirst Bank Payment process: trouble reaching the company to fix a problem with the loan Closed with explanation
- Sept. 29, 2026 Shellpoint / NewRez Payment process: fees charged In progress
- Sept. 28, 2026 Village Capital Struggling to pay: applying for a modification, forbearance, short sale or deed-in-lieu Closed with explanation
- Sept. 27, 2026 Rocket Mortgage Struggling to pay: trouble reaching the company about a modification, forbearance or foreclosure Closed with explanation
- Sept. 27, 2026 Carrington Mortgage Payment process: trouble reaching the company to fix a problem with the loan In progress
- Sept. 26, 2026 Ocwen / Onity Group Struggling to pay: trouble reaching the company about a modification, forbearance or foreclosure In progress
The 10 newest North Carolina complaints about paying a mortgage or getting help with one, newest first, from the Consumer Financial Protection Bureau’s public database as of Oct. 14, 2026. We leave out complaints about taking out a new loan and any that name a credit reporting company. Each is one person’s account, which the bureau doesn’t verify; a complaint doesn’t show that the company did anything wrong. Every North Carolina mortgage complaint at the Consumer Financial Protection Bureau →
What to watch before the next edition
Three dated items stand between now and the next edition, nearest first: a jobs report, then a Medicaid rule that starts on New Year’s Day, and Duke Energy’s new rates, which would start then if the commission approves them.
-
Nov. 20, 2026
October unemployment rates for the states
The Bureau of Labor Statistics plans to publish state unemployment rates for October at 10 a.m. North Carolina’s rate eased from 3.8% in January 2026 to 3.5% in August 2026; this release shows whether that held.
Bureau of Labor Statistics, release schedule for State Employment and Unemployment
-
Jan. 1, 2027
Medicaid expansion’s work rule and six-month renewals begin
Adults 19 through 64 without a disability who get Medicaid through the state’s expansion will need household earnings of $580 a month, or 80 hours a month of work, school or volunteering, unless an exemption applies, the state health department says. Most will also renew their coverage every six months instead of once a year. Expansion began on Dec. 1, 2023.
North Carolina’s health and human services department, Sept. 1, 2026; NC Medicaid, expansion page
-
Jan. 1, 2027
Duke Energy’s new electric rates, if the commission approves them
The North Carolina Utilities Commission is weighing settlements in rate cases for both Duke Energy utilities in the state. If approved, new rates would start taking effect on Jan. 1, 2027. The Attorney General’s office, which did not sign either deal, reads them as raising residential bills about 9.5% for Duke Energy Carolinas and 9.3% over two years for Duke Energy Progress; Duke puts its averages across all customers lower.
North Carolina Attorney General’s office, July 21, 2026; Aug. 13, 2026
Where North Carolina ranks highest and lowest
| Measure | North Carolina | U.S. | Rank | Latest data |
|---|---|---|---|---|
| Share of bankruptcy filings under Chapter 13 4th highest · 2025 | 63.5% U.S. 35.9% | 35.9% | 4th highest | 2025 |
| Car-loan borrowers 90+ days late 8th highest · Early 2025 | 10.9% U.S. 8.5% | 8.5% | 8th highest | Early 2025 |
| People with a subprime credit score 9th highest · Early 2025 | 16.4% U.S. 13.8% | 13.8% | 9th highest | Early 2025 |
| Residents without health insurance 11th highest · 2024* | 9.9% U.S. 8.4% | 8.4% | 11th highest | 2024* |
| Card borrowers 90+ days late 13th highest · Early 2025 | 15.6% U.S. 13.5% | 13.5% | 13th highest | Early 2025 |
| Mortgages with less than 10% equity 14th highest · Apr.–June 2026 | 5.3% U.S. 4.7% | 4.7% | 14th highest | Apr.–June 2026 |
| People with a debt in collections 15th highest · Early 2025 | 15.2% U.S. 13.2% | 13.2% | 15th highest | Early 2025 |
| Residents in poverty Tied for 16th highest · 2024 | 12.6% U.S. 12.1% | 12.1% | Tied for 16th highest | 2024 |
| Residents getting SNAP food benefits (2025 population) Tied for 16th highest · June 2026 | 11.1% U.S. 10.6% | 10.6% | Tied for 16th highest | June 2026 |
| Renters spending at least half their income on housing 23rd highest · 2024 | 24.9% U.S. 26.1% | 26.1% | 23rd highest | 2024 |
| Median rent, a month 25th lowest · 2024* | $1,228 U.S. $1,413 | $1,413 | 25th lowest | 2024* |
| Unemployment rate, three-month average Tied for 17th lowest · June–August 2026 | 3.6% U.S. 4.1% | 4.1% | Tied for 17th lowest | June–August 2026 |
| Median household income 15th lowest · 2024 | $74,055 U.S. $81,604 | $81,604 | 15th lowest | 2024 |
| Bankruptcy filings per 100,000 residents (2025 population) 11th lowest · 2025 | 87.9 U.S. 166.3 | 166.3 | 11th lowest | 2025 |
Each rank places North Carolina among the 50 states and D.C., from the highest value or the lowest as the row says; equal printed values share a rank. * Census Bureau five-year survey, 2020 to 2024. Rows on borrowers, credit scores and collections count people with a credit record (Federal Reserve Bank of Philadelphia); for those rows the U.S. number is a population-weighted average of the states that we compute. Equity: Federal Housing Finance Agency. Sources for each row are in Sources and method. Download this table: CSV.
Questions about North Carolina
Is North Carolina a poor state?
A little poorer than most. The U.S. Census Bureau put 12.6% of North Carolinians in poverty in 2024, tied for 16th highest of the 50 states and D.C., with a median household income of $74,055, 15th lowest. On our State Distress Index it ranks 29th, near the middle, mainly because unemployment is low. Is North Carolina poor? →
What is the poorest county in North Carolina?
Robeson County, whose seat is Lumberton: 23.7% of its residents lived in poverty in 2024, the highest of the state’s 100 counties, and its median household income, $46,927, was the lowest (U.S. Census Bureau, Small Area Income and Poverty Estimates). Edgecombe County, around Tarboro, is the most distressed on our County Distress Index. The poorest and most distressed counties →
Does foreclosure go through a court in North Carolina?
Usually not a full lawsuit, but a court official is involved. Under a power of sale, the clerk of superior court holds a hearing and must make findings before the home can be sold. For an owner-occupied home, the clerk must postpone the hearing for up to 60 days when more time is reasonably likely to resolve the default (G.S. 45-21.16 and 45-21.16C). How foreclosure works in North Carolina →
What is the minimum wage in North Carolina?
$7.25 an hour, the same as the federal minimum; tipped workers can be paid $2.13 an hour if tips make up the rest (North Carolina labor department, minimum wage page).
What’s the poverty level in North Carolina?
Programs use the federal poverty guideline, which is the same in every state except Alaska and Hawaii. For 2026, it is $15,960 a year for a single person and $33,000 for a household of four (U.S. Department of Health and Human Services). The 12.6% poverty rate on this page uses the Census Bureau’s own thresholds, a different measure.
Did Hurricane Helene make western North Carolina more distressed?
Our County Distress Index doesn’t place those counties among the state’s most strained. The 23 mountain and foothill counties FEMA approved for household aid average 49, weighted by population. That is below the 51 average for all 100 counties; Buncombe County scores 45. The index measures household finances, not storm damage. Helene’s mountain counties →
Cite or reuse North Carolina’s data
Journalists, researchers and grant writers are welcome to use these figures; please credit American Default Research.
State Distress Index
North Carolina
29thmost distressed state
of the 50 states and D.C.
More distressed than 44% of the other states and D.C.
North Carolina is the 29th most distressed of the 50 states and D.C. on American Default Research’s State Distress Index, which measures strain on household finances. In early 2025, 10.9% of its car-loan borrowers were 90 or more days late, 8th highest (Federal Reserve Bank of Philadelphia), and the Census Bureau put its 2024 poverty rate at 12.6%. Edgecombe County is the state’s most distressed county, 30th of 3,144 U.S. counties on the County Distress Index.
For an interview or a custom cut of the data, reporters can write to press@americandefault.org
Sources and method
We gather the data, run the numbers and research each state ourselves.
This edition: October 2026 · Next edition expected March 2027
- Poverty and household income for North Carolina and its countiesCensus Bureau, Small Area Income and Poverty Estimates1989 to 2024
- Renter households spending at least half their income on rent and utilitiesCensus Bureau, American Community Survey, one-year estimates2005 to 2024
- Rent, housing costs and health insuranceCensus Bureau, American Community Survey, five-year estimates2020 to 2024
- Income per person and benefit incomeU.S. Bureau of Economic Analysis2024
- Unemployment, state, county and U.S.; payroll jobsU.S. Bureau of Labor Statistics, Local Area Unemployment Statistics; State Employment and Unemployment, August 2026Jan. 1990 to Aug. 2026
- Late payments, collections and credit scoresFederal Reserve Bank of Philadelphia, Consumer Credit Explorerend of 2019 to early 2025
- Household debt and dollars behindFederal Reserve Bank of New York, Consumer Credit Panel / Equifaxend of 2019 and end of 2025
- Mortgages with little equityFederal Housing Finance Agency, National Mortgage Databasesecond quarter of 2026
- Mortgages 30 to 89 days late; mortgage complaints; medical debts on credit reportsConsumer Financial Protection Bureau: Mortgage Performance Trends; complaint database; Recent changes in medical collections on consumer credit recordsSept. 2025; Oct. 14, 2026; March 2022 to June 2023
- Bankruptcy filingsAdministrative Office of the U.S. Courts, Table F-22001 to 2025
- SNAPU.S. Department of Agriculture Food and Nutrition Administration2022 to June 2026
- Hurricane Helene countiesFederal Emergency Management Agency, disaster 4827; North Carolina’s commerce departmentSept. 2024 to Dec. 2025
- Cost of getting byMIT Living Wage Calculator2025 dollars
- Minimum wageNorth Carolina labor departmentOctober 2026
- Mortgage help fundU.S. Treasury, Homeowner Assistance Fundthrough early 2026
- Foreclosure lawNorth Carolina General Statutes, Chapter 45; G.S. 1-54; 12 CFR 1024.41; North Carolina Housing Finance Agencyas of 2026
- Poverty guidelineU.S. Department of Health and Human Services2026
- Housing counselorsU.S. Department of Housing and Urban DevelopmentOctober 2026
- What changed and what to watchNorth Carolina’s health and human services department, Medicaid, and SNAP, NC Medicaid, Office of the Governor, North Carolina Attorney General’s office, Bureau of Labor Statistics schedule. Every dated item links its own source (what changed)Oct. 2025 to Jan. 2027
- PhotoKenneth C. Zirkel, via Wikimedia Commons, CC BY-SA 4.02017
The four parts, jobs, late payments, collections and bankruptcy, and renters’ housing costs, count equally. We average them for every state and then score each one by the percentage of the other 49 states and D.C. with a lower average, so a state that scores 80 is more distressed than 80% of them. The full method →
We write with AI tools, and Ross Kilburn checks and reviews every page before it's published.
Get the next North Carolina edition by email
One email each time a new North Carolina edition is out; the next is expected in March 2027. Unsubscribe anytime.
Thanks, that helps.