Ocwen hardship complaints make up 41.6% of its mortgage record
Complaints about struggling to pay make up 41.6% of the CFPB record under Ocwen’s former company name. Ocwen is now Onity Group, whose Onity Mortgage subsidiary services loans. Its customer service number is 800-449-8767. Mail monthly payments to Onity Mortgage, P.O. Box 660093, Dallas, TX 75266-0093.

Next edition expected January 2027
Onity Mortgage phone number and written-request address
Onity Mortgage lists these routes for an existing mortgage. American Default is independent of Onity, Ocwen and the government.
Onity Mortgage servicing and payment assistance
1-800-449-8767The company uses this line for servicing questions and payment assistance.
Listed on onitymortgage.com · checked Oct 23, 2026
Requests for information and notices of error
Onity Mortgage
PO Box 24695
West Palm Beach, FL 33416
Onity designates this box for notices of error and requests for information about a loan.
Listed on onitymortgage.com · checked Oct 23, 2026
- General mail
- Onity Mortgage, P.O. Box 24736, West Palm Beach, FL 33416-4736 A different box for ordinary mail. Listed on onitymortgage.com · checked Oct 23, 2026
- Regular monthly payments by mail
- Onity Mortgage, P.O. Box 660093, Dallas, TX 75266-0093 For regular monthly payments. The company says to ask for instructions before mailing payoff funds or escrow shortages. Listed on onitymortgage.com · checked Oct 23, 2026
- Website support
- 1-833-862-0732 Help using the website, not the servicing line. Listed on onitymortgage.com · checked Oct 23, 2026
The latest statement names the current servicer. Onity Group is the corporate parent; Onity Mortgage is the borrower-facing company. A later transfer can change the servicer.
The company offers secure messages and chat through a signed-in Onity Mortgage account. American Default is independent of Onity.
What happened to Ocwen and PHH Mortgage?
The corporate renaming took effect June 10, 2024. PHH Mortgage Corporation, a direct subsidiary, changed its legal name to Onity Mortgage Corporation on March 23, 2026 (Onity privacy notice). The parent and the company servicing the loan have different names.
A mortgage servicer collects payments and manages the account. Onity says its mortgage subsidiary handles servicing. The current statement names the company servicing the loan.
The CFPB files complaints under two separate names: Ocwen Financial Corporation and PHH Mortgage Services Corporation. The counts and shares on this page include only complaints filed under Ocwen, not PHH. We leave PHH out because combining the two company records would change the comparison and could count complaints about different servicing periods together.
Ocwen complaints: hardship is the standout issue
Trouble paying is the most distinctive share in this record. From May 1, 2017 through October 19, 2026, 41.6% of 12,313 mortgage complaints under Ocwen's CFPB company name were tagged ‘struggling to pay mortgage.’ The median was 23.5% among 73 other companies with at least 200 complaints in that same window.
The loan mix may have contributed to the high share: New York’s 2014 order cited Ocwen’s rapid acquisition and servicing of distressed loans. That order predates most of the 2017–2026 complaint window, and this possible connection has not been tested.
The CFPB received 1,115 complaints under the Ocwen name in 2025. A matching loan count for a per-loan complaint rate is unavailable.
The chart sets each type of Ocwen complaint against the median company. Struggling to pay stands out. The CFPB changed its issue names in April 2017, so this comparison starts May 1, 2017.
Under the CFPB’s Ocwen name, struggling to pay takes a larger share; PHH complaints are excluded
Share of CFPB mortgage complaints, May 1, 2017 to October 19, 2026; 73 other companies with at least 200 complaints in that period
This company Median of other companies
Trouble during payment process
Struggling to pay mortgage
Applying for a mortgage or refinancing an existing mortgage
Closing on a mortgage
Incorrect information on your report
Problem with a credit reporting company's investigation into an existing problem
How often did Ocwen answer CFPB complaints on time?
Nearly all recent complaints were marked timely. Among 2,355 Ocwen complaints received from January 1, 2025 through October 19, 2026, the CFPB marked 2 late. The timely-response rate was 99.92%, about the same as 99.94% at the median of 40 other companies with at least 200 complaints in that shorter period.
‘Late’ means the CFPB marked the company's reply as untimely. Of the same recent complaints, 96.5% were closed with an explanation. The comparison group is smaller here because it covers only complaints since January 2025.
The CFPB publishes consumers' accounts; company size and the tendency to complain also affect counts (CFPB database notes).
If your mortgage moved to Onity
Your statement names the current servicer, which can differ from the loan owner. Servicing rights can be sold or a new company can be hired to collect payments.
Ocwen's history includes purchased servicing portfolios and the 2018 acquisition of PHH. The 2026 name change alone did not change who owns a loan (Onity announcement).
In June 2026, Onity sold servicing rights on about 20,000 reverse mortgages to Finance of America Reverse. Onity said it would remain their subservicer under a three-year agreement (Onity closing announcement). A subservicer handles the account for another company; the current statement names the servicer for a particular loan.
How to ask Onity Mortgage for help if you're behind
Onity Mortgage offers a payment-assistance request in its signed-in account and by phone. Its assistance page says to open Payments, then Request Assistance under Payment Assistance. It lists 1-800-449-8767 for a short-term hardship or questions, during the hours above.
‘Loss mitigation’ means ways to address missed mortgage payments. A borrower can ask the company which options it will review; the company decides what it can offer. Our loan-modification guide explains the general process.
A HUD-approved housing counselor can help you sort out documents and options for free. HUD's national line is 800-569-4287.
Where to report a servicing problem
A letter reporting a servicing mistake is called a notice of error. A letter asking for loan records is a request for information. Onity Mortgage lists the designated box above for both.
The CFPB complaint system accepts reports of servicing problems and sends them to the company for a response. Onity’s payment-assistance process is a separate route. A HUD-approved counselor or a lawyer can discuss an individual situation.
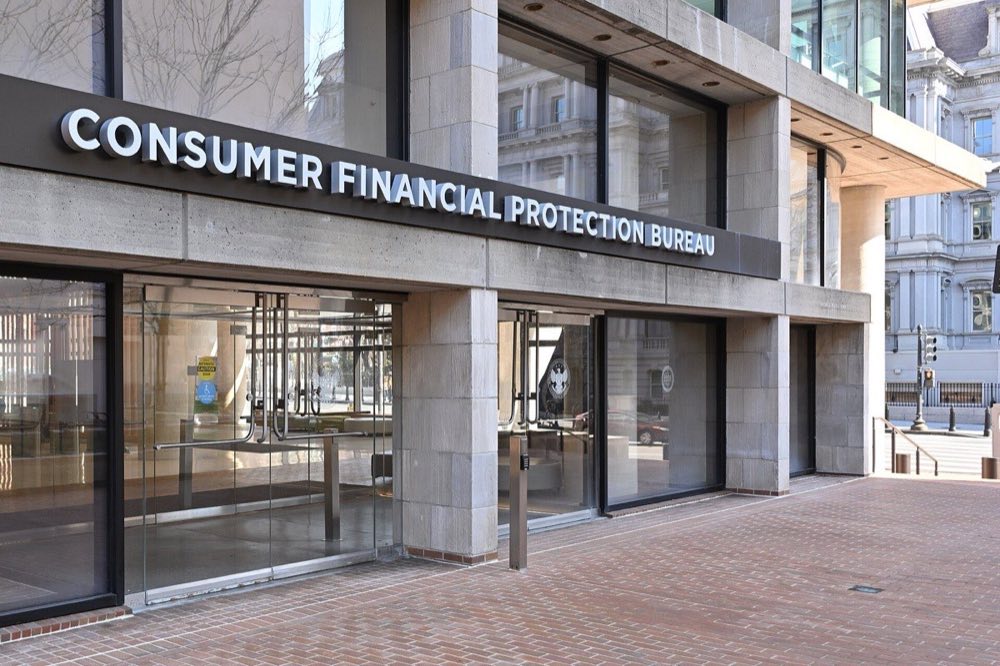
The CFPB publishes the consumer complaint records used in the October 2026 figures. CFPB complaint database

Ocwen regulator actions and lawsuits, with outcomes
These actions were selected for their federal or state servicing findings, penalties, borrower relief, or material court outcomes involving Ocwen-named entities. Actions that named only PHH Mortgage before Ocwen bought it in 2018 are excluded; PHH’s separate earlier record includes a January 2018 multistate servicing settlement. A consent order is a binding negotiated order; a court complaint states allegations.
-
May 2, 2023
Consumer Financial Protection Bureau; U.S. District Court, Southern District of Florida 2017 CFPB lawsuit, dismissed on summary judgment
The CFPB alleged inaccurate servicing information, foreclosure and complaint-handling failures. After an appeal, the district court granted judgment to Ocwen in 2023.
Admitted wrongdoing? No settlement; the court ruled for Ocwen.
Status: Dismissed May 2, 2023. The court granted judgment to Ocwen. · CFPB enforcement case and court outcome
-
Feb 17, 2023
California Department of Financial Protection and Innovation Consent order
California said its examination found that Ocwen Loan Servicing delayed interest-rate changes after some loan transfers, causing both undercharges and overcharges. PHH Mortgage joined because it had merged with Ocwen Loan Servicing.
Admitted wrongdoing? Ocwen did not admit the alleged violations, apart from facts needed for jurisdiction. The order allows later enforcement of its payment terms.
$2.5 million to the state for penalties, costs and fees
Status: Final consent order. It provided for California to withdraw its separate March 2022 proposed license-revocation action over a late annual report. · California DFPI 2023 consent order
-
Oct 15, 2020
Florida Attorney General and Office of Financial Regulation Proposed consent judgment filed in the Florida portion of the 2017 litigation
Florida settled its separate allegations about Ocwen servicing, including escrow and insurance problems. The filed proposal included consumer relief and a $2 million civil penalty, of which $1 million was suspended. Florida later reported more than $11 million in combined relief, penalties and costs; those categories are not all borrower payments.
Admitted wrongdoing? Ocwen denied the Florida allegations and liability in the filed judgment.
Status: Proposed judgment filed October 15, 2020; Florida later reported that the federal district court entered the consent judgment. The separate CFPB suit was dismissed in 2023. · Florida filed consent judgment
-
Jan 31, 2018
Connecticut Department of Banking Consent order resolving earlier state charges
The order restricted new servicing-right purchases through April 30, 2018 and required Ocwen to move loans off its servicing software by April 30, 2020. It also called for an escrow audit and borrower complaint reporting.
Admitted wrongdoing? Ocwen consented without admitting liability, fault or wrongdoing.
Status: Final order. Those dated duties have passed; the order also included contingent penalties rather than an upfront payment. · Connecticut DOB consent order
-
Aug 24, 2016
Washington Department of Financial Institutions Consent order
Washington's regulator said Ocwen Loan Servicing used two affiliates that were unlicensed to service Washington loans. The order imposed a $900,000 fine and $10,000 in investigation costs.
Admitted wrongdoing? The order says the respondents neither admitted nor denied wrongdoing.
Status: Final Washington consent order dated August 24, 2016. · Washington DFI consent order
-
Dec 22, 2014
New York Department of Financial Services Consent order
New York described servicing failures and conflicts of interest. Ocwen agreed to operational changes, a $100 million civil penalty that New York said it would use for housing, foreclosure-relief and community redevelopment programs, and $50 million in restitution to borrowers.
Admitted wrongdoing? Ocwen stipulated to the facts set out in the order.
Status: Final order. Under paragraph 67, each provision remains effective until the Department of Financial Services stays, modifies, suspends or terminates it. · New York DFS consent order
-
Feb 26, 2014
Consumer Financial Protection Bureau and state authorities Federal consent judgment on 2013 complaint
The court entered a negotiated judgment requiring Ocwen to provide $2 billion in principal reduction and fund cash payments for eligible borrowers. Principal reduction and cash compensation are different forms of relief.
Admitted wrongdoing? Ocwen did not admit the complaint's allegations, except facts needed for the court's jurisdiction.
Status: Final judgment entered February 26, 2014, with a dated borrower-relief program. · CFPB entered consent judgment
What federal rules say about payment help
Regulation X sets out the general review and response rules for a complete loss-mitigation application. A HUD-approved counselor or lawyer can explain a particular loan situation. These deadlines describe ordinary cases; exceptions and extensions apply.
-
For missed payments, the company must review a complete application under the rule
Onity Mortgage describes its payment-assistance application on its website. Under Regulation X, a servicer must send a written decision within 30 days when it receives a complete application more than 37 days before a scheduled foreclosure sale.
Source: Consumer Financial Protection Bureau, 12 CFR 1024.41
Get the next edition of this page by email
One email when the next edition is out, expected in January 2027. Unsubscribe anytime.
Thanks, that helps.
Questions about Onity Group Inc.
What is Ocwen called now?
Ocwen Financial Corporation became Onity Group Inc. in June 2024. Its PHH Mortgage subsidiary became Onity Mortgage Corporation in March 2026. The current statement names the company servicing a particular loan.
What is Onity Mortgage's servicing phone number?
The company lists 1-800-449-8767. It says the line is open weekdays, 8 a.m. to 9 p.m. Eastern, and Saturdays, 8 a.m. to 5 p.m. Eastern (Onity contact page).
Where does Onity Mortgage receive notices of error?
The company designates Onity Mortgage, PO Box 24695, West Palm Beach, FL 33416 for notices of error and requests for information (Onity contact page).
Does a late CFPB response prove a complaint was right?
No. A late mark concerns the timing of the company's reply.
Was the 2017 CFPB case against Ocwen resolved?
Yes. The district court granted judgment to Ocwen on May 2, 2023. The court held that the claims were covered by the 2014 consent judgment’s servicing-standard, monitoring and enforcement terms (court order).
Protect yourself from scams
The FTC and CFPB describe these warning signs and the rules behind them:
- Upfront fees for promised relief are a warning sign. Under FTC mortgage-assistance rules, most companies that sell mortgage help cannot charge until a homeowner accepts a written offer from the mortgage company or lender. A separate FTC rule covers debt-relief companies that sell by phone and ties fees to a completed debt arrangement. It bars a fee until at least one debt has been settled or changed, the customer agrees to the arrangement, and the customer has made a payment under it. The FTC describes a narrow exception for lawyers who give help as part of the practice of law and are licensed in the state where the client or dwelling is. The lawyer follows that state's rules for attorneys, and advance fees are placed in a client trust account before services begin under state trust-account rules.
- HUD-approved foreclosure-prevention counseling is free. HUD’s national counselor line is 800-569-4287. The CFPB counselor finder lists agencies and their services. If an organization charges for help described as free HUD counseling, the CFPB finder can verify the agency and its listed services before any payment.
- A request to sign over a deed is a warning sign. The CFPB identifies title-transfer schemes among foreclosure-relief scams. Signing over title can mean losing ownership of the home; a lawyer can explain what a proposed document would do.
- Foreclosure protections depend on timing and the loan. Regulation X generally bars the first foreclosure notice or filing on a principal-residence loan until the borrower is more than 120 days behind, subject to exceptions. A complete assistance application can delay some foreclosure steps, but that depends on when it arrives; it does not necessarily stop every step. The CFPB warns about promises to “save” a home.
Free help if you're behind
Housing counselors approved by the U.S. Department of Housing and Urban Development work at nonprofit agencies. The Consumer Financial Protection Bureau describes free foreclosure-avoidance counseling, including help with mortgage-company conversations and available options Source CFPB.
-
HUD-approved housing counselors
Our help directory lists 1,010 agencies approved for foreclosure counseling, by state.
-
Legal aid
Nonprofit law offices give free civil legal help to people with low incomes. Our help directory lists the 120 offices the Legal Services Corporation funds.
Every figure on this page, with its period and the CFPB filter behind it, in one file. Free to use with credit to American Default Research.
Sources and method
We gather the data, run the numbers and research each company ourselves. The CFPB publishes complaints without verifying each account. We counted only mortgage complaints in the CFPB archive under ‘Ocwen Financial Corporation,’ from 2012 through October 19, 2026. Complaints filed under PHH Mortgage Services Corporation are not included. Issue shares use May 1, 2017 through October 19, 2026; timely-response shares use January 1, 2025 through October 19, 2026. Peer medians compare other companies with at least 200 complaints in each same window. Updated: October 2026 · Next review expected: January 2027.
- Consumer Financial Protection Bureau, Consumer Complaint Database Mortgage complaints about the company, received through Oct 19, 2026. Our counts from the CFPB's complaint records.
- Current borrower contact routes
- Payment-assistance route
- Company names and subsidiary
- 2017 case outcome
- 2014 federal consent judgment
- New York consent order
- Washington consent order
- California 2023 consent order
- Florida case outcome
- Florida filed judgment
- Connecticut consent order
We write with assistance from AI tools. Figures come from the data and sources named on this page.