Minnesota had the nation’s lowest collections share: 7.5%, well below the national share
Each state is shaded by how distressed its households are, from green (least) to red (most), with data through September 2026. Minnesota scores 30 out of 100.
Minnesota had the nation’s lowest share of people with credit records and a debt in collections: 7.5% in early 2025, well below the national share. Typical rent was $1,280 a month, below the national figure. Even so, 23.0% of renters spent at least half their income on housing in 2024. Jobs weigh more on its distress score than late payments. Mahnomen and Beltrami counties face more strain than Carver and Wabasha.
- Score
- 30/100
- Data through
- September 2026
- Edition
- October 2026
Next edition expected March 2027
How Minnesota ranks among the states
Minnesota ranks 36th in household distress, with a State Distress Index score of 30. The tension inside that low score is work: the jobs part scores 72, far above the late-payments part at 4. In August 2026 the unemployment rate was 4.4%, compared with 4.1% nationally (U.S. Bureau of Labor Statistics). That statewide reading also conceals a wide county spread.
What makes up the score
Each measure places Minnesota among the states; the measures within each part form that part’s score. The four parts average 40. The final score reports the share of the other states and D.C. with a lower four-part average. That share is 30%.
- Jobs72The unemployment rate averaged 4.4% from June through August 2026, against 4.1% nationally (U.S. Bureau of Labor Statistics).
- Collections and bankruptcy32In early 2025, 7.5% of Minnesotans with a credit record had debt in collections, compared with 13.2% for the U.S. (Federal Reserve Bank of Philadelphia).
- Renters’ housing costs50The U.S. Census Bureau estimated that 23.0% of renters spent at least half their income on housing in 2024, compared with 26.1% nationally.
- Late payments4In early 2025, 8.3% of card borrowers and 4.6% of auto borrowers were at least 90 days behind, both below the U.S. shares (Federal Reserve Bank of Philadelphia).
Every bordering state scores lower
Iowa, North Dakota, South Dakota and Wisconsin all have lower scores than Minnesota. North Dakota has the lowest score in this group. The comparison counts state averages, not the number of people experiencing hardship.
The bars show the State Distress Index score. Minnesota is higher than 4 of its 4 neighboring states.
Minnesota has stayed in the lower half of the state list
Highest recorded score
The state reached 42 in the third quarter of 2007, ranking 30th for distress.
Lowest recorded score
Minnesota scored 6 in several quarters between 2014 and 2022. Its earliest such quarter was the second quarter of 2014.
The current edition
The history chart ends in the first quarter of 2025 at 20; newer inputs produce today’s score of 30. The two dates come from different data releases.
Minnesota’s quarterly score has remained below the midpoint of the scale
Quarterly State Distress Index score, third quarter of 2006 to first quarter of 2025; today’s score is 30.
Is Minnesota expensive to live in? Rent is below the U.S. median, but many renters are stretched
The Census Bureau’s 2020–2024 survey puts Minnesota’s median monthly gross rent at $1,280, below the U.S. median of $1,413. In its separate 2024 annual survey, 23.0% of Minnesota renter households spent at least half their income on rent and utilities, versus 26.1% nationwide. A lower median rent does not mean housing is affordable to every renter.
Median monthly gross rent
$1,280
U.S. $1,413
Census Bureau, 2020–2024
Renters spending at least half their income on housing
23.0%
U.S. 26.1%
Census Bureau, 2024
The state average also hides local differences. The Census Bureau’s five-year rent estimates put Minnesota above each of its bordering states: Iowa $972, North Dakota $954, South Dakota $946 and Wisconsin $1,087. Yet rent is only one expense, and these medians do not price a particular home or neighborhood.
How many renters pay half their income for housing?
The annual Census estimates let us follow the share of renters with the heaviest housing costs. The chart compares that share in Minnesota with the national share through 2024.
A smaller share of Minnesota renters faces the heaviest housing costs
Share of renter households spending at least half their income on rent and utilities, Census Bureau one-year estimates through 2024.
This page measures rent and housing burden, not a complete cost-of-living index for groceries, transportation, taxes and child care. Poverty and household income →
Which Minnesota counties are poorest, and which face the most financial strain?
Beltrami County had Minnesota’s highest poverty rate in the Census Bureau’s 2024 county estimates, at 17.3%. Mahnomen County had the highest County Distress Index score, 64; its median household income was the lowest in the state, $60,812. Carver County scored 2, the state’s lowest. These rankings answer different questions: the Census rate counts residents below a poverty threshold, while our index combines household finances, work, housing costs and income.
The highest county scores are in Mahnomen, Beltrami and Wadena
Minnesota’s 87 counties, shaded by County Distress Index score with data through August 2026.
Loading the county map…
The county map could not be loaded. Every county is in the lists on this page.
Most distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 1 | Mahnomen | 64 | 16.4% |
| 2 | Beltrami | 54 | 17.3% |
| 3 | Wadena | 50 | 15.1% |
| 4 | Pine | 46 | 13.5% |
| 5 | Ramsey | 45 | 13.3% |
| 6 | Swift | 44 | 13.2% |
| 7 | Lake | 38 | 10.0% |
| 8 | Itasca | 37 | 11.0% |
| 9 | Mower | 37 | 9.2% |
| 10 | Aitkin | 37 | 13.9% |
Least distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 83 | Nicollet | 5 | 7.8% |
| 84 | Douglas | 4 | 9.3% |
| 85 | Rock | 4 | 8.9% |
| 86 | Wabasha | 3 | 7.0% |
| 87 | Carver | 2 | 4.7% |
Rank among Minnesota’s 87 counties, with the most distressed first. The rank uses unrounded scores, so two counties can print the same score but have different ranks. Poverty is the Census Bureau’s 2024 estimate.
Every county, by score
Mahnomen, Beltrami and Wadena are the only Minnesota counties scoring at least 50. Most counties fall in the lowest score group. These county scores rank counties nationally; the state score ranks Minnesota among states and D.C.
0 score 80–100
0 score 70–79
14 score 30–49
Pine, Ramsey, Swift, Lake, Itasca, Mower, Aitkin, Isanti, Kanabec, St. Louis, Mille Lacs, Clearwater, Faribault, Freeborn
70 score 0–29
Benton, Hubbard, Stearns, Crow Wing, Carlton, Cass, Koochiching, Grant, Renville, Chisago, Meeker, Martin, Nobles, Steele, Becker, Redwood, Blue Earth, Hennepin, Anoka, Norman, Chippewa, Traverse, Big Stone, Clay, Todd, Pennington, Lincoln, Rice, Polk, Dakota, Pipestone, Lyon, Dodge, Kandiyohi, McLeod, Cottonwood, Pope, Sherburne, Wilkin, Morrison, Brown, Waseca, Sibley, Lake of the Woods, Watonwan, Otter Tail, Wright, Goodhue, Winona, Cook, Washington, Le Sueur, Lac qui Parle, Houston, Yellow Medicine, Red Lake, Roseau, Scott, Jackson, Murray, Marshall, Olmsted, Stevens, Kittson, Fillmore, Nicollet, Douglas, Rock, Wabasha, Carver
Beltrami is poorest; Mahnomen is most distressed
Beltrami’s poverty rate of 17.3% was the state’s highest in 2024, while its distress score of 54 placed it second in Minnesota. Mahnomen’s poverty rate was 16.4%, second highest, yet its distress score was the highest. Blue Earth County offers a sharper mismatch: its poverty rate was 14.1%, among the state’s highest, while its distress score was 24. The index also counts jobs, late payments, collections and renter costs. A poverty rate alone cannot explain why a county ranks where it does.
The five poorest counties
| County | Poverty | Distress rank |
|---|---|---|
| Beltrami | 17.3% | 2nd |
| Mahnomen | 16.4% | 1st |
| Wadena | 15.1% | 3rd |
| Blue Earth | 14.1% | 34th |
| Clearwater | 14.1% | 15th |
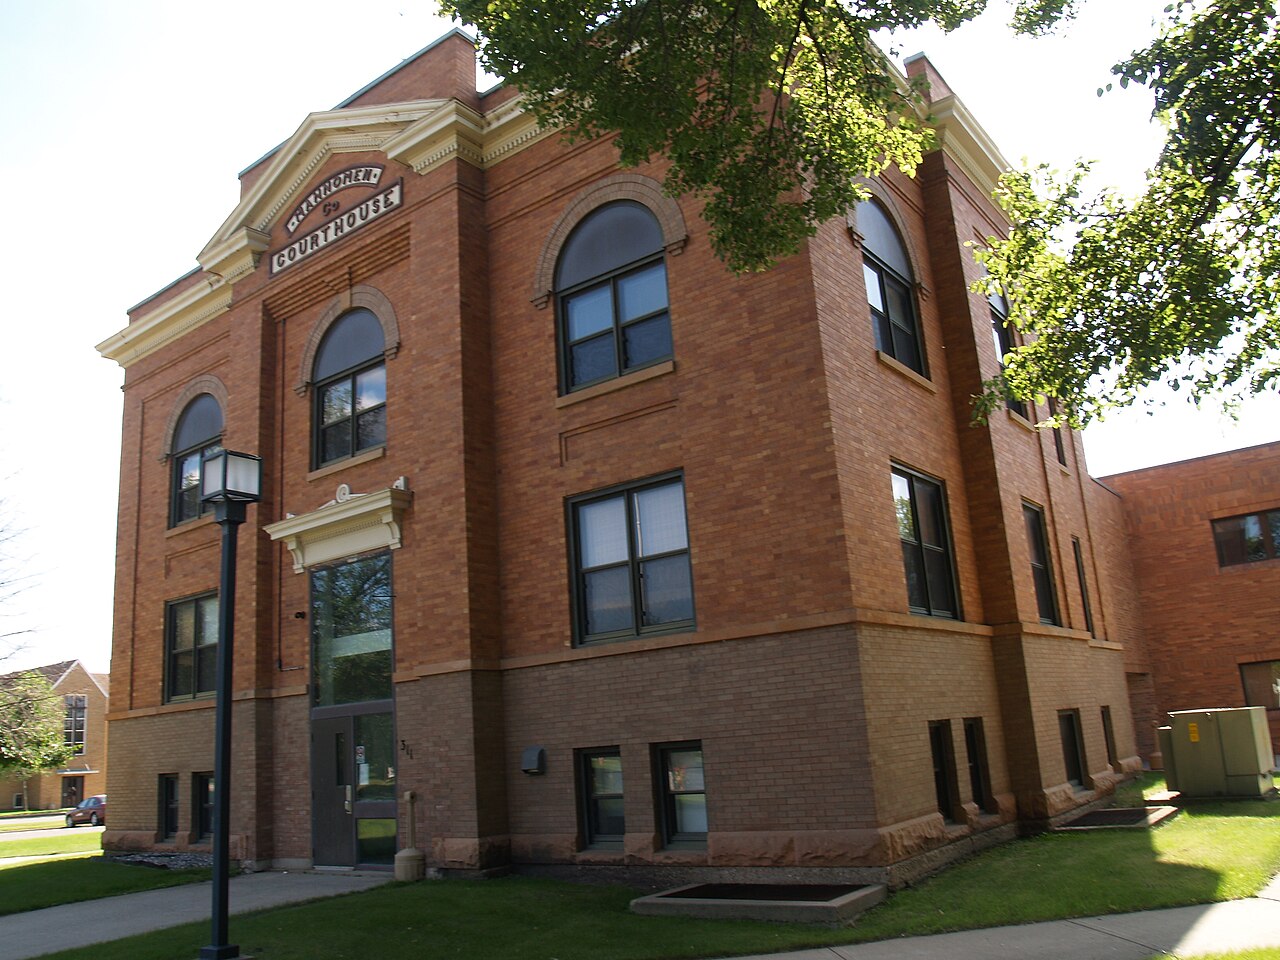
The Mahnomen County Courthouse stands in the county with Minnesota’s highest financial-distress score, 64. Its 2024 median household income was $60,812, the state’s lowest (U.S. Census Bureau).

The Twin Cities counties do not have the same profile
Ramsey County, home to St. Paul, scores 45, among Minnesota’s highest county scores. Neighboring Hennepin County, home to Minneapolis, scores 24. The Census Bureau puts Ramsey’s 2024 poverty rate at 13.3% and Hennepin’s at 9.5%. These are county rates, not a count of residents in poverty; Hennepin has many more residents.
American Default Research, County Distress Index; U.S. Census Bureau, Small Area Income and Poverty Estimates.
Is Minnesota a poor state? Its poverty rate is among the lowest
In 2024, the Census Bureau estimated that 9.3% of Minnesotans lived in poverty, tied for 5th lowest among states and D.C., compared with 12.1% nationally. The state’s median household income was $87,120, above the U.S. figure of $81,604. The two figures describe different parts of the income distribution.
Residents in poverty
9.3%
U.S. 12.1%
2024, Census Bureau
Children in poverty
9.6%
U.S. 15.5%
2024, Census Bureau
Median household income
$87,120
U.S. $81,604
2024, Census Bureau
Statewide poverty has remained under the national rate in the published Census series. The chart keeps the state and U.S. on the same measure and shows the years actually published.
Minnesota’s poverty rate remains below the U.S. rate
Census Bureau Small Area Income and Poverty Estimates, published years from 1989 through 2024; some early years are missing.
State averages leave room for deep county differences
Beltrami County’s 17.3% poverty rate was almost twice Minnesota’s statewide rate, while Mahnomen had the state’s lowest median household income. Both counties appear near the top of our county distress list. Compare every county →
What is Minnesota’s unemployment rate?
Minnesota’s seasonally adjusted unemployment rate was 4.4% in August 2026, compared with 4.1% for the U.S. (U.S. Bureau of Labor Statistics). A year earlier, Minnesota’s rate was 3.9%. The jobs part of its distress score is high relative to its other parts because it ranks the state against its peers.
Unemployment rate
4.4%
U.S. 4.1%
August 2026, adjusted for season
Annual average
3.9%
U.S. 4.3%
2025, U.S. Bureau of Labor Statistics
The longer BLS series puts this recent increase in context. The chart traces Minnesota and the country on the same monthly, seasonally adjusted basis.
Minnesota’s jobless rate moved above the U.S. rate in 2026
Monthly seasonally adjusted unemployment rates, Minnesota and the U.S., through August 2026.
The unemployment rate counts people working or looking for work. It does not measure wages, underemployment or the number who have stopped looking. See the state’s four score parts →
What changed in Minnesota in the past year
-
Oct. 1, 2026
Medical Assistance eligibility narrowed for some noncitizen adults
Minnesota’s Department of Human Services says the federal budget law changed which immigration statuses qualify for full Medical Assistance coverage for some adults beginning Oct. 1. Pregnant people and children follow different rules. The department lists the affected groups and its state-funded coverage arrangements.
Minnesota Department of Human Services, federal Medicaid changes
-
March 1, 2026
Federal SNAP eligibility narrowed for some noncitizens
The Minnesota Department of Children, Youth, and Families says the federal budget law narrowed the noncitizen categories eligible for SNAP from March 1. Its estimate of the effect is a projection, not a count of people who lost benefits.
Minnesota Department of Children, Youth, and Families, federal SNAP provisions
-
Jan. 1, 2026
The state paid-leave program began
Minnesota Paid Leave began covering qualifying family and medical leave. It replaces part of eligible workers’ wages and is funded by premiums from employers and workers. This is a new program, separate from unemployment insurance.
Minnesota Department of Employment and Economic Development, Paid Leave
-
Jan. 1, 2026
The minimum wage rose with inflation
The Minnesota Department of Labor and Industry raised the state minimum wage through its annual inflation adjustment. Minneapolis and St. Paul have their own higher local rates.
How many Minnesotans are behind on bills?
In early 2025, the Federal Reserve Bank of Philadelphia found debt in collections for 7.5% of Minnesotans with a credit file. The comparable U.S. share was 13.2%. The same records show that 8.3% of Minnesota card borrowers were at least 90 days behind. The shares were 4.6% for auto-loan borrowers and 0.8% for mortgage borrowers.
Those four measures count people with credit records or a particular kind of loan. The chart places Minnesota beside the U.S. within each measure; it does not combine them into one default rate.
Minnesota’s share of residents with debt in collections was lowest among the states and D.C. The rates here describe household credit, not state government debt.
The dollars owed tell a different part of the story
The Federal Reserve Bank of New York measures balances per person with a credit report, rather than the share of borrowers late on a payment. Minnesota’s total household debt was $63,860 per person at the end of 2025, near the national $63,200; it had been $55,380 at the end of 2019. These are nominal dollars, without an inflation adjustment.
| Measure | Minnesota | U.S. |
|---|---|---|
| Total household debt per credit-file person, end of 2025 | $63,860 U.S. $63,200 | $63,200 |
| Card balance per credit-file person, end of 2025 | $3,990 U.S. $4,350 | $4,350 |
| Credit card balances seriously late, end of 2025 | 8.6% U.S. 12.4% | 12.4% |
| Mortgage balances seriously late, end of 2025 | 0.6% U.S. 0.9% | 0.9% |
Federal Reserve Bank of New York Consumer Credit Panel / Equifax. The delinquency rows concern dollars in the balance, not the share of borrowers in the Philadelphia Fed chart.
How common is bankruptcy in Minnesota?
U.S. Courts recorded 176.0 bankruptcy cases per 100,000 Minnesota residents in 2025, compared with 166.3 nationally. The rate uses 2025 population and counts cases filed, not households that finished a case or people who could not pay a debt.
Cases per 100,000 residents
176.0
U.S. 166.3
2025 population
Cases filed
10,260
2025, U.S. Courts
Chapter 13 share
23.0%
U.S. 35.9%
2025 filings
The state recorded more cases in 2025 than in 2024. A case count can change when filing rules or population changes, so the per-person rate is the state comparison. See the full bankruptcy statistics →
How many Minnesotans receive SNAP food benefits?
The U.S. Department of Agriculture counted 428,540 people receiving SNAP in Minnesota in July 2026. That equals 7.4% of the state’s 2025 population, compared with 10.5% across the states and D.C. The enrollment rate is our calculation; it is not a poverty rate.
People receiving SNAP
428,540
July 2026, U.S. Department of Agriculture
Share of residents
7.4%
U.S. 10.5%
Using 2025 population
The federal budget law changed eligibility and work rules. Minnesota’s Department of Children, Youth, and Families says expanded work requirements began in November 2025 and a narrower noncitizen eligibility rule began in March 2026. A change in enrollment can reflect rules as well as need. What changed in Minnesota →
How foreclosure works in Minnesota
Minnesota law allows a mortgage foreclosure by advertisement, with a sheriff’s sale after published notice, and also permits foreclosure through a court action. For a covered occupied home, state law requires counseling information before the foreclosure notice is recorded. The precise path depends on the loan and the foreclosure papers.
Under Minnesota Statutes § 580.03, a sale by advertisement follows six consecutive weeks of published notice. The statute also requires service on an occupant at least four weeks before the sale. For most residential properties, § 580.23 gives a six-month period after the sale to redeem, subject to exceptions. The federal mortgage-servicing rule generally limits the first foreclosure notice or filing until a loan is more than 120 days behind, with exceptions (12 CFR 1024.41).
- Sale without a court case
- Permitted
- Published sale notice
- Six weeks
- Most home redemption periods
- Six months
- Counseling information
- Required for covered homes
General statutory rules, not a personal timeline. Minnesota Statutes §§ 580.021, 580.03 and 580.23; 12 CFR 1024.41. How foreclosure works in Minnesota →
Minnesota Housing directs homeowners having trouble with a mortgage to the Minnesota Homeownership Center’s foreclosure prevention advisers. The federal Homeowner Assistance Fund was a separate temporary program; its current application status is described on the state law and help page.
What Minnesota homeowners report in mortgage complaints
The Consumer Financial Protection Bureau has received 5,220 mortgage complaints from Minnesota since 2012. The most common subjects include the payment process (1,272) and loan modification, collection or foreclosure (1,378). A complaint is a borrower’s report, not a verified finding against a company.
- Oct. 6, 2026 PennyMac Payment process: releasing the lien Closed with explanation
- Oct. 5, 2026 U.S. Bank Payment process: trouble reaching the company to fix a problem with the loan In progress
- Oct. 3, 2026 Rocket Mortgage Struggling to pay: an existing modification, forbearance or other relief Closed with explanation
- Oct. 1, 2026 U.S. Bank Payment process In progress
- Sept. 29, 2026 Shellpoint / NewRez Payment process: paying off the loan Closed with explanation
- Sept. 29, 2026 Shellpoint / NewRez Payment process: trouble reaching the company to fix a problem with the loan Closed with explanation
- Sept. 29, 2026 New American Funding Struggling to pay: trouble reaching the company about a modification, forbearance or foreclosure In progress
- Sept. 28, 2026 Freedom Mortgage Payment process: escrow, taxes or insurance In progress
- Sept. 28, 2026 Rocket Mortgage Payment process: escrow, taxes or insurance Closed with explanation
- Sept. 26, 2026 CMG Financial Payment process: escrow, taxes or insurance Closed with explanation
The latest ten Minnesota complaints about payment trouble or help with an existing mortgage, from the Consumer Financial Protection Bureau public database. New-loan and credit-bureau complaints are excluded. The bureau does not verify the accounts. Search the CFPB complaint database →
What to watch before the next edition
The next jobs report and scheduled federal benefit changes can alter the context for this October edition.
-
Nov. 19, 2026
October employment and unemployment figures
Minnesota’s Department of Employment and Economic Development schedules its October state employment report for Nov. 19. The release may revise earlier months.
-
Jan. 1, 2027
Medical Assistance work reporting and more frequent renewals
The state says some adults covered through the Medical Assistance expansion will have new work-reporting rules and renew coverage every six months from January. Exemptions and individual circumstances matter.
Minnesota Department of Human Services, federal Medicaid changes
-
Oct. 1, 2027
A federal SNAP benefit formula change is scheduled
Minnesota’s children and families department says the federal food-benefit formula changes at the start of the next federal fiscal year. Its impact estimate is a forecast, not an observed household payment.
Minnesota Department of Children, Youth, and Families, federal SNAP provisions
Where Minnesota ranks highest and lowest
The state looks different depending on the measure. Work and bankruptcy place it closer to the middle than its low poverty and late-payment rates do.
| Measure | Minnesota | U.S. | Rank | Latest data |
|---|---|---|---|---|
| Residents in poverty Tied for 46th highest · 2024 | 9.3% U.S. 12.1% | 12.1% | Tied for 46th highest | 2024 |
| Children in poverty 49th highest · 2024 | 9.6% U.S. 15.5% | 15.5% | 49th highest | 2024 |
| Median household income 37th lowest · 2024 | $87,120 U.S. $81,604 | $81,604 | 37th lowest | 2024 |
| Median monthly gross rent 29th lowest · 2020–2024* | $1,280 U.S. $1,413 | $1,413 | 29th lowest | 2020–2024* |
| Renters spending half their income on housing Tied for 37th highest · 2024 | 23.0% U.S. 26.1% | 26.1% | Tied for 37th highest | 2024 |
| Unemployment rate, three-month average Tied for 14th highest · June–August 2026 | 4.4% U.S. 4.1% | 4.1% | Tied for 14th highest | June–August 2026 |
| Residents receiving SNAP 40th highest · July 2026 | 7.4% U.S. 10.5% | 10.5% | 40th highest | July 2026 |
| People with debt in collections 51st highest · Early 2025 | 7.5% U.S. 13.2% | 13.2% | 51st highest | Early 2025 |
| Credit card borrowers 90 or more days late Tied for 49th highest · Early 2025 | 8.3% U.S. 13.5% | 13.5% | Tied for 49th highest | Early 2025 |
| Auto borrowers 90 or more days late Tied for 46th highest · Early 2025 | 4.6% U.S. 8.5% | 8.5% | Tied for 46th highest | Early 2025 |
| Bankruptcy filings per 100,000 residents 20th highest · 2025 | 176.0 U.S. 166.3 | 166.3 | 20th highest | 2025 |
| Household debt per person with a credit report 19th highest · End of 2025 | $63,860 U.S. $63,200 | $63,200 | 19th highest | End of 2025 |
| Mortgages with less than 10% equity Tied for 36th highest · Second quarter 2026 | 3.2% U.S. 4.7% | 4.7% | Tied for 36th highest | Second quarter 2026 |
| Income per person 37th lowest · 2024 | $75,603 U.S. $73,204 | $73,204 | 37th lowest | 2024 |
Ranks cover the 50 states and D.C.; identical printed values tie. *The Census rent measure is a five-year survey estimate. Philadelphia Fed measures count people with a credit record or a particular loan; the New York Fed debt measure counts dollars per credit-file person. Sources and method identifies each producer. Download the table as CSV.
Questions about Minnesota
Is Minnesota an expensive state to live in?
The Census Bureau puts Minnesota’s 2020–2024 median monthly gross rent at $1,280, below the U.S. $1,413. Yet 23.0% of Minnesota renter households spent at least half their income on housing in 2024. Those are housing measures, not a complete price index. Cost of living →
Is Minnesota a poor state?
Its 2024 poverty rate was 9.3%, compared with 12.1% for the U.S., among the lowest of states and D.C. (U.S. Census Bureau, Small Area Income and Poverty Estimates). The typical Minnesota household earned $87,120. Poverty and income →
Which is Minnesota’s poorest county?
Beltrami County had the highest poverty rate in the Census Bureau’s 2024 estimates, 17.3%. Mahnomen County had the lowest median household income, $60,812, and the highest County Distress Index score, 64. “Poorest” depends on the measure. County comparisons →
What is Minnesota’s unemployment rate?
The U.S. Bureau of Labor Statistics put it at 4.4% in August 2026, seasonally adjusted, compared with 4.1% nationally. Jobs and unemployment →
Does foreclosure require a court in Minnesota?
Minnesota permits foreclosure by advertisement, which ends in a sheriff’s sale without a foreclosure lawsuit, and also allows a court action. Published notice, service and redemption rules differ by path and property. Minnesota foreclosure overview →
Cite or reuse Minnesota’s data
The edition figures, chart images and county comparisons can be quoted with attribution to American Default Research.
State Distress Index
Minnesota
36thmost distressed state
of the 50 states and D.C.
More distressed than 30% of the other states and D.C.
Minnesota is the 36th most distressed of the 50 states and D.C. on the American Default Research State Distress Index, scoring 30. Its jobs component scores 72, while its late-payment component scores 4. Beltrami County had the highest 2024 poverty rate in the state, 17.3% (U.S. Census Bureau); Mahnomen County had the highest County Distress Index score, 64.
Reporters can request an interview or a custom cut of the data at press@americandefault.org.
Sources and method
We gather the data, run the numbers and research each state ourselves.
This edition: October 2026 · Next edition expected March 2027
- State and county unemploymentU.S. Bureau of Labor Statistics, Local Area Unemployment Statisticsthrough August 2026
- State and county poverty and household incomeU.S. Census Bureau, Small Area Income and Poverty Estimates1989–2024
- Rent, homeowner and renter costsU.S. Census Bureau, American Community Survey2020–2024 five-year and 2024 one-year estimates
- Income per personU.S. Bureau of Economic Analysis, regional economic accounts2024
- Collections and late payments by borrowersFederal Reserve Bank of Philadelphia, Consumer Credit Explorerfirst quarter of 2025
- Debt balances and dollars behindFederal Reserve Bank of New York, Consumer Credit Panel / Equifaxend of 2019 and 2025
- Bankruptcy filingsAdministrative Office of the U.S. Courts, Table F-22025
- Food assistance participationU.S. Department of Agriculture, SNAP data tablesJuly 2026
- Mortgage equityFederal Housing Finance Agency, National Mortgage Databasesecond quarter of 2026
- Mortgage complaintsConsumer Financial Protection Bureau, public complaint databasethrough October 2026
- Mortgage foreclosure rulesMinnesota Revisor of Statutes, chapters 580 and 581; Consumer Financial Protection Bureau, 12 CFR 1024.41as of October 2026
- State paid leave and minimum wageMinnesota Department of Employment and Economic Development; Minnesota’s labor department2026
- Food and health coverage rule changesMinnesota Department of Children, Youth, and Families; Minnesota Department of Human Services2025–2027
- Housing counselorsU.S. Department of Housing and Urban DevelopmentOctober 2026
- PhotoAndrew Filer via Wikimedia Commons, CC BY-SA 2.0June 2007
The state score brings together employment, past-due credit, debt collection and bankruptcy, and the heaviest renter housing costs. Each part combines the measures within it. The four-part average is then compared with the other states and D.C.; a score of 80 would mean more distressed than 80% of those places. The county index uses additional measures and ranks counties among counties. The full state method →
We write with AI tools, and Ross Kilburn checks and reviews every page before it's published.
Get the next Minnesota edition by email
One email each time a new Minnesota edition is out; the next is expected in March 2027. Unsubscribe anytime.
Thanks, that helps.