In South Carolina, 22.1% of people had a debt 90 or more days late, tied for 6th highest
Each state is shaded by how distressed its households are, from green (least) to red (most), with data through September 2026. South Carolina scores 84 out of 100.
In early 2025, 22.1% of South Carolinians with credit records had a debt 90 or more days late; that share was tied for 6th highest nationally. Renters paying half their income for housing add to the state’s strain, while bankruptcy filings are relatively rare. Williamsburg, Marlboro and Bamberg top South Carolina’s distress ranking. Beaufort, Lancaster and Charleston appear at the low end.
- Score
- 84/100
- Data through
- September 2026
- Edition
- October 2026
Next edition expected March 2027
How South Carolina ranks among the states
Among the 50 states and D.C., South Carolina ranks 9th on financial distress. Late payments and renters’ housing costs put it there; poverty isn’t one of the score’s measures. In early 2025, 18.3% of South Carolinians with a credit record had a debt in collections, the 6th highest share in the country (Federal Reserve Bank of Philadelphia), and the late-payments part of its score is tied for 7th highest. Yet few people here file for bankruptcy: the state’s filing rate in 2025 was the 13th lowest of the 50 states and D.C. (see bankruptcy). Neither its poverty rate nor its unemployment rate is among the 10 highest.
What drives the score
Four parts make up the score. Each measure behind a part is ranked against the other states from 0 to 100, and each part averages its measures. South Carolina’s four parts average 69. Its score, 84, is the share of the other states and D.C. whose four-part average is lower, which is why it isn’t simply the average of the parts.
- Late payments84More card, car-loan and mortgage borrowers 90 or more days behind than the U.S. average (early 2025)
- Renters’ housing costs7726.6% of renter households spent half or more of their income on housing in 2024 (U.S. 26.1%)
- Jobs58Unemployment averaged 4.2% from June to August 2026, against 4.1% for the U.S.
- Collections and bankruptcy57More people with a debt in collections than in most states (early 2025), but one of the lowest bankruptcy filing rates (2025)
Beside its neighbors
Georgia, to the south and west, scores a little lower than South Carolina. North Carolina, to the north, scores far lower, near the middle of the states.
- Georgia 80
- South Carolina 84
- North Carolina 44
State Distress Index score, 0 to 100. North Carolina’s typical household earned $74,055 in 2024, close to South Carolina’s $72,507 (Census Bureau). North Carolina’s unemployment rate was lower in August 2026, 3.5% (Bureau of Labor Statistics), and it had a smaller share of renters paying half their income for housing, 24.9% in 2024 (Census Bureau).
Jobs drove its swings: down to the middle in 2019, back near the top in 2024
At its worst
Ranked 4th most distressed, with a score of 94, from the start of our full quarterly history in the third quarter of 2006 through the second quarter of 2007, and again in the second and third quarters of 2024. By the end of 2007 the score had dropped to 72; the first step came in the third quarter, when the renters’ costs part fell from 60 to 36.
By early 2025
Ranked 11th most distressed, with a score of 80. Its least distressed point in our quarterly history came in the third quarter of 2019: 25th, with a score of 52.
Why it moved
Mostly jobs. The jobs part sank from 84 at the end of 2014 to 10 in the third quarter of 2019, the year the state’s unemployment rate averaged 2.8%, its lowest in yearly figures back to 1990. It climbed again from 38 at the end of 2023 to 82 by the third quarter of 2024. Late payments never eased much: that part hasn’t dropped below 81 in any quarter since 2006. Today South Carolina ranks 9th, because of renters’ costs (see the note under the chart).
South Carolina was the 4th most distressed state in 2006 and 2007 and again in 2024, with a dip to 25th in 2019
Quarterly State Distress Index score, 0 to 100, from the third quarter of 2006 through the first quarter of 2025.
Is South Carolina a poor state?
It’s poorer than most states on income, and above the U.S. on poverty, though not among the 10 highest states. In 2024, 13.3% of South Carolinians lived in poverty, tied for 13th highest among the 50 states and D.C., against 12.1% for the U.S. The typical household earned $72,507, the 14th lowest (Census Bureau, Small Area Income and Poverty Estimates). Income per person, which adds up wages, business and investment income and government benefits, was $60,776, the 7th lowest (Bureau of Economic Analysis). The state’s poverty rate has topped the nation’s in every Census estimate since 1989, but in 2024 the gap was the narrowest yet.
Residents in poverty
13.3%
U.S. 12.1%
Tied for 13th highest among the 50 states and D.C. (2024)
Median household income
$72,507
U.S. $81,604
14th lowest among the 50 states and D.C. (2024)
Children in poverty
18.1%
U.S. 15.5%
11th highest among the 50 states and D.C. (2024)
South Carolina’s poverty rate has been above the nation’s in every Census estimate since 1989, but the gap is now the smallest on record
Percent of South Carolinians and of all Americans living in poverty, 1989 to 2024. No Census state estimates for 1990 to 1992 or 1994.
Fewer South Carolinians get SNAP, and the drop began before the new work rules
In June 2026, 8.9% of South Carolinians got SNAP food benefits, the 19th lowest share of the 50 states and D.C. and below the U.S. share of 10.7% (U.S. Department of Agriculture). The count fell 14.2% in a year, from 570,687 in June 2025 to 489,699, dropping every month along the way. Most of that fall came before federal work rules reached more adults on Feb. 2, 2026: by January the count was already down to 514,847 (see what changed). A smaller count doesn’t mean fewer people need help, and it doesn’t say why people left.
To apply for SNAP or other help: South Carolina Department of Social Services →
Where South Carolina’s income comes from
Government benefits, such as Social Security, Medicare and veterans’ benefits, made up 23.4% of all income in South Carolina in 2024, the 7th highest share of the 50 states and D.C., against 18.3% nationwide. Wages and salaries made up 45.3%, the 14th lowest (Bureau of Economic Analysis).
| Measure | South Carolina | U.S. | Rank |
|---|---|---|---|
| Residents 65 and older Tied for 12th highest | 18.9% U.S. 17.2% | 17.2% | Tied for 12th highest |
| Residents with a disability 13th highest | 14.6% U.S. 13.3% | 13.3% | 13th highest |
| Residents without health insurance Tied for 12th highest | 9.6% U.S. 8.4% | 8.4% | Tied for 12th highest |
| Adults without a high school diploma Tied for 18th highest | 9.9% U.S. 10.4% | 10.4% | Tied for 18th highest |
Census Bureau, American Community Survey, 2020 to 2024. Rank 1 is the highest share among the 50 states and D.C.
South Carolina’s poorest and most distressed counties
Allendale County, on the Savannah River, is South Carolina’s poorest county: 31.6% of its residents lived in poverty in 2024, more than in any other of the state’s 46 counties (Census Bureau, Small Area Income and Poverty Estimates). Williamsburg County, whose seat is Kingstree, is the most distressed on our County Distress Index, which rates every U.S. county on how strained its household finances are. It ranks 27th of 3,144 counties nationwide, and five South Carolina counties are among the country’s 100 most distressed (see the list). Beaufort County, home to Hilton Head Island, is the least distressed in the state.
South Carolina’s 10 most distressed counties form a band from the Pee Dee southwest to the Savannah River; the least distressed are around Charleston, Hilton Head, Greenville and the Charlotte suburbs
Scores from 0 to 100 on our County Distress Index for all 46 South Carolina counties, with data through August 2026.
Loading the county map…
The county map could not be loaded. Every county is in the lists on this page.
Most distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 1 | Williamsburg | 99 | 25.5% |
| 2 | Marlboro | 98 | 30.2% |
| 3 | Bamberg | 97 | 24.2% |
| 4 | Darlington | 97 | 24.6% |
| 5 | Lee | 96 | 22.8% |
| 6 | Orangeburg | 96 | 21.0% |
| 7 | Marion | 94 | 30.8% |
| 8 | Sumter | 93 | 16.7% |
| 9 | Barnwell | 93 | 20.3% |
| 10 | Colleton | 92 | 21.0% |
Least distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 42 | Greenville | 43 | 9.9% |
| 43 | York | 42 | 8.8% |
| 44 | Lancaster | 39 | 10.2% |
| 45 | Charleston | 38 | 10.3% |
| 46 | Beaufort | 38 | 8.4% |
Rank in South Carolina, 1 = most distressed. Ranks follow unrounded scores, so two counties can show the same score and still rank apart: Bamberg and Darlington, Lee and Orangeburg, Sumter and Barnwell. Poverty rates are Census Bureau figures for 2024.
Every county, by score
Of South Carolina’s 46 counties, 23 score 80 or more; together they hold 24.8% of the state’s people. Richland County, home to Columbia, the capital, is one of them, ranking 20th in the state. The other big counties score lower: Greenville ranks 42nd, Charleston 45th, and Horry, home to Myrtle Beach, 26th. No county scores below 30.
23 score 80–100
Williamsburg, Marlboro, Bamberg, Darlington, Lee, Orangeburg, Marion, Sumter, Barnwell, Colleton, Dillon, Fairfield, Chesterfield, Union, Allendale, Florence, Clarendon, Calhoun, Chester, Richland, Cherokee, Hampton, Laurens
13 score 50–69
Aiken, Newberry, Pickens, Greenwood, Spartanburg, Georgetown, Kershaw, Abbeville, Dorchester, Berkeley, Anderson, Oconee, McCormick
6 score 30–49
Lexington, Greenville, York, Lancaster, Charleston, Beaufort
Poorest isn’t the same as most distressed
Our county score has five equal parts: late payments; collections and bankruptcy; jobs; housing costs; and a fifth that weighs poverty along with income, disability and health insurance. So the poorest county isn’t necessarily the most distressed. Allendale ranks 15th on distress: it scores lower on collections and bankruptcy than every county ranked above it. The split runs the other way, too. Sumter County’s poverty rate is tied for 22nd highest in the state, yet it ranks 8th on distress, and Fairfield County’s is tied for 19th highest while it ranks 12th. Both score high on late payments and on collections and bankruptcy. Other sites may name a different poorest county because they use another Census survey or year; ours are the Census Bureau’s 2024 county estimates.
The five poorest counties
| County | Poverty | Distress rank |
|---|---|---|
| Allendale | 31.6% | 15th |
| Marion | 30.8% | 7th |
| Marlboro | 30.2% | 2nd |
| Williamsburg | 25.5% | 1st |
| Darlington | 24.6% | 4th |
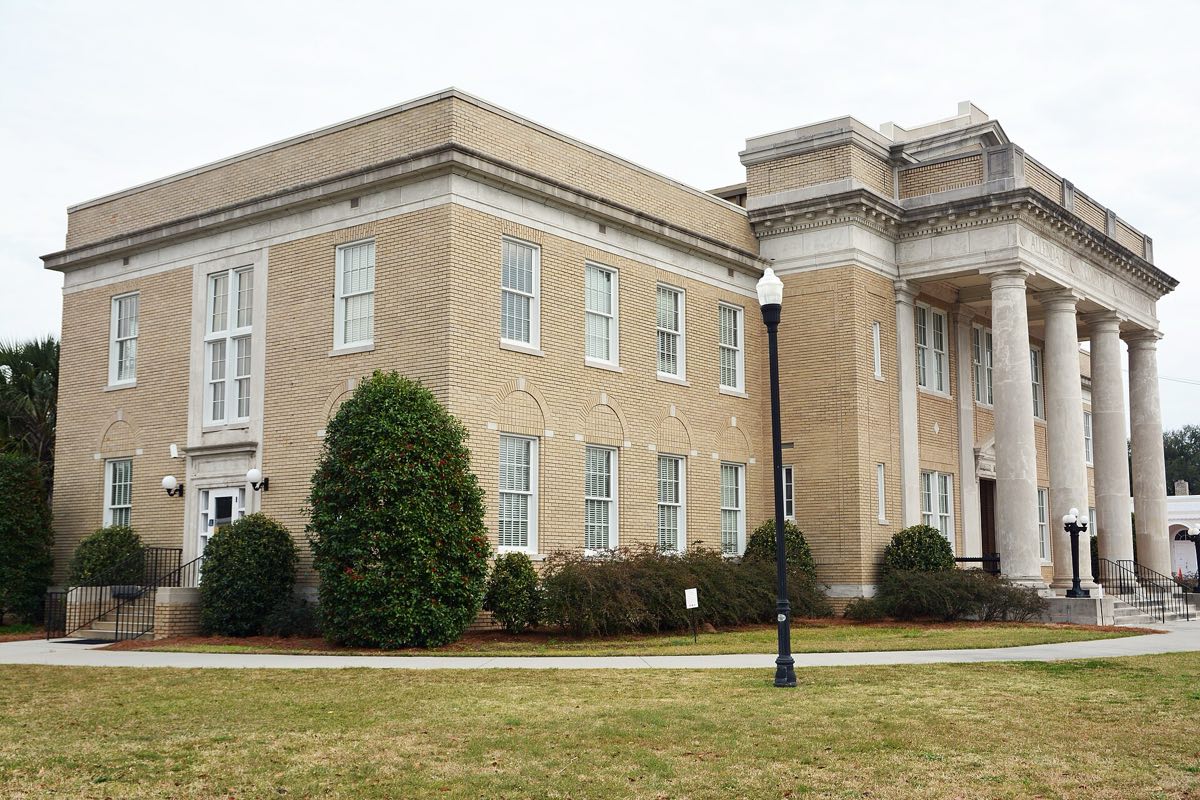
The Allendale County Courthouse in Allendale, photographed in 2017. The first courthouse was nearly destroyed by fire in 1998, and the rebuilt one kept its outer walls (South Carolina Encyclopedia). Allendale County counted 8,039 people in the 2020 census, about half its 1920 count of 16,098, and its typical household earned $41,336 in 2024, the lowest in the state (Census Bureau).
Sources: U.S. Census Bureau; South Carolina Encyclopedia. Photo: Judson McCranie (Bubba73), Wikimedia Commons, CC BY-SA 3.0.

On the coast, the strain is housing costs
Among the 10 South Carolina counties where renters’ housing costs weigh most on our county score, six are on the coast or around Charleston: Jasper, Horry, Charleston, Berkeley, Beaufort and Dorchester. Charleston and Beaufort rank among the least distressed counties overall, yet both score higher on housing costs than Williamsburg, the most distressed.
American Default Research, County Distress Index, from Census Bureau rent and income figures.
How expensive is it to live in South Carolina?
Rent is below the middle of the states, but so are incomes, and many renters are stretched. The median rent was $1,180 a month from 2020 to 2024, the 22nd lowest of the 50 states and D.C., against $1,413 nationwide (Census Bureau). Yet in 2024, 26.6% of renter households paid half or more of their income for rent and utilities, tied for 9th highest, up from 25.6% in 2023. That rise lifted the renters’ part of the state’s score above where it stood in early 2025 (see how it ranks). We don’t measure food prices, home prices, insurance or utility bills, so we can’t rank the overall cost of living.
Median rent, a month
$1,180
U.S. $1,413
22nd lowest among the 50 states and D.C. (2020 to 2024)
Renters spending half or more of income on housing
26.6%
U.S. 26.1%
Tied for 9th highest among the 50 states and D.C. (2024)
Homes their owners live in
71.9%
U.S. 65.2%
9th highest among the 50 states and D.C. (2020 to 2024)
South Carolina renters were squeezed hardest in 2011, and the share paying half their income rose again in 2024
Percent of renter households whose rent and utilities take half or more of their income, South Carolina and the U.S., 2005 to 2024. There is no 2020 figure: the Census Bureau skipped that year’s one-year estimates.
What a basic budget costs
MIT’s Living Wage Calculator puts the cost of basic needs for one adult with no children in South Carolina at $46,469 a year before taxes, the 22nd lowest of the 50 states and D.C. overall. For a family of four with both parents working, the figure is $106,474 (2025 dollars).
Electric bills aren’t in our data. New Dominion Energy South Carolina rates took effect in July 2026 and Duke Energy Carolinas’ rates were set to rise again in August; Duke Energy Progress is appealing a ruling that held off another increase (see what changed).
Rent is lower than in Georgia or North Carolina
| Measure | South Carolina | Georgia | North Carolina |
|---|---|---|---|
| Median rent, a month, 2020 to 2024 North Carolina $1,228 | $1,180 Georgia $1,393 | $1,393 | $1,228 |
| Median rent as a share of median household income North Carolina 19.9% | 19.5% Georgia 20.9% | 20.9% | 19.9% |
| Renters spending half or more of income, 2024 North Carolina 24.9% | 26.6% Georgia 26.6% | 26.6% | 24.9% |
| Homes their owners live in, 2020 to 2024 North Carolina 66.6% | 71.9% Georgia 65.7% | 65.7% | 66.6% |
South Carolina’s rent is the lowest of the three, in dollars and as a share of income, yet its share of renters paying half their income matches Georgia’s. Sources: Census Bureau, American Community Survey (five-year figures for rent and owner-occupied homes; one-year figures for renters paying half their income). Rent as a share of income is our calculation: the 2020 to 2024 median rent times 12, divided by the 2024 median household income (Census Bureau).
More South Carolinians are behind on their bills than in most states
In early 2025, 22.1% of South Carolinians with a credit record had a debt 90 or more days late, tied for 6th highest among the 50 states and D.C., against 17.2% for the U.S. (Federal Reserve Bank of Philadelphia). We calculated the national figure as an average of the states weighted by population. This is household debt, owed by people, not by the state government.
Where South Carolina ranks among the 50 states and D.C. (1 = highest share): collections 6th, auto 6th, card 9th, mortgage tied for 6th. The U.S. figure averages the states, weighted by population (our calculation).
At the end of 2019, 30.6% of South Carolinians with a credit record had a debt in collections, against 18.3% in early 2025. Part of the fall since then comes from what credit reports show rather than from fewer people struggling. In 2022, the three big credit bureaus said they would stop reporting certain medical debts. Nationwide, the share of people with a medical collection on their credit record went from 14% in March 2022 to 5% in June 2023 (Consumer Financial Protection Bureau).
Can wages be garnished in South Carolina?
Not for most consumer debts. For a debt from a consumer credit sale, lease, loan or rent-to-own agreement, state law says “the creditor may not attach unpaid earnings of the debtor by garnishment or like proceedings” (S.C. Code § 37-5-104). So a court judgment on that kind of debt can’t take part of a paycheck. The law reaches only those consumer credit debts, not every debt a person can owe.
Counted in dollars, more of South Carolina’s loans are seriously late
The Federal Reserve Bank of New York measures the share of money owed, not of people, that is 90 or more days late. South Carolina is above the nation on cards, car loans and mortgages by that count too. At the end of 2025, 6.2% of auto loan balances were seriously late, tied for 8th highest among the 50 states and D.C. overall. South Carolinians don’t owe unusually much: $59,460 per person with a credit report, the 25th highest of the 50 states and D.C., against $63,200 nationwide.
| Loan type | South Carolina | U.S. | South Carolina 2019 | U.S. 2019 |
|---|---|---|---|---|
| Credit card | 13.4% End of 2025 U.S. 12.4% South Carolina 2019 8.2% · U.S. 2019 8.1% | 12.4% | 8.2% | 8.1% |
| Auto loan | 6.2% End of 2025 U.S. 5.2% South Carolina 2019 6.4% · U.S. 2019 4.9% | 5.2% | 6.4% | 4.9% |
| Mortgage | 1.2% End of 2025 U.S. 0.9% South Carolina 2019 1.2% · U.S. 2019 1.0% | 0.9% | 1.2% | 1.0% |
Share of balances 90 or more days past due, end of 2025 and end of 2019. Source: Federal Reserve Bank of New York, Consumer Credit Panel / Equifax. Because it counts dollars rather than people, it can’t be set beside the Philadelphia Fed figures above, and it includes old debts lenders have written off but still report.
Homeowners have less cushion than most
South Carolina mortgages with less than 10% equity made up 5.7% of the total in the second quarter of 2026, the 12th highest share of the 50 states and D.C., against 4.7% nationwide (Federal Housing Finance Agency). Equity is the part of a home’s value the owner doesn’t owe to a lender.
| Measure | South Carolina | U.S. | Rank |
|---|---|---|---|
| Mortgages 30 to 89 days late, Sept. 2025 Tied for 5th highest | 2.3% U.S. 1.6% | 1.6% | Tied for 5th highest |
| People with a credit score under 620, early 2025 6th highest | 18.2% U.S. 13.8% | 13.8% | 6th highest |
| Card users near their credit limit, early 2025 10th highest | 30.7% U.S. 26.9% | 26.9% | 10th highest |
Ranks are among the 50 states and D.C. Mortgages 30 to 89 days late, an early stage of falling behind: Consumer Financial Protection Bureau. Credit scores and card use: Federal Reserve Bank of Philadelphia; its U.S. figure averages the states, weighted by population (our calculation).
South Carolinians rarely file for bankruptcy, and most who do choose Chapter 13
South Carolinians filed 5,210 bankruptcy cases in 2025, up 12.0% from 2024 and the most since 2019, when they filed 6,833 (U.S. Courts). That works out to 95.1 filings for every 100,000 residents, using the 2024 population, the 13th lowest rate of the 50 states and D.C. and far below the U.S. rate of 167.1. Of the state’s filings, 64.6% were under Chapter 13, the 3rd highest share in the country, against 35.9% nationwide. In Chapter 13, a filer pays back part of the debts through a court-approved plan.
Next door, Georgia had 282.6 filings per 100,000 residents (2024 population), nearly three times South Carolina’s rate and the 5th highest of the 50 states and D.C. Most of its filings are Chapter 13 too (53.4%).
One possibility: because state law bars garnishing wages for consumer credit debts (see above), a collector’s court judgment can’t take part of a paycheck, so people may feel less pushed to file. The case against reading it that way: we haven’t compared filing rates across states with and without such a law. A study of U.S. bankruptcy filings from 2010 to 2014 found that filers’ disposable income explains most of the differences from place to place in which chapter people choose (Pattison and Millimet, IZA, 2023). And a high Chapter 13 share doesn’t go with few filings everywhere: Alabama has the highest filing rate in the country, 400.1 per 100,000, and 70.8% of its filings are Chapter 13.
| Year | Filings |
|---|---|
| 2018 | 6,598 |
| 2019 | 6,833 |
| 2020 | 4,707 |
| 2021 | 3,376 |
| 2022 | 3,619 |
| 2023 | 4,053 |
| 2024 | 4,651 |
| 2025 | 5,210 |
Bankruptcy cases of every chapter filed in the U.S. Bankruptcy Court for the District of South Carolina, by calendar year. Source: Administrative Office of the U.S. Courts, Table F-2.
What is South Carolina’s unemployment rate?
South Carolina’s unemployment rate was 4.1% in August 2026, the same as the U.S. rate and tied for 22nd highest among the 50 states and D.C., down from 4.6% a year earlier (Bureau of Labor Statistics). Over whole years the state ran below the nation from 2017 to 2023, then rose above it in 2024 and 2025. Its 2025 average, 4.5%, was its highest since 2020.
Unemployment rate
4.1%
U.S. 4.1%
Tied for 22nd highest among the 50 states and D.C. (August 2026)
Unemployment rate, 2025 average
4.5%
U.S. 4.3%
Highest yearly average since 2020
Workers named in layoff notices
4,489
Jan. 1 to Aug. 28, 2026, SC Department of Employment and Workforce
South Carolina’s unemployment rate ran at or below the nation’s from 2017 to 2023; by August 2026 the two were level
Unemployment rate, South Carolina and the United States, seasonally adjusted, each month from January 1990 to August 2026. October 2025 is missing: no figures were published during the federal shutdown.
Layoff notices in 2026
From Jan. 1 to Aug. 28, 2026, employers filed 35 notices with the state for layoffs and closures, naming 4,489 workers. The largest came from Electrolux, which is laying off 1,245 workers at its Anderson plant between July 18 and Dec. 18 (SC Department of Employment and Workforce). A notice counts workers at one workplace before the layoff happens, so it isn’t a count of jobs already lost.
Unemployment benefits are claimed through the SC Department of Employment and Workforce.
Unemployment is highest in Williamsburg and Marlboro
| County | Rate |
|---|---|
| Williamsburg | 7.1% |
| Marlboro | 7.0% |
| Allendale | 6.5% |
| Marion | 6.5% |
| Lee | 6.3% |
| Union | 6.3% |
| Richland | 4.5% |
| Spartanburg | 4.3% |
| Greenville | 3.7% |
| Charleston | 3.5% |
Unemployment rate in selected counties, August 2026, not adjusted for seasonal swings. Williamsburg County’s rate was tied for 49th highest among the 3,143 U.S. counties with a rate. Charleston had the lowest in South Carolina. Source: Bureau of Labor Statistics.
What changed in South Carolina in the past year
-
Aug. 27, 2026
Limits on what SNAP can buy are pushed back to November
The state planned to start Healthy Food SC on Aug. 31, a two-year project that stops SNAP food benefits from paying for candy, energy drinks, soft drinks and sweetened drinks; diet and zero-sugar sodas stay allowed, and households can’t opt out (announced Aug. 17). The U.S. Department of Agriculture, which approved the project at Gov. Henry McMaster’s request, then asked the state to wait until Nov. 1, 2026.
-
Aug. 1, 2026
A second Duke Energy Carolinas rate increase is due in the Upstate
Under the second step of a rate increase the Public Service Commission approved in 2024, Duke Energy Carolinas’ home rates were set to rise another 4.3% from Aug. 1, 2026, about $6.42 a month for a home using 1,000 kilowatt-hours.
-
July 28, 2026
Fewer South Carolinians pay for marketplace health plans
The extra federal help with marketplace premiums ended after 2025. In KFF’s analysis of federal enrollment figures, the number of South Carolinians who picked a 2026 marketplace plan fell 7%, but the number who paid for one, which is what puts coverage in force, fell 29%.
-
July 15, 2026
Regulators turn down a Duke Energy Progress increase, and Duke appeals
The Public Service Commission ruled that Duke Energy Progress, which serves the Pee Dee, could not raise rates under the state’s new rate stabilization program until a year after it applied. Duke appealed to the South Carolina Supreme Court in late July, and the state Department of Consumer Affairs asked the court to dismiss the appeal.
-
July 2026
New Dominion Energy rates take effect
Dominion Energy South Carolina asked in January for an increase that would have added about $19.98 a month to the bill of a home using 1,000 kilowatt-hours, according to the state Office of Regulatory Staff. In May the company signed settlement agreements for a smaller increase (Dominion), and new home rates took effect with the first July bills under Public Service Commission Order No. 2026-374 (Dominion’s rate schedule).
-
May 15, 2026
Electrolux files the year’s largest layoff notice
Electrolux Consumer Products told the state it would lay off 1,245 workers in Anderson between July 18 and Dec. 18, 2026. From Jan. 1 to Aug. 28, employers filed 35 layoff and closure notices covering 4,489 workers (see jobs).
SC Department of Employment and Workforce, layoff notices through Aug. 28, 2026
-
March 30, 2026
A new state income tax law is signed
Gov. McMaster signed H. 4216. Starting with the 2026 tax year, income is taxed at 1.99% up to $30,000 and 5.21% above that. A new state deduction of up to $15,000 for single filers and $30,000 for married couples filing jointly replaces the federal standard deduction and can shrink as income rises, and the state earned income tax credit is capped at $200. The first returns under the law are due April 15, 2027.
-
Feb. 2, 2026
Federal SNAP work rules reach more adults
Under the 2025 federal law known as the One Big Beautiful Bill Act, adults 18 to 64 without dependents must work or join a work program 80 hours a month to keep SNAP beyond three months in any three years. The upper age had been 54. Exemptions for veterans, people who are homeless and young adults who aged out of foster care ended, and parents of children 14 to 17 are no longer exempt.
How foreclosure works in South Carolina
Every foreclosure on a home mortgage in South Carolina goes through a court. The lender files a lawsuit, the homeowner has 30 days after being served to answer. The case is ordinarily sent to a master-in-equity, a judge who hears it and holds the sale (Rule 71, South Carolina Rules of Civil Procedure). The sale must be advertised for the three weeks before sale day (S.C. Code § 15-39-650). Federal rules generally bar the first filing until a home loan is more than 120 days behind. No law sets how long the case takes, and the homeowner can’t buy the home back after the sale. If the lender is seeking a judgment for any balance the sale leaves unpaid, bidding stays open for 30 days after sale day.
- Goes through a court
- Always
- Time to answer the lawsuit
- 30 days
- Sale advertised
- 3 weeks
- Who holds the sale
- Master-in-equity
- Buying the home back after the sale
- Not allowed
- Lender can seek the balance left after the sale
- Yes, with limits
- Statewide foreclosure mediation
- No
What the law says. Sources: S.C. Code §§ 15-39-650 and 29-3-610 to 29-3-740; South Carolina Rules of Civil Procedure 12(a) and 71; federal rule 12 CFR 1024.41. How foreclosure works in South Carolina →
South Carolina received a $144.7 million award from the federal Homeowner Assistance Fund and had assisted 14,873 homeowners (U.S. Treasury, through early 2026; Treasury’s count includes housing counseling).
South Carolina’s most common mortgage complaint is trouble during the payment process
Since 2012, South Carolinians have filed 6,215 mortgage complaints with the Consumer Financial Protection Bureau. The issues named most often were trouble during the payment process (1,893), then loan modifications, collection and foreclosure (1,156), then loan servicing, payments or escrow (941).
- Oct. 7, 2026 Vanderbilt Mortgage Struggling to pay mortgage: Applying for or obtaining a modification, forbearance plan, short sale, or deed-in-lieu In progress
- Oct. 6, 2026 Figure Technologies, Inc Struggling to pay mortgage: Trying to communicate with the company to fix an issue related to modification, forbearance, short sale, deed-in-lieu, bankruptcy, or foreclosure Closed with explanation
- Oct. 4, 2026 Shellpoint / NewRez Trouble during payment process: Fees charged In progress
- Sept. 30, 2026 Ocwen / Onity Group Struggling to pay mortgage: Applying for or obtaining a modification, forbearance plan, short sale, or deed-in-lieu In progress
- Sept. 30, 2026 Ocwen / Onity Group Trouble during payment process: Trying to communicate with the company to fix an issue while managing or servicing your loan In progress
- Sept. 29, 2026 Shellpoint / NewRez Trouble during payment process: Payment process In progress
- Sept. 29, 2026 SN Servicing Struggling to pay mortgage: Trying to communicate with the company to fix an issue related to modification, forbearance, short sale, deed-in-lieu, bankruptcy, or foreclosure Closed with explanation
- Sept. 28, 2026 Carrington Mortgage Struggling to pay mortgage: Foreclosure In progress
- Sept. 28, 2026 Toll Brothers Inc Trouble during payment process: Escrow, taxes, or insurance Closed with explanation
- Sept. 28, 2026 Fifth Third Bank Struggling to pay mortgage: Foreclosure In progress
The ten latest South Carolina complaints about paying a mortgage or getting help with one, newest first, from the Consumer Financial Protection Bureau’s public complaint record as of Oct. 14, 2026. Complaints about getting a new loan are left out, and so are complaints naming a credit reporting company. The bureau doesn’t check what each person tells it. See every South Carolina mortgage complaint at the Consumer Financial Protection Bureau →
What to watch before the next edition
Dates that reach household budgets between now and spring 2027, nearest first.
-
Nov. 1, 2026
Healthy Food SC is set to start
If it starts on the date the U.S. Department of Agriculture asked for, SNAP benefits in South Carolina would no longer pay for candy, energy drinks, soft drinks or sweetened drinks.
-
Dec. 18, 2026
The last layoffs in Electrolux’s Anderson notice
Electrolux’s notice covers the layoff of 1,245 workers at its Anderson plant between July 18 and this date.
SC Department of Employment and Workforce, layoff notices through Aug. 28, 2026
-
Feb. 15, 2027
A decision on another income tax cut
The state Board of Economic Advisors must decide by this date each year whether the top income tax rate falls again. Under H. 4216 it does when the board projects revenue rising 5% or more from the year before.
-
April 15, 2027
The first tax returns under the new rates are due
Returns for the 2026 tax year use the new rates, the new state deduction and the capped earned income tax credit.
Where South Carolina ranks highest and lowest
| Measure | South Carolina | U.S. | Rank | Latest data |
|---|---|---|---|---|
| Population growth since 2020 Tied for 3rd highest · 2025 | 8.5% U.S. 3.1% | 3.1% | Tied for 3rd highest | 2025 |
| People with a debt in collections 6th highest · Early 2025 | 18.3% U.S. 13.2% | 13.2% | 6th highest | Early 2025 |
| Auto loan borrowers 90+ days late 6th highest · Early 2025 | 11.5% U.S. 8.5% | 8.5% | 6th highest | Early 2025 |
| People with a debt 90+ days late Tied for 6th highest · Early 2025 | 22.1% U.S. 17.2% | 17.2% | Tied for 6th highest | Early 2025 |
| People with a credit score under 620 6th highest · Early 2025 | 18.2% U.S. 13.8% | 13.8% | 6th highest | Early 2025 |
| Mortgages 30 to 89 days late Tied for 5th highest · Sept. 2025 | 2.3% U.S. 1.6% | 1.6% | Tied for 5th highest | Sept. 2025 |
| Share of income from government benefits 7th highest · 2024 | 23.4% U.S. 18.3% | 18.3% | 7th highest | 2024 |
| Renters spending half or more of income on housing Tied for 9th highest · 2024 | 26.6% U.S. 26.1% | 26.1% | Tied for 9th highest | 2024 |
| Homes their owners live in 9th highest · 2024* | 71.9% U.S. 65.2% | 65.2% | 9th highest | 2024* |
| Children in poverty 11th highest · 2024 | 18.1% U.S. 15.5% | 15.5% | 11th highest | 2024 |
| Residents in poverty Tied for 13th highest · 2024 | 13.3% U.S. 12.1% | 12.1% | Tied for 13th highest | 2024 |
| Unemployment rate, three-month average Tied for 22nd highest · June–August 2026 | 4.2% U.S. 4.1% | 4.1% | Tied for 22nd highest | June–August 2026 |
| Median household income 14th lowest · 2024 | $72,507 U.S. $81,604 | $81,604 | 14th lowest | 2024 |
| Income per person 7th lowest · 2024 | $60,776 U.S. $73,204 | $73,204 | 7th lowest | 2024 |
| Bankruptcy filings per 100,000 residents (2024 population) 13th lowest · 2025 | 95.1 U.S. 167.1 | 167.1 | 13th lowest | 2025 |
Ranks count among the 50 states and D.C., from the top for “highest” and from the bottom for “lowest.” * Census five-year survey, 2020 to 2024. Population growth: Census Bureau estimates, 2020 to 2025; the U.S. figure is our sum of the 50 states and D.C. combined. Debts and credit scores: Federal Reserve Bank of Philadelphia, counting people with a credit record; its U.S. figure averages the states, weighted by population (our calculation). Each measure’s source is listed in Sources and method. Download this table: CSV.
Questions about South Carolina
Is South Carolina a poor state?
Poorer than most on income, and above the U.S. on poverty but not among the 10 highest states. In 2024, 13.3% of South Carolinians lived in poverty, tied for 13th highest among the 50 states and D.C., and the typical household earned $72,507, the 14th lowest (U.S. Census Bureau, Small Area Income and Poverty Estimates). Income per person, $60,776, was the 7th lowest (U.S. Bureau of Economic Analysis, 2024).
Which county is the poorest in South Carolina?
Allendale County, on the Savannah River. In 2024, 31.6% of its residents lived in poverty and its typical household earned $41,336, the highest poverty rate and the lowest income of South Carolina’s 46 counties (U.S. Census Bureau, Small Area Income and Poverty Estimates). On our County Distress Index, Williamsburg County is the most distressed.
Can wages be garnished in South Carolina?
Not for most consumer debts. State law bars a creditor from garnishing wages for a debt from a consumer credit sale, lease, loan or rent-to-own agreement (S.C. Code § 37-5-104). The ban covers only those debts. We don’t give legal advice; free legal help is listed under Free help in South Carolina.
Is South Carolina an expensive place to live?
Rent is below the middle of the states: the median was $1,180 a month, the 22nd lowest of the 50 states and D.C. (U.S. Census Bureau, 2020 to 2024). But in 2024, 26.6% of South Carolina renters paid half or more of their income for housing, slightly more than renters nationwide. We don’t measure food prices, home prices, insurance or utility bills, so we don’t rank the overall cost of living.
What is South Carolina’s poverty line?
Under the 2026 federal poverty guideline it’s $15,960 a year for one person and $33,000 for a family of four. South Carolina uses the same figures as every state except Alaska and Hawaii (U.S. Department of Health and Human Services).
Does foreclosure in South Carolina go through a court?
Yes, always. A lender has to sue, and the case is ordinarily heard by a master-in-equity, who also holds the sale. After the sale there’s no right to buy the home back. How foreclosure works in South Carolina →
Cite or reuse South Carolina’s data
Free to quote in news stories, grant applications and policy memos, with credit.
State Distress Index
South Carolina
9thmost distressed state
of the 50 states and D.C.
More distressed than 84% of the other states and D.C.
On the State Distress Index, South Carolina ranks 9th among the 50 states and D.C.; the index is the measure of household financial distress that American Default Research publishes. In early 2025, 18.3% of South Carolinians with a credit record had a debt in collections, the 6th highest share of the 50 states and D.C. (Federal Reserve Bank of Philadelphia). Yet the state had 95.1 bankruptcy filings per 100,000 residents in 2025, measured against its 2024 population, the 13th lowest rate of the 50 states and D.C. (U.S. Courts). Its poverty rate, 13.3% in 2024, was tied for 13th highest (U.S. Census Bureau, Small Area Income and Poverty Estimates).
Reporters and researchers can ask for interviews or a custom cut of the data at press@americandefault.org
Sources and method
We gather the data, run the numbers and research each state ourselves.
This edition: October 2026 · Next edition expected March 2027
- Late payments, collections, credit scores and card useFederal Reserve Bank of Philadelphia, Consumer Credit Explorerend of 2019 and early 2025
- Household debt and dollars behindFederal Reserve Bank of New York, Consumer Credit Panel / Equifaxend of 2019 and end of 2025
- Mortgages with little equityFederal Housing Finance Agency, National Mortgage Databasesecond quarter of 2026
- Mortgages 30 to 89 days late; mortgage complaints; medical debts on credit reportsConsumer Financial Protection Bureau: Mortgage Performance Trends; complaint database; Recent changes in medical collections on consumer credit recordsSept. 2025; Oct. 14, 2026; March 2022 to June 2023
- Bankruptcy filingsU.S. Courts, Table F-22018 to 2025
- Why bankruptcy chapters differ from place to placeNathaniel Pattison and Daniel L. Millimet, A Tale of Two Bankruptcies, IZA Discussion Paper 16105May 2023
- Unemployment, state, county and nationalU.S. Bureau of Labor Statistics, Local Area Unemployment StatisticsJan. 1990 to Aug. 2026
- Layoff noticesSC Department of Employment and WorkforceJan. 1 to Aug. 28, 2026
- Poverty and incomeCensus Bureau, Small Area Income and Poverty Estimates1989 to 2024
- Renters spending half or more of income on housingCensus Bureau, American Community Survey 1-year2005 to 2024
- Rent, homeownership, age, disability, health insurance, schoolingCensus Bureau, American Community Survey 5-year2020 to 2024
- PopulationCensus Bureau, population estimates and decennial census counts1920; 2020 to 2025
- Income per person and its sourcesU.S. Bureau of Economic Analysis2024
- SNAPU.S. Department of Agriculture Food and Nutrition AdministrationJune 2025 to June 2026
- Cost of getting byMIT Living Wage Calculator2025 dollars
- Mortgage help fundU.S. Treasury, Homeowner Assistance Fundthrough early 2026
- Wage garnishment and foreclosure lawSouth Carolina Code of Laws, Title 37, Chapter 5, Title 29, Chapter 3 and Title 15, Chapter 39; South Carolina Rules of Civil Procedure, Rule 71; 12 CFR 1024.41as of 2026
- Poverty guidelineU.S. Department of Health and Human Services2026
- Housing counselorsU.S. Department of Housing and Urban DevelopmentOctober 2026
- What changed and what to watchSouth Carolina Department of Social Services, South Carolina Department of Revenue, South Carolina Office of Regulatory Staff, Dominion Energy South Carolina, Duke Energy, SC Daily Gazette, KFF, SC Department of Employment and Workforce; every item above links to the page we read it on (see what changed)Jan. 2026 to April 2027
- County photo and courthouse historyJudson McCranie (Bubba73), via Wikimedia Commons; South Carolina Encyclopedia2017
The score has four equal parts: late payments; collections and bankruptcy; jobs; and renters’ housing costs. Each measure is ranked against the 50 states and D.C., and the score is the share of the other 50 places whose four-part average is lower than South Carolina’s. The full method →
We write with AI tools, and Ross Kilburn checks and reviews every page before it's published.
Get the next South Carolina edition by email
One email each time a new South Carolina edition is out; the next is expected in March 2027. Unsubscribe anytime.
Thanks, that helps.