Florida had the nation’s highest share of renters paying half or more of their income for housing: 32.1%
Each state is shaded by how distressed its households are, from green (least) to red (most), with data through September 2026. Florida scores 96 out of 100.
Florida had the nation’s highest share of severely burdened renters in 2024: 32.1% spent half or more of their income on housing. Its unemployment rate has risen above the U.S. rate, though its poverty rate matches the nation’s. Gadsden and Hamilton counties are among the nation’s 50 most distressed counties; St. Johns County is Florida’s least distressed.
- Score
- 96/100
- Data through
- September 2026
- Edition
- October 2026
Next edition expected March 2027
How Florida ranks among the states
Florida’s poverty rate matches the nation’s, 12.1% in 2024, yet Florida is the 3rd most distressed of the 50 states and D.C., behind only Nevada and Louisiana. No other state has a larger share of renters paying half or more of their income in rent, and rising unemployment has pushed its score up since early 2025. The poverty rate doesn’t capture rent: the official poverty line is the same across the country, so it doesn’t reflect what housing costs in Florida (Census Bureau).
What drives the score
The index averages four parts, each scored 0 to 100 against the other states.
- Renters’ housing costs9932.1% of renters pay half or more of their income in rent, the highest share of any state (2024)
- Late payments7815.8% of card borrowers and 1.5% of mortgage borrowers are 90 or more days behind (early 2025)
- Jobs754.6% unemployment, June to August 2026, up from 3.5% at the end of 2024
- Collections and bankruptcy7014.5% of people have a debt in collections; bankruptcy filings rose by a fifth in 2025
Beside its neighbors
More distressed than both of its neighbors, Georgia and Alabama.
State Distress Index score, 0 to 100. Georgia and Alabama score higher than Florida on late payments and on collections and bankruptcy; Florida scores higher on renters’ costs and jobs.
How its rank has changed
At its worst
Most distressed state, every quarter from 2009 through 2011
By early 2025
9th most distressed, climbing from 15th at the end of 2022
Why it climbed to 3rd
Unemployment rose: the jobs part of the score went from 36 to 75
Florida was the most distressed state through the foreclosure crisis and has stayed among the 15 most distressed since
State Distress Index score, 0 to 100, each quarter, third quarter of 2006 to first quarter of 2025.
The poorest and most distressed counties in Florida
Hamilton County, on the Georgia line, is the poorest county in Florida: 25.3% of its residents lived in poverty in 2024, and its typical household earned $48,859, the least in the state (Census Bureau, Small Area Income and Poverty Estimates). Sites that use the Census Bureau’s other survey, the American Community Survey, averaged over five years, name Gadsden instead. The richest county is St. Johns, around St. Augustine, where the typical household earned $117,178, followed by Collier ($97,022) and Monroe ($94,752). On our County Distress Index, Gadsden County, west of Tallahassee, is the most distressed, and St. Johns is the least.
Florida’s most distressed counties stretch across the north and down the middle of the peninsula
County Distress Index score, 0 to 100, for Florida’s 67 counties, data through August 2026.
Loading the county map…
The county map could not be loaded. Every county is in the lists on this page.
Most distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 1 | Gadsden | 99 | 20.7% |
| 2 | Hamilton | 98 | 25.3% |
| 3 | Putnam | 95 | 20.7% |
| 4 | Highlands | 94 | 15.5% |
| 5 | DeSoto | 93 | 21.8% |
| 6 | Hendry | 92 | 18.3% |
| 7 | Madison | 92 | 19.6% |
| 8 | Dixie | 91 | 22.1% |
| 9 | Polk | 91 | 13.4% |
| 10 | Hardee | 91 | 18.9% |
Least distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 63 | Martin | 45 | 8.6% |
| 64 | Santa Rosa | 44 | 10.3% |
| 65 | Wakulla | 43 | 11.8% |
| 66 | Sumter | 42 | 8.8% |
| 67 | St. Johns | 21 | 5.8% |
Rank in Florida, 1 = most distressed; ranks use unrounded scores, so two counties showing the same score can rank differently. Poverty: share of residents in poverty, Census Bureau, 2024.
Every county, by score
Most of Florida’s 67 counties score 70 or higher: 29 score 80 or more, and only St. Johns scores below 30.
29 score 80–100
Gadsden, Hamilton, Putnam, Highlands, DeSoto, Hendry, Madison, Dixie, Polk, Hardee, Lafayette, Calhoun, Marion, Osceola, Escambia, Jackson, Citrus, Levy, Okeechobee, Taylor, Columbia, Glades, Suwannee, Hernando, Duval, Holmes, Bradford, St. Lucie, Volusia
15 score 70–79
Union, Orange, Franklin, Leon, Liberty, Pasco, Gilchrist, Jefferson, Gulf, Hillsborough, Broward, Washington, Lake, Lee, Miami-Dade
14 score 50–69
Flagler, Brevard, Alachua, Charlotte, Bay, Pinellas, Clay, Palm Beach, Baker, Manatee, Indian River, Seminole, Okaloosa, Walton
1 score 0–29
Poorest isn’t the same as most distressed
Our county score has five equal parts: late payments; collections and bankruptcy; jobs; housing costs; and a fifth built from poverty, income, health insurance and disability. So a county can be poor without ranking near the top. Polk and Highlands counties show it: their poverty rates sit near the middle of the state, yet they rank 9th and 4th most distressed. It works the other way for Alachua and Leon counties, home to the University of Florida and Florida State University: both are among the five poorest but sit in the middle on distress (table below). College students living off campus count in poverty figures, and leaving them out lowers both counties’ poverty rates markedly (U.S. Census Bureau, 2012 to 2016 data).
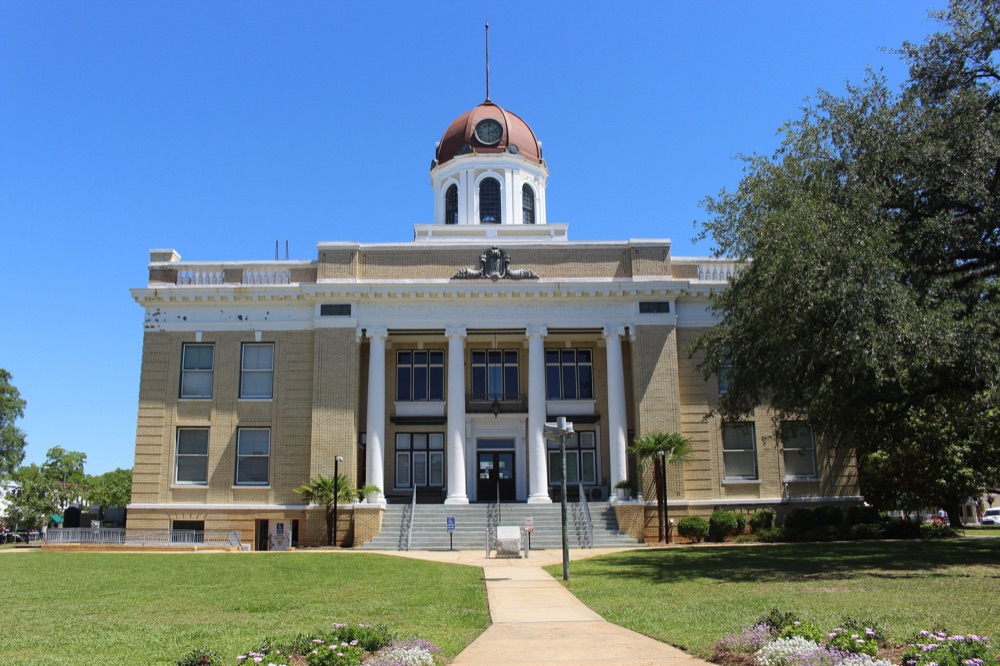
The Gadsden County Courthouse in Quincy. Gadsden is the most distressed of Florida’s 67 counties on our index and the 8th most distressed of 3,144 U.S. counties; 20.7% of its residents lived in poverty in 2024 (Census Bureau).
Sources: American Default Research, County Distress Index; U.S. Census Bureau. Photo: Michael Rivera, Wikimedia Commons, CC BY-SA 4.0.

Counties that lost people before 2020 are Florida’s most distressed
Florida grew 8.7% from 2020 to 2025, the 2nd fastest of any state, yet 17 of its 67 counties had fewer people in 2020 than at some earlier census. Of those 17, 14 score 80 or more on our index, including six of the ten most distressed: Gadsden, Hamilton, Putnam, DeSoto, Madison and Hardee. The 17 together hold 2% of Floridians.
Census Bureau, decennial census and annual estimates; American Default Research.
Renters are squeezed hardest outside the most distressed counties
The share of renters paying half or more of their income for housing is highest in Alachua, Martin, Osceola, Miami-Dade, Broward, Collier, Palm Beach and Monroe counties, most of them in the middle of our index or below it. Across Florida’s counties, a high distress score goes with low incomes, unpaid debts sent to collectors and late card payments far more than with renters’ costs.
Census Bureau, American Community Survey, 2020 to 2024; our comparison across the 67 counties.
One in five Floridians lives in a county scoring 80 or more
About 5.1 million people, 22.6% of Floridians, live in the 29 counties scoring 80 or more, including Duval (Jacksonville) and Polk (Lakeland). The biggest counties sit in the middle: Orange is the 31st most distressed of 67, Hillsborough 39th, Broward 40th, Miami-Dade 44th and Palm Beach 52nd.
American Default Research, County Distress Index; Census Bureau population estimates.
Is Florida expensive to live in?
For renters, yes: more of them are stretched by rent than in any other state. In 2024, 32.1% of Florida renter households spent half or more of their income on rent and utilities, the highest share of any state, against 26.1% nationwide (Census Bureau). Day-to-day costs sit closer to the middle: MIT’s estimate of what a single adult needs to get by ranks 24th of the 50 states and D.C. overall. Homeowners face a different squeeze: Florida was the only state where home prices fell in 2025, and only one state has a larger share of mortgages where the owner owes nearly as much as the home is worth. We don’t measure the prices of food, gas or insurance.
Renters paying half or more of income on housing
32.1%
U.S. 26.1%
Highest of the 50 states and D.C., 2024
Change in home prices
−0.5%
U.S. +2.9%
The only state where prices fell, 2025
Mortgages with less than 10% equity
7.8%
U.S. 4.7%
2nd highest, mid-2026
Florida has led the states on renters paying half or more of their income for housing three years running
Share of renter households spending half or more of their income on rent and utilities, Florida and the United States, 2005 to 2024. The Census Bureau published no 2020 figure.
Other housing costs
| Measure | Fla. | U.S. | Rank |
|---|---|---|---|
| Median rent, a month 9th highest | $1,669 U.S. $1,413 | $1,413 | 9th highest |
| Homeowners spending 30%+ of income on housing 5th highest | 27.2% U.S. 22.5% | 22.5% | 5th highest |
| Mortgages larger than the home’s value Highest | 0.8% U.S. 0.3% | 0.3% | Highest |
| Share of income spent on home energy 43rd highest | 2.1% U.S. 2.4% | 2.4% | 43rd highest |
| Basic costs for a single adult, a year (MIT) 24th highest | $50,117 | 24th highest |
Ranks among the 50 states and D.C., highest first. Rent and homeowners: Census Bureau, American Community Survey, 2020 to 2024. Mortgages: Federal Housing Finance Agency, mid-2026. Energy: U.S. Department of Energy, 2022, state figure our calculation. Basic costs: MIT Living Wage Calculator, single adult with no children.
Why is home insurance so expensive in Florida?
Storms and failing insurers. Six hurricanes brought federal major-disaster declarations from 2022 to 2024: Ian, Nicole, Idalia, Debby, Helene and Milton (Federal Emergency Management Agency). At least 10 Florida property insurers went insolvent from early 2021. A state report listed causes including storm losses, rates too low to cover claims and the cost of reinsurance, the coverage insurers buy for themselves (Insurance Journal, July 2023). We don’t track insurance prices; Florida’s insurance regulator does. Its July 2026 report found that average homeowners premiums fell in 51 of the state’s 67 counties in the first half of 2026 (Florida Office of Insurance Regulation, as reported by WPTV). WWSB put the statewide average premium at $3,757 (Aug. 31, 2026).
Condo owners face new repair bills
After the Surfside condo collapse in June 2021, which killed 98 people, Florida required condo buildings to be inspected and to save in full for major repairs. Some special assessments, one-time charges to owners, now top $100,000 a unit, a particular strain for some older owners on fixed incomes (Federal Reserve Bank of Atlanta, October 2026).
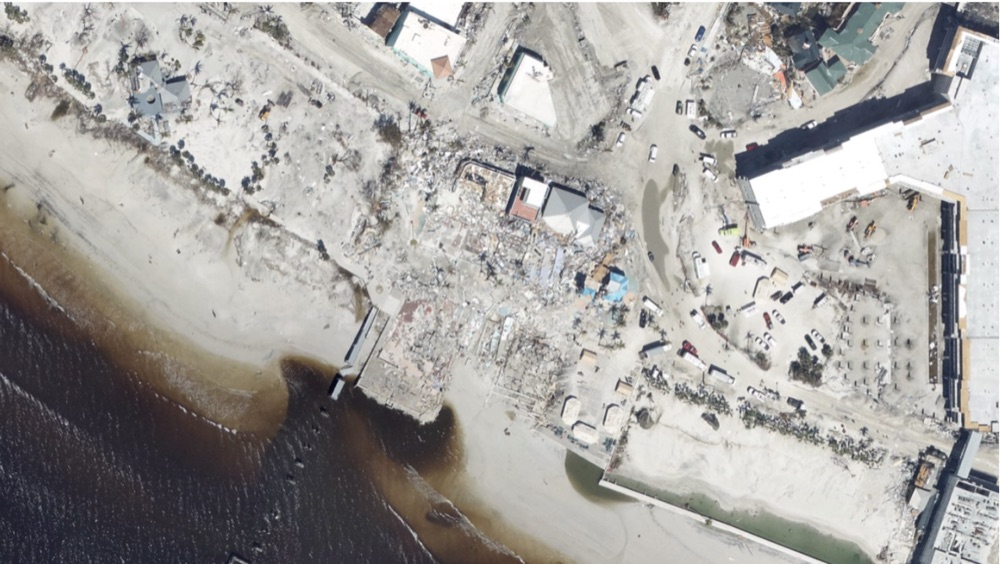
Fort Myers Beach after Hurricane Ian, which came ashore in Lee County in September 2022. FEMA declared a major disaster for Ian on Sept. 29, 2022.
Source: FEMA. Photo: National Oceanic and Atmospheric Administration (NOAA), public domain.

How is Florida’s economy doing?
Florida is still adding jobs and people, but more Floridians are out of work. The unemployment rate rose from 3.5% at the end of 2024 to 4.8% in April and May 2026, and averaged 4.6% from June to August 2026, above the U.S. rate of 4.1% (Bureau of Labor Statistics).
Unemployment rate
4.6%
U.S. 4.1%
13th highest, June to August 2026
Jobs
10,051,600
0.6% more than a year earlier
August 2026, preliminary
Population growth since 2020
8.7%
2nd fastest of any state
2020 to 2025
Florida’s unemployment rate rose above the nation’s in January 2026, for the first time since 2020
Unemployment rate, Florida and the United States, each month, January 2022 to August 2026. No figures for October 2025, during the federal shutdown.
Are people leaving Florida?
No. More people still move in than leave, but the gap has nearly closed. Florida had 23,462,518 people in 2025, the 3rd most of any state, and grew 0.8% from 2024, the 13th fastest (Census Bureau). About 22,000 more people moved to Florida from other states than left in 2025, against about 208,000 a year from 2020 to 2022, and deaths have outnumbered births every year since 2020 (The Conversation, via WUSF, July 2026). Miami-Dade County lost nearly 73,000 residents, net, to moves within the U.S. in 2025 (University of Florida, July 2026).
Where the jobs are, and aren’t
In the year to August 2026, education and health care jobs grew 2.5%, while finance jobs fell 2.1% and information jobs, such as publishing, broadcasting and telecom, fell 2.6% (Bureau of Labor Statistics, preliminary). Unemployment differs widely by county:
| County | Rate |
|---|---|
| Taylor | 8.2% |
| Sumter | 7.9% |
| Highlands | 6.8% |
| Miami-Dade | 2.7% |
Unemployment rate, August 2026, the three highest of Florida’s 67 counties and the lowest; not adjusted for seasonal swings. Source: Bureau of Labor Statistics.
Is Florida a poor state?
No. In 2024, 12.1% of Floridians lived in poverty, the same share as the nation, and the typical household earned $77,687 a year, a little below the U.S. figure of $81,604 (Census Bureau). Florida’s strain shows up in housing costs and late payments, not in its poverty rate.
Residents in poverty
12.1%
U.S. 12.1%
Tied for 19th highest, 2024
Median household income
$77,687
U.S. $81,604
27th highest of the 50 states and D.C., 2024
Children in poverty
15.7%
U.S. 15.5%
19th highest, 2024
Florida’s poverty rate ran above the nation’s from 2008 to 2022 and now matches it
Share of residents in poverty, Florida (dark line) and the United States, 1989 to 2024
Why is Florida so distressed if it isn’t poor?
Three facts help explain the gap.
The poverty line doesn’t move with rent. The official poverty line is the same across the country, so it doesn’t reflect what housing costs in Florida (Census Bureau). More of Florida’s renters pay half or more of their income for housing than in any other state (see Is Florida expensive to live in?).
More income comes from investments, less from paychecks. Dividends, interest and rent make up 30.2% of all the income Floridians get, the 2nd highest share of any state, against 21.0% nationwide; wages make up 43.1%, the 7th lowest share, against 49.7% nationwide (Bureau of Economic Analysis, 2024).
An older state. Residents 65 or older make up 21.3% of Florida, the 3rd highest share, against 17.2% nationwide (Census Bureau, 2020 to 2024).
Our reading: the state’s averages include many retirees living on savings and investments, while working-age households carry more of the squeeze from rent and debt.
Food help fell by a fifth in a year, even as unemployment rose
About one in ten Floridians get food help through SNAP, close to the national share. The number fell by about a fifth in a year, and in May 2026 it was the lowest since 2009. Need didn’t fall with it: more Florida households had trouble affording food in 2022 to 2024 than in 2019 to 2021 (U.S. Department of Agriculture). The drop came the same year as stricter federal work rules (see what changed in Florida in the past year). Florida hasn’t expanded Medicaid to more low-income adults (KFF, a health policy research group).
“Particularly here in Florida, we often see people who are wrongly subject to the requirements and improperly sanctioned.”
| Measure | Fla. | U.S. | Rank |
|---|---|---|---|
| Residents getting SNAP, June 2026 25th highest | 10.1% U.S. 10.7% | 10.7% | 25th highest |
| People getting SNAP, June 2026 | 2,358,796 | ||
| People getting SNAP, May 2026, the fewest since 2009 | 2,290,760 | ||
| People getting SNAP, June 2025 | 2,928,850 | ||
| Change, June 2025 to June 2026 5th largest drop | −19.5% | 5th largest drop | |
| Households short of food, 2022 to 2024 Tied for 17th highest | 13.3% | Tied for 17th highest | |
| Residents without health insurance, 2020 to 2024 4th highest | 11.5% U.S. 8.4% | 8.4% | 4th highest |
Ranks among the 50 states and D.C. (1 = highest). SNAP: USDA Food and Nutrition Administration. Households short of food: USDA Economic Research Service; 3.4 points higher than in 2019 to 2021. Health insurance: Census Bureau. To apply for either program: Florida Department of Children and Families →
What changed in Florida in the past year
-
Coming: Nov. 3, 2026
A vote on property taxes
Florida voters will decide Amendment 3, which the Legislature put on the ballot in June. It needs 60% to pass. It would raise the homestead exemption for non-school property taxes, the part of a home’s value those taxes don’t reach, from $50,000 to $150,000 on Jan. 1, 2027, and to $250,000 a year later, rising with inflation after that. People who move to Florida from 2027 would start at $50,000 and get the larger amount after four years with a homestead exemption. For other property, the limit on how much its taxed value can rise each year would fall from 10% to 5%. School taxes wouldn’t change.
-
Sept. 30, 2026
Minimum wage reaches $15
Florida’s minimum wage rose to $15.00 an hour, and to $11.98 for tipped workers, the last of the yearly $1 steps set by an amendment to the state constitution. About 1.29 million Floridians earned less than $15 before the change, the Florida Policy Institute, a research group, estimated. From 2028, the wage is set to rise with inflation.
Florida Phoenix, via Florida Trend; Lowndes law firm
-
July 1, 2026
Home insurance: the state insurer cuts rates
Citizens Property Insurance, the state-created insurer for homeowners who can’t get private coverage, began cutting rates for new policies and at renewal: an average 8.8% for homeowners policies and 5.5% for wind-only policies, and at least 2% for every personal policy. Regulators approved the cuts in March, when Citizens had 336,000 policies, down 76% from 1.41 million in October 2023, as private insurers took policies back.
-
Apr. 20, 2026
Food assistance rules
In Florida, SNAP food benefits (once called food stamps) can no longer buy soda, energy drinks, candy or prepared desserts, under a federal pilot that runs to April 2028. Earlier, the budget law Congress passed in July 2025 extended SNAP work rules to adults aged 55 to 64 and to parents of children 14 and older, and ended exemptions for veterans, people without homes and young people leaving foster care. Fewer Floridians now get SNAP (see Is Florida a poor state?).
-
Jan. 1, 2026
Health insurance
Larger federal tax credits for health plans bought through HealthCare.gov expired after Congress didn’t extend them. About 4.5 million Floridians signed up for 2026 plans, more than 260,000 fewer than a year earlier (down 5.5%), the largest drop in number of any state.
Centers for Medicare and Medicaid Services, via WUSF
-
Jan. 1, 2026
Electric bills
Florida Power & Light’s bill for a typical home using 1,000 kilowatt-hours a month rose $2.50, from $134.14 to $136.64, under a four-year rate agreement the Public Service Commission approved on Nov. 20, 2025.
How many Floridians are behind on their bills?
More than in most states. In early 2025, 15.8% of Floridians with a credit card had one 90 or more days late, against 13.5% nationwide, and 14.5% of Floridians had a debt in collections, against 13.2% (Federal Reserve Bank of Philadelphia). Measured in dollars, a larger share of Floridians’ card balances is 90 or more days late than in any state but Nevada (Federal Reserve Bank of New York, end of 2025). This is household debt, not state government debt.
Ranks among the 50 states and D.C., highest first: card 11th, collections 18th, mortgage tied for 6th, auto tied for 14th. The U.S. figure is the population-weighted average of the states, our calculation.
At the end of 2019, 22.7% of Floridians had a debt in collections. Much of the drop since came when the credit bureaus stopped reporting many medical debts in 2022 and 2023. The share of Americans with a medical debt on their credit report fell from about 14% to about 5% (Consumer Financial Protection Bureau). So the drop mostly shows what the reports count, not fewer people struggling.
Other signs of strain
| Measure | Fla. | U.S. | Rank |
|---|---|---|---|
| People with any debt 90+ days late, early 2025 15th highest | 19.3% U.S. 17.2% | 17.2% | 15th highest |
| People with a credit score under 620, early 2025 Tied for 12th highest | 15.3% U.S. 13.8% | 13.8% | Tied for 12th highest |
| Mortgages 30 to 89 days late, Sept. 2025 Tied for 16th highest | 1.8% U.S. 1.6% | 1.6% | Tied for 16th highest |
Any debt and credit scores: Federal Reserve Bank of Philadelphia. Mortgages 30 to 89 days late, an early stage of falling behind: Consumer Financial Protection Bureau.
Dollars behind, a second measure
The New York Fed counts something different: the share of what Floridians owe that is 90 or more days late. Florida’s card balances were the 2nd most behind of any state in 2019 too, so this isn’t new. Floridians also carry more card debt: $5,050 per person with a credit report, against $4,350 nationwide, the 7th highest.
| Loan type | Fla. | U.S. | Fla. 2019 | U.S. 2019 |
|---|---|---|---|---|
| Credit card | 14.9% End of 2025 U.S. 12.4% Fla. 2019 10.5% · U.S. 2019 8.1% | 12.4% | 10.5% | 8.1% |
| Auto loan | 5.5% End of 2025 U.S. 5.2% Fla. 2019 5.8% · U.S. 2019 4.9% | 5.2% | 5.8% | 4.9% |
| Mortgage | 1.4% End of 2025 U.S. 0.9% Fla. 2019 1.5% · U.S. 2019 1.0% | 0.9% | 1.5% | 1.0% |
Share of balances 90 or more days past due, end of 2025 and end of 2019. Source: Federal Reserve Bank of New York, Consumer Credit Panel / Equifax. Not comparable with the Philadelphia Fed figures above, which count people, not dollars.
Bankruptcy
In 2025, 44,661 bankruptcy cases were filed in Florida: 191.1 for every 100,000 residents, against 167.1 nationwide, the 17th highest rate. Filings rose 20.2% from 2024, the 4th fastest rise of the 50 states and D.C., against 11.1% nationwide, and are back above their 2018 level after a low in 2022 (U.S. Courts). Florida’s homestead protection shields a home from most creditors with no dollar limit (Florida Constitution); one possibility, ours, is that this makes filing more useful to homeowners here than in most states.
How does foreclosure work in Florida?
Every Florida foreclosure goes through a court. The lender files a lawsuit, the homeowner has 20 days after being served to answer it, and if the judge rules for the lender, the home is usually sold at auction 20 to 35 days after the judgment. No law sets how long the court case itself takes (Florida Statutes). Until the clerk files the certificate of sale, the homeowner can still stop the sale by paying the full amount the judgment sets. Florida had the highest foreclosure rate of any state in the first half of 2026: filings on 27,494 properties, about one in every 373 homes, against one in 632 nationwide (ATTOM, a property data company, via News4JAX).
- Goes through a court
- Yes
- Time to answer the lawsuit
- 20 days after being served
- Stop the sale by paying the full judgment amount
- Yes, until the clerk files the certificate of sale
- Lenders can sue for the balance left after the sale
- Yes; for a home you live in, only up to the debt minus the home’s fair market value, and within one year
- Right to buy the home back after the sale
- No
- Home protected from other creditors (homestead protection)
- No dollar limit
- Statewide foreclosure mediation
- No; some local courts run their own, such as Hillsborough County’s
What the law says. Sources: Florida Statutes 45.031, 45.0315, 95.11 and 702.06; Florida Rules of Civil Procedure; Florida Constitution, Article X, Section 4. How foreclosure works in Florida →
Florida’s share of the federal Homeowner Assistance Fund assisted 68,843 homeowners, a count that includes housing counseling, and paid out $669.2 million of its $676.1 million (U.S. Treasury, through early 2026). The state’s program is now closed.
Mortgage complaints
Floridians have sent 48,335 mortgage complaints to the Consumer Financial Protection Bureau since 2012. The most common were about loan modification, collection or foreclosure (12,735), trouble during the payment process (12,543), and loan servicing, payments or escrow (7,362).
- Oct. 6, 2026 CountryPlace Acceptance Trouble fixing a problem with the loan In progress
- Oct. 5, 2026 Kind Holdings Escrow, taxes or insurance In progress
- Oct. 2, 2026 Navy Federal Credit Union Struggling to pay: an existing modification or forbearance plan In progress
- Oct. 1, 2026 Carrington Mortgage Services Trouble fixing a problem with the loan In progress
- Oct. 1, 2026 Lakeview Loan Servicing Struggling to pay: trouble fixing a problem with a modification, forbearance or foreclosure Closed with explanation
- Sept. 30, 2026 PennyMac Loan Services Escrow, taxes or insurance Closed with relief
- Sept. 30, 2026 Figure Technologies Payment process Closed with explanation
- Sept. 29, 2026 Bank of America Escrow, taxes or insurance Closed with relief
- Sept. 29, 2026 PennyMac Loan Services Struggling to pay: an existing modification or forbearance plan In progress
- Sept. 29, 2026 Data Mortgage Trouble fixing a problem with the loan Closed with explanation
The latest ten Florida complaints about paying a mortgage or getting help with one (not about getting a new loan), newest first, from the Consumer Financial Protection Bureau’s public complaint record, as of Oct. 9, 2026. A complaint is one person’s account; the bureau doesn’t verify it. Show all 48,335 →
What to watch before the next edition
Four things will show up in Florida household budgets over the next year, the nearest first.
-
From Nov. 1, 2026
Health plan sign-ups for 2027
Open enrollment for 2027 HealthCare.gov plans runs from Nov. 1 to Jan. 15; plans chosen by Dec. 15 start on Jan. 1. About 4.5 million Floridians signed up for 2026 plans, after the larger federal tax credits expired (see what changed).
-
Nov. 3, 2026
The property tax vote
Voters decide Amendment 3, which needs 60% to pass. If it does, the homestead exemption for non-school property taxes rises from $50,000 to $150,000 on Jan. 1, 2027 (see what changed).
-
Nov. 10, 2026
New figures on household debt
The Federal Reserve Bank of New York publishes its quarterly report on household debt and credit, covering July to September 2026. It will show how much Americans owe and how much of it is 90 or more days late. This page’s Florida figures come from the bank’s yearly state data, through the end of 2025.
-
Sept. 30, 2027
The minimum wage starts rising with inflation
Florida calculates its first minimum wage adjusted for inflation, raising the $15.00 hourly rate by the rise in prices over the year to Sept. 1. The new rate takes effect on Jan. 1, 2028.
Where Florida ranks highest and lowest
| Measure | Fla. | U.S. | Rank | Latest data |
|---|---|---|---|---|
| State Distress Index score 3rd highest · Aug. 2026 | 96 | 3rd highest | Aug. 2026 | |
| Renters paying half or more of income on housing Highest · 2024 | 32.1% U.S. 26.1% | 26.1% | Highest | 2024 |
| Change in home prices Lowest · 2025 | −0.5% U.S. +2.9% | +2.9% | Lowest | 2025 |
| Mortgages with less than 10% equity 2nd highest · Mid-2026 | 7.8% U.S. 4.7% | 4.7% | 2nd highest | Mid-2026 |
| Card balances 90+ days late 2nd highest · End of 2025 | 14.9% U.S. 12.4% | 12.4% | 2nd highest | End of 2025 |
| Rise in bankruptcy filings 4th highest · 2025 | 20.2% U.S. 11.1% | 11.1% | 4th highest | 2025 |
| Income from dividends, interest and rent 2nd highest · 2024 | 30.2% U.S. 21.0% | 21.0% | 2nd highest | 2024 |
| Residents 65 or older 3rd highest · 2024* | 21.3% U.S. 17.2% | 17.2% | 3rd highest | 2024* |
| Residents without health insurance 4th highest · 2024* | 11.5% U.S. 8.4% | 8.4% | 4th highest | 2024* |
| Median rent 9th highest · 2024* | $1,669 U.S. $1,413 | $1,413 | 9th highest | 2024* |
| Unemployment rate, three-month average 13th highest · June–August 2026 average | 4.6% U.S. 4.1% | 4.1% | 13th highest | June–August 2026 average |
| Residents in poverty Tied for 19th highest · 2024 | 12.1% U.S. 12.1% | 12.1% | Tied for 19th highest | 2024 |
| Median household income 27th highest · 2024 | $77,687 U.S. $81,604 | $81,604 | 27th highest | 2024 |
| Population growth since 2020 2nd highest · 2025 | 8.7% | 2nd highest | 2025 | |
| Share of income from wages 7th lowest · 2024 | 43.1% U.S. 49.7% | 49.7% | 7th lowest | 2024 |
“Highest” and “lowest” mean among the 50 states and D.C. * Census five-year survey, 2020 to 2024. Sources for each measure are in Sources and method. Download this table: CSV.
Questions about Florida
Is it expensive to live in Florida?
For renters, yes: in 2024, 32.1% of Florida renter households spent half or more of their income on rent and utilities, the highest share of any state (Census Bureau, American Community Survey). Day-to-day costs sit near the middle: MIT’s estimate of what a single adult needs to get by ranks 24th of the 50 states and D.C. We don’t measure the prices of food, gas or insurance.
Is Florida a poor state?
No. In 2024, 12.1% of Floridians lived in poverty, the same share as the nation, and the typical household earned $77,687, the 27th highest of the 50 states and D.C. (U.S. Census Bureau). Even so, Florida is the 3rd most distressed state on our State Distress Index, mostly because of renters’ housing costs, late payments and rising unemployment.
What is the poorest county in Florida?
Hamilton County, on the Georgia line. In 2024, 25.3% of its residents lived in poverty, and its typical household earned $48,859, both the worst in Florida (U.S. Census Bureau, Small Area Income and Poverty Estimates). On our County Distress Index it is the 2nd most distressed county, behind Gadsden.
What is the richest county in Florida?
St. Johns County, around St. Augustine. Its typical household earned $117,178 in 2024, the most in the state, and 5.8% of residents lived in poverty, the lowest share (U.S. Census Bureau). Collier ($97,022) and Monroe ($94,752) come next. St. Johns is also the least distressed of Florida’s 67 counties on our index.
Are people leaving Florida?
No. More people still move in than leave, but the gap has nearly closed. Florida had 23,462,518 people in 2025, 8.7% more than in 2020, the 2nd fastest growth of any state (Census Bureau). About 22,000 more people moved to Florida from other states than left in 2025, against about 208,000 a year from 2020 to 2022 (The Conversation, via WUSF).
What is Florida’s unemployment rate?
Florida’s rate averaged 4.6% from June to August 2026, above the U.S. rate of 4.1% (Bureau of Labor Statistics). It was 3.5% at the end of 2024.
What is the poverty level in Florida?
The 2026 federal poverty guideline in Florida is $15,960 a year for one person and $33,000 for a family of four, the same as in every state but Alaska and Hawaii (U.S. Department of Health and Human Services).
How many counties are in Florida?
Florida has 67 counties, and every one is ranked on our County Distress Index: see all 67, ranked.
Cite or reuse Florida’s data
For grant applications, legislative memos and news stories.
State Distress Index
Florida
3rdmost distressed state
of the 50 states and D.C.
More distressed than 96% of the other states and D.C.
Florida is the 3rd most distressed of the 50 states and D.C. on the State Distress Index, American Default Research’s measure of household financial distress. In 2024, 32.1% of Florida renter households spent half or more of their income on rent and utilities, the highest share of any state, against 26.1% nationwide (U.S. Census Bureau). In early 2025, 15.8% of Floridians with a credit card had one 90 or more days late, against 13.5% nationwide (Federal Reserve Bank of Philadelphia).
Questions, interviews or a custom cut of the data: press@americandefault.org
Sources and method
We gather the data, run the numbers and research each state ourselves.
This edition: October 2026 · Next edition expected March 2027
- Late payments, collections, credit scoresFederal Reserve Bank of Philadelphia, Consumer Credit Explorerearly 2025
- Debt and dollars behindFederal Reserve Bank of New York, Consumer Credit Panel / Equifaxend of 2025
- Mortgages 30 to 89 days late; mortgage complaintsConsumer Financial Protection Bureau: Mortgage Performance Trends; complaint databaseSept. 2025; Oct. 9, 2026
- Bankruptcy filingsAdministrative Office of the U.S. Courts, Table F-22024 and 2025
- Unemployment and jobsU.S. Bureau of Labor Statistics: state, county and national unemployment; Florida jobsAug. 2026
- Poverty and incomeCensus Bureau, Small Area Income and Poverty Estimates2024
- Renters paying half or more of income on housingCensus Bureau, American Community Survey 1-year2005 to 2024
- Rent, homeowners’ costs, age, health insuranceCensus Bureau, American Community Survey 5-year2020 to 2024
- PopulationCensus Bureau, census and annual estimates2020 to 2025
- Where income comes fromU.S. Bureau of Economic Analysis2024
- Home prices; mortgage equityFederal Housing Finance Agency (house price index; National Mortgage Database)2025; mid-2026
- Energy billsU.S. Department of Energy, Low-Income Energy Affordability Data (state figure: our calculation)2022
- Cost of getting byMIT Living Wage Calculatorretrieved July 2026
- SNAP; households short of foodU.S. Department of Agriculture Food and Nutrition Administration; U.S. Department of Agriculture Economic Research ServiceJune 2026; 2022 to 2024
- Poverty guidelineU.S. Department of Health and Human Services2026
- Mortgage help fundU.S. Treasury, Homeowner Assistance Fundthrough early 2026
- Foreclosure rate; foreclosure lawATTOM, via News4JAX; Florida Statutes and Constitutionfirst half of 2026
- Home insurance; condo costsFlorida Office of Insurance Regulation, via WPTV; WWSB; Insurance Journal (2022, 2023); Federal Reserve Bank of Atlanta2021 to 2026
- Disaster declarationsFederal Emergency Management Agency2022 to 2024
- Moves in and out of FloridaThe Conversation, via WUSF; University of Florida2025
- What changed in the past yearThe news and agency sources linked with each item (see what changed)Nov. 2025 to Nov. 2026
The score has four equal parts: late payments; collections and bankruptcy; jobs; and renters’ housing costs. Each measure is ranked against the 50 states and D.C., and the score is the share of the other 50 that Florida is more distressed than. The full method →
We write with AI tools, and Ross Kilburn checks and reviews every page before it's published.
Get the next Florida edition by email
One email each time a new Florida edition is out; the next is expected in March 2027. Unsubscribe anytime.
Thanks, that helps.