Indiana has had one of the 10 highest bankruptcy rates for 21 straight years
Each state is shaded by how distressed its households are, from green (least) to red (most), with data through September 2026. Indiana scores 50 out of 100.
Few Hoosiers are out of work: the August 2026 jobless rate, 3.3%, was significantly below the nation's. Car loans are the weak spot, with 9.6% of car-loan borrowers at least three months behind in early 2025. Delaware County, home to Muncie, is the poorest in Indiana and the most distressed: more distressed than 85% of U.S. counties. Hamilton County, the suburbs north of Indianapolis, is the 75th least distressed of all 3,144 U.S. counties.
- Score
- 50/100
- Data through
- September 2026
- Edition
- October 2026
Next edition expected March 2027
How Indiana ranks among the states
Indiana lands in the middle because two parts of its score point in opposite directions. Its residents filed for bankruptcy at the 7th highest rate among the 50 states and D.C. in 2025 (Administrative Office of the U.S. Courts), yet fewer of its workers were jobless in August 2026 than in most states. So the collections and bankruptcy part of its score is in the top quarter of states, while the jobs part is in the bottom quarter (see bankruptcy).
What drives the score
Each part below runs from 0 to 100 and shows where Indiana stands among the 50 states and D.C. on the measures inside it. The four parts average 54, but the State Distress Index score is a different number: the percentage of the other 50 places (49 states and D.C.) with a lower four-part average than Indiana’s. That is true of 25 of the 50, so Indiana scores 50. Put another way, a state that scores 80 is more distressed than 80% of the others.
- Collections and bankruptcy75Indiana’s 2025 bankruptcy filing rate is what lifts this part; the share of residents with a credit record and a debt sent to collectors, 13.6% in early 2025, was close to the U.S. share of 13.2%.
- Late payments61Car loans stand out: in early 2025, 9.6% of Indiana car-loan borrowers were 90 days or more behind, against 8.5% nationwide, while card and mortgage borrowers were near the U.S. shares.
- Renters’ housing costs54Rent and utilities took half or more of the income of 24.1% of Indiana renter households in 2024, a little under the U.S. share of 26.1%.
- Jobs25Unemployment averaged 3.3% over June, July and August 2026, against 4.1% for the country, lower than in most states.
Three of Indiana’s four neighbors score higher
Michigan, Kentucky and Illinois all score well above Indiana, and Michigan is among the most distressed states in the country. Ohio, to the east, is the closest, a few points lower.
State Distress Index score, 0 to 100. Of the 50 states and D.C., Michigan is the 5th most distressed and Ohio the 28th. In August 2026 the unemployment rate was 5.0% in Michigan, the highest of the five, 4.7% in both Illinois and Kentucky, and 3.3% in both Indiana and Ohio (U.S. Bureau of Labor Statistics).
Indiana was among the 10 most distressed states until early 2008 and hasn’t returned to that group since
At its worst
In the third quarter of 2006, the first quarter our index covers all four parts, Indiana scored 92, the 5th most distressed state. It stayed in the top 10 through the first quarter of 2008. Its best showing came in the second quarter of 2021: a score of 38, ranking 32nd.
What moved it
The big drops came from two different parts. In the third quarter of 2008, new Census renter figures cut the renters’ part from 74 to 42, and the score fell from 80 to 68. Over the first half of 2015, the jobs part, which sets Indiana’s unemployment against other states’, slid from 52 to 38, late payments eased a little, and the score went from 64 to 44. In every quarter on the chart, the collections and bankruptcy part has stayed between 72 and 82.
Since the chart ends
The quarterly history stops at the first quarter of 2025, when Indiana scored 60 and ranked 21st. Today it ranks 26th, with a score of 50. Most of the change came from jobs: unemployment averaged 3.8% over January to March 2025 and 3.3% over June to August 2026, and the jobs part dropped from 46 to 25. The 2025 Census renter figures left the renters’ part at 54, and late payments and collections moved little.
Indiana went from the 5th most distressed state in 2006 to the 21st in early 2025
Indiana’s State Distress Index score each quarter, on a 0 to 100 scale, from the third quarter of 2006, the first with all four parts, to the first quarter of 2025.
How is Indiana’s economy doing? Few people are out of work, but pay trails the nation
Joblessness is low. In August 2026, 3.3% of Indiana’s labor force was out of work and looking for a job, tied for 13th lowest among the 50 states and D.C. overall. By the Bureau of Labor Statistics’ test, that was significantly below the national rate of 4.1%. A year earlier, Indiana’s rate was 3.7%. Income is the weak spot: all the income Hoosiers received in 2024, divided by the number of residents, came to $64,077 a person, the 13th lowest among the 50 states and D.C., against $73,204 nationwide (U.S. Bureau of Economic Analysis).
Unemployment rate
3.3%
U.S. 4.1%
Tied for 13th lowest of the states and D.C. for August 2026
Yearly average unemployment rate
3.7%
U.S. 4.3%
Tied for 18th lowest of the states and D.C. for 2025
Highest county rate, Lake County
4.8%
August 2026, not adjusted for seasonal swings
It wasn’t always so. Indiana’s yearly unemployment rate was higher than the nation’s in seven of the nine years from 2005 to 2013, through the 2008 recession and the years after it. It hasn’t been above the U.S. rate in any year from 2014 through 2025.
Indiana’s yearly unemployment rate hasn’t topped the U.S. rate in any year from 2014 through 2025
Share of Indiana’s and the nation’s labor force without a job and looking for one, by month, seasonally adjusted, from January 1990 through August 2026. There is no October 2025 point because the survey was not taken during the federal shutdown; the title above compares yearly averages.
Unemployment is highest in Lake and Howard counties
| County | Rate |
|---|---|
| Lake (Crown Point) | 4.8% |
| Howard (Kokomo) | 4.6% |
| Delaware (Muncie) | 4.2% |
| Fayette (Connersville) | 4.2% |
| Marion (Indianapolis) | 3.6% |
| Pulaski (Winamac) | 2.7% |
| Union (Liberty) | 2.7% |
| Wells (Bluffton) | 2.7% |
Unemployment rate, August 2026, not adjusted for seasonal swings: the four highest of Indiana’s 92 counties (Delaware and Fayette share a rate), Marion for Indianapolis, and Pulaski, Union and Wells, which share the lowest rate. County seats are in parentheses. Source: U.S. Bureau of Labor Statistics.
Indiana’s minimum wage is the federal one
Indiana’s minimum wage is $7.25 an hour, the same as the federal minimum, the U.S. Department of Labor’s table shows. Three of its four neighbors pay more: Illinois, $15.00; Michigan, $13.73, set to rise to $15.00 on Jan. 1, 2027; and Ohio, $11.00 for employers with yearly sales of $405,000 or more. Kentucky’s rate is $7.25, like Indiana’s (U.S. Department of Labor). Recent layoff notices in Indiana →
The poorest and most distressed counties in Indiana: Delaware County tops both lists
Delaware County, home to Muncie, is the poorest of Indiana’s 92 counties and the most distressed. The Census Bureau estimates that 20.5% of its residents lived below the poverty line in 2024, and it scores 85 on our County Distress Index, which measures the strain on household budgets in every U.S. county. None of Indiana’s counties makes our national list of the 100 most distressed (the top 100). Hamilton County, the suburbs north of Indianapolis, is the least distressed, at 2, with the 75th lowest score of all 3,144 U.S. counties.
The strain is heaviest around Muncie and Richmond, in Indianapolis and in Lake County; the suburbs ringing Indianapolis carry the least
How each of Indiana’s 92 counties scores on the County Distress Index, from 0 to 100, using data through August 2026.
Loading the county map…
The county map could not be loaded. Every county is in the lists on this page.
Most distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 1 | Delaware | 85 | 20.5% |
| 2 | Wayne | 84 | 18.3% |
| 3 | Vigo | 82 | 18.3% |
| 4 | Grant | 82 | 17.9% |
| 5 | Marion | 82 | 15.8% |
| 6 | Lake | 81 | 13.3% |
| 7 | Fayette | 81 | 16.2% |
| 8 | Howard | 80 | 13.6% |
| 9 | Madison | 76 | 14.6% |
| 10 | Crawford | 69 | 16.4% |
Least distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 88 | Warren | 11 | 8.4% |
| 89 | Spencer | 6 | 10.4% |
| 90 | Boone | 5 | 5.6% |
| 91 | Dubois | 4 | 7.7% |
| 92 | Hamilton | 2 | 4.7% |
Rank among Indiana’s counties, 1 = most distressed. We rank on unrounded scores, so two counties that show the same score can hold different ranks. Poverty is each county’s 2024 rate from the Census Bureau.
Every county, by score
Of Indiana’s 92 counties, 8 score 80 or more, and they hold 28.1% of the state’s people. Counting every county at 60 or above, 18 counties hold 37.6% of Hoosiers; seven of those 18 are in east central Indiana, and Marion County alone is home to 37.5% of the people living in those 18 counties.
1 score 70–79
23 score 50–69
Crawford, Scott, St. Joseph, LaPorte, Vermillion, Jay, Switzerland, Fulton, Miami, Randolph, Cass, Vanderburgh, Jennings, Washington, Elkhart, Starke, Ohio, Blackford, Benton, Newton, Greene, Sullivan, Henry
Bloomington’s and Lafayette’s counties are among the poorest in Indiana but sit mid-pack on distress
The County Distress Index blends five parts, each worth a fifth: late payments; collections and bankruptcy; jobs; renters’ housing costs; and a fifth that combines poverty, child poverty, household income, disability and health insurance. For most of Indiana’s poorest counties, the two lists line up: Delaware, Wayne, Vigo and Grant, the four highest poverty rates, are all among the six most distressed. Two college counties break the pattern. Monroe County, home to Bloomington, and Tippecanoe County, home to Lafayette, have a poverty rate of 16.8%, tied for 5th highest in the state, yet Tippecanoe ranks 43rd on distress and Monroe 50th. Renters’ costs score among the highest in the state in both, but their collections and bankruptcy parts are among the lowest. The poverty rates here are the Census Bureau’s 2024 Small Area Income and Poverty Estimates; lists built on another survey or year can put a different county first.
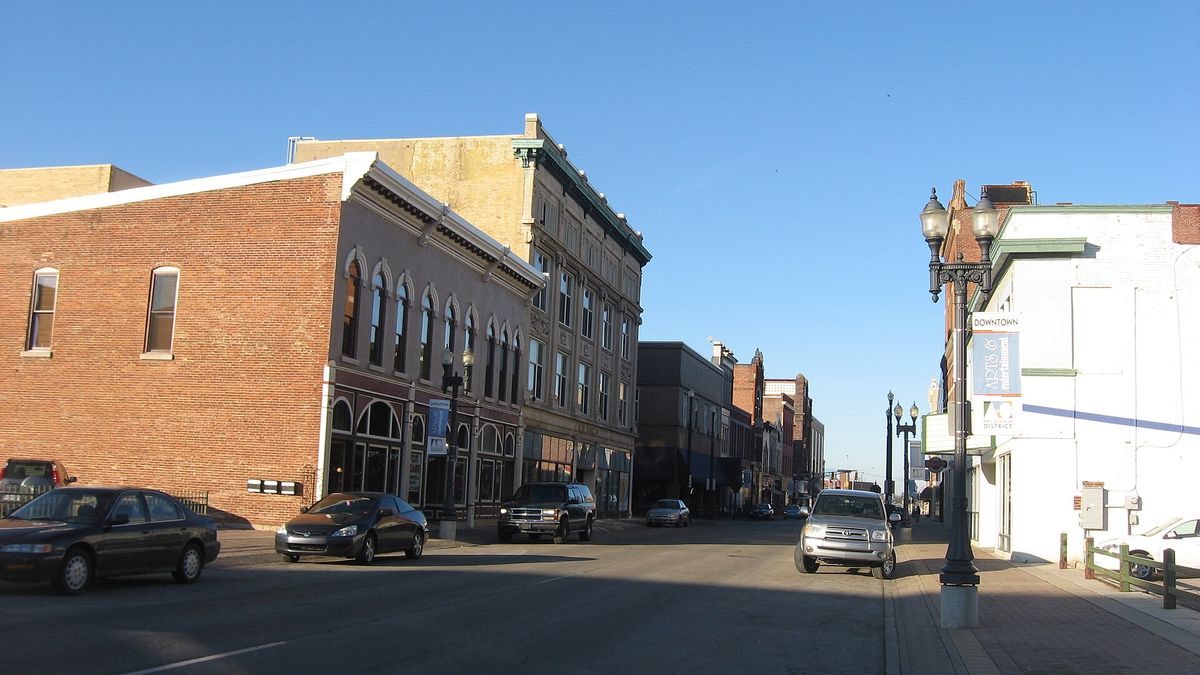
Walnut Street in downtown Muncie, the seat of Delaware County, in January 2012. Delaware’s typical household earned $55,462 in 2024, the 3rd lowest median income of Indiana’s 92 counties (Census Bureau). The county counted 111,903 residents in the 2020 census, down from 129,219 in 1970, its largest count since at least 1900.
Source: U.S. Census Bureau; American Default Research. Photo: Nyttend, public domain, via Wikimedia Commons.

Indianapolis carries far more strain than its suburbs, the least distressed part of the state
We sorted Indiana’s counties into nine groups of our own and weighted each county by its population, so a big county counts for more people than a small one. The groups and the averages are ours. Marion County, Indianapolis, holds 14.1% of Indiana’s people and scores 82. The suburban counties around it, Hamilton, Hendricks, Johnson, Hancock, Boone, Morgan, Shelby, Brown and Putnam, hold 15.4% and average 16, the lowest of any group, and none scores 60 or more. East central Indiana, 11 counties around Muncie, Anderson, Kokomo and Richmond, averages 76, and seven of them score 60 or more. Northwest Indiana, Lake, Porter and LaPorte counties beside Chicago, averages 68, pulled up by Lake County at 81, while Porter scores 33. The South Bend and Elkhart area averages 54, the Louisville area on the Indiana side 43, Fort Wayne and the northeast 37, the Evansville area 38. The other 42 counties, including Terre Haute’s Vigo County and the college counties of Monroe and Tippecanoe, 41. The averages say where strain is highest, not why.
Our grouping and averages, built from County Distress Index scores (American Default Research) with each county weighted by its Census population.
Is Indiana a poor state? Its poverty rate equals the nation’s, but incomes are lower
Not by the poverty rate. In 2024, 12.1% of Hoosiers lived below the poverty line, exactly the U.S. rate and tied for 19th highest among the 50 states and D.C. (Census Bureau, Small Area Income and Poverty Estimates). Household income tells a different story: the typical Indiana household earned $71,958, the 10th lowest among the 50 states and D.C., against $81,604 for the country.
Residents in poverty
12.1%
U.S. 12.1%
Tied for 19th highest of the states and D.C. for 2024
Children in poverty
15.8%
U.S. 15.5%
18th highest of the states and D.C. for 2024
Median household income
$71,958
U.S. $81,604
10th lowest of the states and D.C. for 2024
Indiana’s poverty rate was below the U.S. rate in every Census estimate through 2008; since 2009 the two have stayed within a point
Share of Hoosiers and of all Americans below the poverty line, 1989 to 2024. The Census Bureau published no state estimates for 1990 to 1992 or for 1994.
A smaller share of Hoosiers get SNAP than in most states
In June 2026, 488,244 Indiana residents got SNAP, the federal food benefit once called food stamps, the U.S. Department of Agriculture reports. That is 7.0% of the state’s 2025 population, the 10th lowest share among the 50 states and D.C., against 10.6% nationwide, even though Indiana’s poverty rate matches the country’s. The count fell 16.0% over the year from June 2025 and is below the 567,414 the state averaged from October 2019 to February 2020, before the pandemic. We found no count of Hoosiers who lost SNAP under the 2025 and 2026 rule changes, and a smaller count isn’t proof of less need: the Census poverty figures stop at 2024.
To apply for SNAP or check a case, start at Indiana’s family and social services agency →
Little income from savings and investments
Dividends, interest and rent made up 16.3% of all the income Hoosiers received in 2024, the 3rd lowest share among the 50 states and D.C., against 21.0% nationwide. Government benefits such as Social Security, Medicare and Medicaid made up 20.5%, more than the 18.3% nationwide (U.S. Bureau of Economic Analysis).
Why another site may show a different poverty rate for Indiana
Many sites quote the Census Bureau’s American Community Survey, which puts Indiana’s poverty rate a little higher or lower depending on the year. This page uses the bureau’s Small Area Income and Poverty Estimates, published every year for each state and county, so the state and county rates here come from one source. Programs that decide who qualifies for help use a separate yardstick, the federal poverty guideline, covered in the questions below. Indiana’s poorest counties →
What changed in Indiana in the past year
-
Oct. 5, 2026
The state says many Healthy Indiana Plan members aren’t yet meeting a coming work rule
Starting Jan. 1, 2027, adults ages 19 to 64 in the Healthy Indiana Plan, the state’s Medicaid plan for working-age adults, will have to spend at least 80 hours a month working, in school, in training or volunteering, unless an exemption applies. On Oct. 5, Indiana’s family and social services agency estimated that more than 58,000 members were not yet meeting the rule. For people applying in January, the agency says, the months that count are October, November and December 2026 (see what to watch).
Indiana’s family and social services agency, HIP work requirements
-
Oct. 5, 2026
A layoff notice in Gas City, in one of Indiana’s most distressed counties
American Woodmark told Indiana’s workforce agency on Oct. 5 that it would lay off 207 workers in Gas City, in Grant County, on Dec. 5. The agency’s current list of these notices, which employers file ahead of large layoffs and closings, also shows Thyssenkrupp Presta closing its plant in Terre Haute, in Vigo County, with 207 workers, by March 31, 2027, and ZF Active Safety and Electronics closing in Lafayette, with 133, on Nov. 30. Grant and Vigo both score 80 or more on our County Distress Index, among the most distressed counties in the state. A notice is an employer’s plan, not a count of all jobs lost.
Indiana’s workforce agency, current layoff and closing notices
-
July 15, 2026
The utility regulator opened two investigations into energy costs
Indiana’s utility regulator released a report on energy affordability and opened two investigations, one into the profit rates utilities are allowed to earn and one into the add-on charges, called trackers, that appear on bills (Cause Nos. 46428 and 46429). The commission said the steps came out of an inquiry hearing it held on March 24 and 10 public listening sessions in March and April, and include steps to carry out a 2026 state law on energy affordability, House Enrolled Act 1002.
-
June 17, 2026
Regulators approved a rate increase for AES Indiana, the Indianapolis electric utility
The Indiana Utility Regulatory Commission approved, with changes, a settlement that lets AES Indiana raise its yearly revenue by about $71.1 million, less than the $192.9 million the utility first asked for (Cause No. 46258). Three commissioners agreed, one dissented and one did not take part. The state’s utility consumer counselor asked the commission on July 7 to reconsider. We found no figure for what the increase adds to a typical home bill, so this page doesn’t give one.
Indiana Utility Regulatory Commission, order in Cause No. 46258; Indiana Office of Utility Consumer Counselor
-
May 11, 2026
The first property tax bills under Indiana’s 2025 property tax law came due
Indiana homeowners pay property taxes in two installments, due May 11 and Nov. 10 in 2026, to their county treasurer. In June 2025 the state’s local government finance agency said Senate Enrolled Act 1, the 2025 property tax law, applies starting with these 2026 bills; it adds a homestead credit worth 10% of the home’s tax, up to $300, and a new credit for owners 65 and older.
Indiana Department of Local Government Finance, legislative update, June 18, 2025; property tax due dates
-
Jan. 1, 2026
SNAP stopped paying for candy and sugary drinks in Indiana
Under a waiver the U.S. Department of Agriculture approved on May 22, 2025, Indiana’s SNAP benefits can’t be used to buy candy or sugary drinks starting Jan. 1, 2026; the state calls it Smart SNAP. The state agency also says the 2025 federal budget law’s SNAP changes are in place, among them a work rule that now reaches adults up to age 64 and parents whose youngest child is 14 or older (see SNAP).
Indiana’s family and social services agency, Smart SNAP; SNAP page
Is Indiana cheap to live in? Housing costs less than in most states
For housing, yes. Half of Indiana renters paid less than $1,062 a month in the Census Bureau’s 2020 to 2024 survey, the 14th lowest median rent among the 50 states and D.C., against $1,413 nationwide. Twelve months of that rent equal 17.7% of the typical household’s 2024 income, compared with 20.8% nationally (our calculation). We hold no prices for food, gas or electricity, so we can’t rank Indiana’s overall cost of living.
Median rent, a month
$1,062
U.S. $1,413
14th lowest of the states and D.C. for 2020 to 2024
Homes lived in by their owners
70.6%
U.S. 65.2%
12th highest of the states and D.C. for 2020 to 2024
Homeowners spending at least 30% of income on housing
16.6%
U.S. 22.5%
3rd lowest of the states and D.C. for 2020 to 2024
Every year since 2007, Indiana renters have been less likely than the nation’s to spend half their income on housing
Renter households whose rent and utilities take half or more of their income, Indiana and the U.S., from the Census Bureau’s one-year surveys, 2005 to 2024; no figures were published for 2020.
This share is the measure behind the renters’ part of our State Distress Index. New figures arrive once a year, so it can move Indiana’s score in a single quarter, as it did in 2008 and 2023 (see how it ranks).
Covering basic needs costs less in Indiana than in most states, by MIT’s estimate
The MIT Living Wage Calculator estimates that one adult with no children needs $45,326 a year before taxes for basic needs in Indiana. That is the 18th lowest among the 50 states and D.C. Two working parents with two children need $120,833 (figures updated Feb. 15, 2026). Those budgets leave nothing for savings. Property tax bills changed for 2026 too (see what changed).
Rent takes a smaller bite of income in Indiana than in three of its four neighbors
Rent is higher in Illinois and Michigan and lower in Ohio and Kentucky. Measured against what households earn, only Ohio’s rent takes a smaller share than Indiana’s.
| State | Rent, a month | Median household income | Rent as share of income |
|---|---|---|---|
| Illinois Rent as share of income 18.3% | $1,274 Median household income $83,327 | $83,327 | 18.3% |
| Michigan Rent as share of income 18.7% | $1,129 Median household income $72,336 | $72,336 | 18.7% |
| Indiana Rent as share of income 17.7% | $1,062 Median household income $71,958 | $71,958 | 17.7% |
| Ohio Rent as share of income 17.2% | $1,034 Median household income $72,259 | $72,259 | 17.2% |
| Kentucky Rent as share of income 18.0% | $967 Median household income $64,481 | $64,481 | 18.0% |
Rent: median gross rent a month, 2020 to 2024 (Census Bureau, American Community Survey). Income: median household income, 2024 (Census Bureau, Small Area Income and Poverty Estimates). The share is ours: 12 months of median rent divided by median household income. Rent and housing costs by state →
Bankruptcy in Indiana: among the highest filing rates every year since 2005
Hoosiers filed 18,210 bankruptcy cases in 2025, or 261.1 for every 100,000 residents (2025 population), the 7th highest rate among the 50 states and D.C. and far above the national rate of 166.3 (Administrative Office of the U.S. Courts). Filings rose 11.6% from 2024, about as fast as the 11.1% rise nationwide, and 2025 brought the most since 2019, when Hoosiers filed 23,332 cases.
A high rate isn’t new. Dividing each year’s filings by that year’s Census population estimate, we found Indiana among the 10 states with the highest filing rate in every year from 2005 to 2025, and first of all in 2005. Of its four neighbors, only Kentucky had a higher rate in 2025. We found no source that explains why Indiana’s rate runs so high.
Chapter 13 made up 43.4% of Indiana’s 2025 cases, the 12th highest share among the states, against 35.9% nationwide. In a Chapter 13 case the filer repays part of what they owe over three to five years under a plan the court approves. Chapter 7, the more common kind across the country, cancels many debts but can mean selling property the law doesn’t shield.
| Year | Filings |
|---|---|
| 2005 | 78,959 |
| 2010 | 47,304 |
| 2015 | 26,600 |
| 2019 | 23,332 |
| 2020 | 17,298 |
| 2021 | 14,487 |
| 2022 | 13,076 |
| 2023 | 14,681 |
| 2024 | 16,319 |
| 2025 | 18,210 |
Cases under every chapter in Indiana’s two federal bankruptcy courts, the Northern and Southern districts, in selected years and each year since 2019. The available series run from 2001 to 2025 without 2004; of those years, filings peaked in 2005 and bottomed out in 2022. Source: Administrative Office of the U.S. Courts, Table F-2. Bankruptcy filings in every state →
Are Hoosiers behind on their bills? As often as Americans overall, and more often on car loans
About as often as the rest of the country, except on car loans. In early 2025, 17.2% of Indiana residents with a credit record had a debt 90 or more days late, the same as the U.S. share, our population-weighted average of the states (Federal Reserve Bank of Philadelphia). Car-loan borrowers fell that far behind more often: 9.6% in Indiana, against 8.5% nationwide. These figures cover what households owe, not debt owed by the state government.
Among the 50 states and D.C., counted from the largest share, Indiana ranks tied for 14th on car loans, 20th on collections, 20th on cards and tied for 20th on mortgages. Each U.S. bar averages the states, with bigger states counting for more.
More Indiana card borrowers are far behind than before the pandemic: 9.0% at the end of 2019, 13.6% in early 2025. The collections share fell over the same years, from 21.3% to 13.6%, while the three big credit bureaus removed many medical debts from credit reports; a debt dropped from a report hasn’t necessarily been paid. Across the country, the share of people with a medical collection on their report went from about 14% in March 2022 to about 5% in June 2023 (Consumer Financial Protection Bureau).
Counted in dollars, Indiana car loans are among the most often far behind
The Federal Reserve Bank of New York measures the share of dollars owed that is 90 or more days late, not the share of people. At the end of 2025, 6.3% of Indiana car-loan balances were that far behind, tied for 6th highest among the 50 states and D.C. and above the U.S. share of 5.2%; in 2019 Indiana had been at 5.2%. Card dollars ran below the U.S. share, mortgage dollars a little above it.
| Loan type | Indiana | U.S. | Indiana 2019 | U.S. 2019 |
|---|---|---|---|---|
| Auto loan | 6.3% End of 2025 U.S. 5.2% Indiana 2019 5.2% · U.S. 2019 4.9% | 5.2% | 5.2% | 4.9% |
| Credit card | 11.7% End of 2025 U.S. 12.4% Indiana 2019 7.0% · U.S. 2019 8.1% | 12.4% | 7.0% | 8.1% |
| Mortgage | 1.1% End of 2025 U.S. 0.9% Indiana 2019 1.0% · U.S. 2019 1.0% | 0.9% | 1.0% | 1.0% |
Share of balances 90 or more days past due at the end of 2025 and the end of 2019. Source: Federal Reserve Bank of New York, Consumer Credit Panel / Equifax. It counts dollars, not people, so it doesn’t line up exactly with the Philadelphia Fed chart above, and it includes old debts lenders have written off but still report.
Hoosiers carry less debt than people in most states
At the end of 2025, household debt in Indiana came to $49,330 per person with a credit report, against $63,200 nationwide (Federal Reserve Bank of New York). Mortgages a month or two behind were more common than in most states: 2.0% in September 2025, tied for 11th highest, against 1.6% for the U.S. (Consumer Financial Protection Bureau).
| Measure | Indiana | U.S. | Rank |
|---|---|---|---|
| Household debt per person with a credit report, end of 2025 14th lowest | $49,330 U.S. $63,200 | $63,200 | 14th lowest |
| Card balances per person with a credit report, end of 2025 8th lowest | $3,410 U.S. $4,350 | $4,350 | 8th lowest |
| Mortgages with less than 10% equity, mid-2026 Tied for 23rd highest | 4.3% U.S. 4.7% | 4.7% | Tied for 23rd highest |
Rank among the 50 states and D.C. Debt and card balances: Federal Reserve Bank of New York. Equity: Federal Housing Finance Agency, second quarter of 2026. Late payments in every state →
Is Indiana a judicial foreclosure state? Yes: a lender has to go to court
Yes. To foreclose on a home in Indiana, a lender files a lawsuit in court, and a sheriff’s sale comes only after the court grants a judgment. Before filing, the lender has to send the homeowner a pre-suit notice by certified mail, on a form the state’s housing and community development authority sets, and in most cases wait at least 30 days after sending it (Ind. Code § 32-30-10.5-8).
That notice points homeowners to the Indiana Foreclosure Prevention Network, a free state program, at 877-438-4673 (877-GET-HOPE). Once a lawsuit is filed, the owner of a home they live in may have the right to a settlement conference with the lender, a meeting to look for a way to avoid foreclosure. The lawsuit papers must include a notice about it. Up to the sheriff’s sale, the owner can stop it by paying the judgment (Ind. Code § 32-29-7-7). Federal rules generally keep a mortgage company from starting a foreclosure on a primary home until the loan is more than 120 days behind.
- Goes through a court
- Yes
- Notice before the lawsuit
- At least 30 days
- Settlement conference
- May be available
- Stopping the sale
- Pay the judgment
- Federal wait before starting
- Over 120 days behind
What the law says for a home you live in. Sources: Ind. Code §§ 32-30-10.5-8 and 32-29-7-7, as cited in the state’s pre-suit notice form and its instructions; federal rule 12 CFR 1024.41. How foreclosure works in Indiana →
Indiana was awarded $167.9 million from the federal Homeowner Assistance Fund and had helped 11,332 households with it, by its last report to the U.S. Treasury in early 2026. The state program’s site says it made its final payments in August 2024 and is closed. For help available today, see Indiana’s foreclosure guide.
Payment problems lead Indiana’s mortgage complaints to the CFPB
Since 2012, the Consumer Financial Protection Bureau has logged 4,673 mortgage complaints from Indiana. Problems with the payment process, such as how payments, fees and escrow are handled, come up most, in 1,307 complaints; trouble with loan modifications, collection and foreclosure is next, at 886.
- Oct. 8, 2026 PNC Bank Payment process In progress
- Oct. 4, 2026 PCH JV Ventures #9, LLC Struggling to pay: trouble reaching the company about a modification, forbearance or foreclosure Closed with explanation
- Sept. 30, 2026 Rocket Mortgage Struggling to pay: trouble reaching the company about a modification, forbearance or foreclosure In progress
- Sept. 29, 2026 PNC Bank Payment process: trouble reaching the company to fix a problem with the loan In progress
- Sept. 25, 2026 PNC Bank Struggling to pay: applying for a modification, forbearance, short sale or deed-in-lieu In progress
- Sept. 24, 2026 Freedom Mortgage Payment process: trouble reaching the company to fix a problem with the loan In progress
- Sept. 22, 2026 Lakeview Loan Servicing Payment process Closed with explanation
- Sept. 22, 2026 Ocwen / Onity Group Struggling to pay: an existing modification, forbearance or other relief Closed with explanation
- Sept. 21, 2026 PennyMac Struggling to pay: applying for a modification, forbearance, short sale or deed-in-lieu Closed with explanation
- Sept. 20, 2026 Rocket Mortgage Payment process: escrow, taxes or insurance In progress
The 10 newest Indiana complaints about paying a mortgage or getting help with one, newest first, from the Consumer Financial Protection Bureau’s public complaint database as we pulled it in October 2026. We leave out complaints about getting a new loan and any that name a credit bureau. Each is one person’s account, which the bureau doesn’t verify, and a complaint doesn’t show that a company did anything wrong. Every Indiana mortgage complaint at the Consumer Financial Protection Bureau →
What to watch before the next edition
These dates, nearest first, come from the agencies that set them.
-
Oct. 20, 2026
September unemployment for Indiana
The U.S. Bureau of Labor Statistics is scheduled to publish state unemployment rates for September at 10 a.m. Eastern. Indiana’s August rate was 3.3%.
U.S. Bureau of Labor Statistics, state employment and unemployment release
-
Nov. 10, 2026
Second property tax installment due
The second half of 2026 property taxes is due to county treasurers. The state’s finance agency says a payment made within 30 days of the due date by an owner with no back taxes on the property draws a smaller penalty.
Indiana Department of Local Government Finance, property tax due dates
-
Nov. 23, 2026
Old SNAP benefits start being removed from cards
From this date, the state will remove SNAP benefits that are at least 274 days old, about nine months, from EBT accounts, whether or not the card has been used. Removed benefits can’t be replaced, the state agency says.
-
Jan. 1, 2027
Healthy Indiana Plan work rule begins
The work rule applies to new applications and renewals started on or after this date (see what changed).
Indiana’s family and social services agency, HIP work requirements
Where Indiana ranks highest and lowest
| Measure | Indiana | U.S. | Rank | Latest data |
|---|---|---|---|---|
| Bankruptcy filings per 100,000 residents (2025 population) 7th highest · 2025 | 261.1 U.S. 166.3 | 166.3 | 7th highest | 2025 |
| Car-loan dollars 90+ days late Tied for 6th highest · End of 2025 | 6.3% U.S. 5.2% | 5.2% | Tied for 6th highest | End of 2025 |
| Mortgages 30 to 89 days late Tied for 11th highest · Sept. 2025 | 2.0% U.S. 1.6% | 1.6% | Tied for 11th highest | Sept. 2025 |
| Share of bankruptcy filings under Chapter 13 12th highest · 2025 | 43.4% U.S. 35.9% | 35.9% | 12th highest | 2025 |
| Homes lived in by their owners 12th highest · 2024* | 70.6% U.S. 65.2% | 65.2% | 12th highest | 2024* |
| Residents in poverty Tied for 19th highest · 2024 | 12.1% U.S. 12.1% | 12.1% | Tied for 19th highest | 2024 |
| Median household income 10th lowest · 2024 | $71,958 U.S. $81,604 | $81,604 | 10th lowest | 2024 |
| Residents getting SNAP food benefits (2025 population) 10th lowest · June 2026 | 7.0% U.S. 10.6% | 10.6% | 10th lowest | June 2026 |
| Unemployment rate, three-month average Tied for 11th lowest · June–August 2026 | 3.3% U.S. 4.1% | 4.1% | Tied for 11th lowest | June–August 2026 |
| Median rent, a month 14th lowest · 2024* | $1,062 U.S. $1,413 | $1,413 | 14th lowest | 2024* |
| Household debt per person with a credit report 14th lowest · End of 2025 | $49,330 U.S. $63,200 | $63,200 | 14th lowest | End of 2025 |
| Credit card balance per person with a credit report 8th lowest · End of 2025 | $3,410 U.S. $4,350 | $4,350 | 8th lowest | End of 2025 |
| Homeowners spending 30% or more of income on housing 3rd lowest · 2024* | 16.6% U.S. 22.5% | 22.5% | 3rd lowest | 2024* |
| Share of income from dividends, interest and rent 3rd lowest · 2024 | 16.3% U.S. 21.0% | 21.0% | 3rd lowest | 2024 |
Ranks are among the 50 states and D.C.; each says whether it counts from the highest or the lowest value, and equal printed values share a rank. * Census Bureau five-year survey, 2020 to 2024. Car-loan dollars late and debt per person: Federal Reserve Bank of New York. Mortgages 30 to 89 days late: Consumer Financial Protection Bureau. Every row’s source is listed under Sources and method. Download this table: CSV.
Questions about Indiana
Does Indiana have a good economy?
By jobs, yes: Indiana’s unemployment rate was 3.3% in August 2026, significantly below the U.S. rate of 4.1% (U.S. Bureau of Labor Statistics). Pay is lower than in most states, with a median household income of $71,958 in 2024 (Census Bureau). On our State Distress Index, which also weighs debts and rent, Indiana ranks 26th of the 50 states and D.C. Jobs and unemployment →
What is the poorest county in Indiana?
Delaware County, home to Muncie. Census estimates put 20.5% of its residents below the poverty line in 2024, the top rate among Indiana’s 92 counties (U.S. Census Bureau, Small Area Income and Poverty Estimates). It is also the most distressed county on our County Distress Index. Wayne County (Richmond) and Vigo County (Terre Haute) share the next highest poverty rate, 18.3%. Indiana’s poorest counties →
Is Indiana a cheap state to live in?
For housing, it is cheaper than most. Median rent was $1,062 a month in 2020 to 2024, the 14th lowest among the 50 states and D.C. Homeowners were less likely than in all but two states to spend 30% or more of income on housing (Census Bureau). Incomes are lower too, and we don’t track prices for food or fuel. Cost of living →
What is Indiana’s minimum wage?
$7.25 an hour, the federal minimum (U.S. Department of Labor). Illinois, Michigan and Ohio set higher rates; Kentucky’s is the same as Indiana’s. Indiana’s minimum wage →
Is Indiana a judicial foreclosure state?
Yes. A lender has to file a lawsuit, and a sheriff’s sale follows only after a court judgment. The lender must first send a pre-suit notice by certified mail and, in most cases, wait at least 30 days (Ind. Code § 32-30-10.5-8). How foreclosure works in Indiana →
What is the poverty line in Indiana?
Indiana programs use the federal poverty guideline, one figure for D.C. and the 48 contiguous states. In 2026 it is $15,960 a year for a single person and $33,000 for a household of four (U.S. Department of Health and Human Services). The 12.1% poverty rate on this page is measured against the Census Bureau’s poverty thresholds, a different yardstick.
Cite or reuse Indiana’s data
Quote or reuse any figure on this page; please credit American Default Research.
State Distress Index
Indiana
26thmost distressed state
of the 50 states and D.C.
More distressed than 50% of the other states and D.C.
Indiana is the 26th most distressed of the 50 states and D.C. on American Default Research’s State Distress Index, which measures strain on household finances. Its residents filed for bankruptcy at the 7th highest rate in the country in 2025, 261.1 cases per 100,000 residents, using the 2025 population (Administrative Office of the U.S. Courts). Meanwhile, its unemployment rate was 3.3% in August 2026, against 4.1% nationwide (U.S. Bureau of Labor Statistics). Delaware County, home to Muncie, is the state’s most distressed county, with a County Distress Index score of 85.
Reporters who want an interview or a custom cut of the data can email press@americandefault.org
Sources and method
We gather the data, run the numbers and research each state ourselves.
This edition: October 2026 · Next edition expected March 2027
- Bankruptcy filingsAdministrative Office of the U.S. Courts, Table F-22001 to 2025
- Monthly and yearly unemployment for Indiana, its counties and the nation; significance testU.S. Bureau of Labor Statistics, Local Area Unemployment Statistics and Current Population Survey; state release, Table AJan. 1990 to Aug. 2026
- Poverty and median household income for the state and all its countiesCensus Bureau, Small Area Income and Poverty Estimates1989 to 2024
- Renter households spending half or more of income on rent and utilitiesCensus Bureau, American Community Survey, one-year estimates2005 to 2024
- Rent, homeownership and housing costsCensus Bureau, American Community Survey, five-year estimates2020 to 2024
- PopulationCensus Bureau, population estimates, 2025 release; decennial census counts for Delaware County1900 to 2025
- Late payments and collectionsFederal Reserve Bank of Philadelphia, Consumer Credit Explorerend of 2019 to early 2025
- Household debt and dollars behindFederal Reserve Bank of New York, Consumer Credit Panel / Equifaxend of 2019 and end of 2025
- Personal income per resident and where it comes fromU.S. Bureau of Economic Analysis2024
- SNAPU.S. Department of Agriculture Food and Nutrition Administrationthrough June 2026
- Mortgages 30 to 89 days late; mortgage complaints; medical debts on credit reportsConsumer Financial Protection Bureau: Mortgage Performance Trends; complaint database; Recent changes in medical collections on consumer credit recordsSept. 2025; October 2026; March 2022 to June 2023
- Mortgages with little equityFederal Housing Finance Agency, National Mortgage Databasesecond quarter of 2026
- Cost of getting byMIT Living Wage Calculatorupdated Feb. 15, 2026
- Minimum wagesU.S. Department of Labor, minimum wage rates by stateJuly 1, 2026
- Mortgage help fundU.S. Treasury, Homeowner Assistance Fund; Indiana Foreclosure Prevention Networkthrough early 2026
- Foreclosure lawInd. Code § 32-30-10.5-8 and § 32-29-7-7, as cited in the Indiana Housing and Community Development Authority’s pre-suit notice form and its instructions; 12 CFR 1024.41as of 2026
- Poverty guidelineU.S. Department of Health and Human Services2026
- Housing counselorsU.S. Department of Housing and Urban DevelopmentOctober 2026
- What changed and what to watchIndiana’s family and social services agency, Indiana’s workforce agency, Indiana Utility Regulatory Commission, Indiana Office of Utility Consumer Counselor, Indiana Department of Local Government Finance, U.S. Bureau of Labor Statistics. Each item links the page it was read on (see what changed)June 2025 to Jan. 2027
- PhotoNyttend, via Wikimedia Commons, public domainJan. 7, 2012
Each state’s score draws on four equally weighted parts: unemployment, late payments, collections and bankruptcy, and the share of renters’ income that goes to housing. We average the four for every state and then score each state by the percentage of the other 49 states and D.C. whose average is lower, so a state that scores 80 is more distressed than 80% of them. The full method →
We write with AI tools, and Ross Kilburn checks and reviews every page before it's published.
Get the next Indiana edition by email
One email each time a new Indiana edition is out; the next is expected in March 2027. Unsubscribe anytime.
Thanks, that helps.