Pennsylvania unemployment was 3.7% in August 2026, about the national rate after years above it
Each state is shaded by how distressed its households are, from green (least) to red (most), with data through September 2026. Pennsylvania scores 48 out of 100.
Pennsylvania’s unemployment rate was 3.7% in August 2026, about the national rate after years above it. Philadelphia and Fayette counties and the northeast around Scranton and the Poconos face the most strain. Chester County, west of Philadelphia, is the least distressed.
- Score
- 48/100
- Data through
- September 2026
- Edition
- October 2026
Next edition expected March 2027
How Pennsylvania ranks among the states
At the end of 2019 Pennsylvania was the 11th most distressed state; today it is in the middle, and most of the drop came from jobs. Its yearly unemployment rate was 4.3% in both 2019 and 2025. But the U.S. rate climbed from 3.7% to 4.3%, so Pennsylvania’s rank went from 8th highest among the 50 states and D.C. to tied for 16th highest (U.S. Bureau of Labor Statistics). What keeps the score from falling further is renters’ housing costs, the highest of its four parts (see cost of living).
What drives the score
Each part is a score from 0 to 100 for where Pennsylvania falls among the 50 states and D.C. on the measures inside it. Pennsylvania’s four parts average 51, but the State Distress Index score is a count, not that average: 24 of the other 49 states and D.C. have a lower four-part average, which is 48% of them, so Pennsylvania scores 48. Put another way, a state that scored 80 would be more distressed than 80% of the rest.
- Renters’ housing costs56In 2024, 26.0% of Pennsylvania renter households paid half or more of their income for housing, just under the U.S. share of 26.1% and still tied for 14th highest among the states.
- Late payments58Early in 2025, 13.4% of card borrowers and 7.3% of car-loan borrowers were 90 or more days behind, a little under the national shares; mortgage borrowers, at 1.3%, were a little over.
- Jobs45Unemployment averaged 3.9% over June, July and August 2026, below the U.S. average of 4.1%.
- Collections and bankruptcy45Early in 2025, 12.0% of Pennsylvanians with a credit record had a debt in collections, and in 2025 there were 106.9 bankruptcy filings per 100,000 residents (2025 population); both are under the U.S. figures.
Pennsylvania beside its neighbors
Five of the six states on Pennsylvania’s borders score higher, led by Delaware, one of the most distressed states in the country. Ohio, to the west, is the only neighbor with a lower score.
State Distress Index score, 0 to 100. Among the 50 states and D.C., Delaware ranks 8th for distress, Maryland 16th and Ohio 28th. Unemployment in August 2026 was 3.7% in Pennsylvania, against 4.7% in Delaware and 3.3% in Ohio (U.S. Bureau of Labor Statistics).
Pennsylvania’s score climbed while its jobless rate ranked high among the states, then fell back as other states’ rates rose to meet it
At its worst
In the third quarter of 2019, Pennsylvania scored 82, the 10th most distressed state. It was the only quarter since mid-2006 that Pennsylvania ranked among the 10 most distressed. Its lowest score came at the end of 2010 and the start of 2011: 30, 36th among the states, when its unemployment ran below the nation’s.
The sharpest drop
From the third to the fourth quarter of 2022, the score fell from 68 to 54, which left Pennsylvania 24th. The jobs part, which places Pennsylvania’s unemployment among other states’, went from 94, its highest in the available series, to 74. The renters’ part didn’t move.
Since the chart ends
Our quarterly history runs only to the first quarter of 2025, when Pennsylvania stood 24th with a score of 54. Today it is 27th, at 48. The jobs part slid again, from 65 to 45, while the Census Bureau’s 2025 renter figures moved the renters’ part from 58 to 56. Late payments and collections barely changed. Measured from the end of 2019, the jobs part has fallen from 85 to 45.
Pennsylvania peaked as the 10th most distressed state in 2019 and stood 24th in early 2025
Pennsylvania’s State Distress Index score each quarter, 0 to 100, from the third quarter of 2006, the first with all four parts, to the first quarter of 2025.
How is Pennsylvania’s economy doing? Unemployment is in line with the nation’s
On unemployment, about as well as the country. In August 2026, 3.7% of Pennsylvania’s labor force was out of work, tied for 23rd lowest among the 50 states and D.C., against 4.1% nationwide (U.S. Bureau of Labor Statistics); by the bureau’s test, that difference isn’t statistically significant. A year earlier the rate was 4.4%, a fall the bureau does count as significant. For the full year 2025, Pennsylvania’s rate matched the nation’s at 4.3%, after running above it every year from 2015 through 2023.
Filing a claim for unemployment benefits? That goes through the Pennsylvania labor department’s unemployment site →
Unemployment rate
3.7%
U.S. 4.1%
Tied for 23rd lowest of the states and D.C. for August 2026
Yearly average unemployment rate
4.3%
U.S. 4.3%
2025, U.S. Bureau of Labor Statistics
Highest county rate, Cameron County
5.8%
August 2026, not adjusted for seasonal swings
Pennsylvania’s unemployment rate ran above the nation’s every year from 2015 to 2023; in 2025 the two were equal
Share of the labor force out of work and looking, Pennsylvania and the U.S., seasonally adjusted, monthly from January 1990 through August 2026; there is no October 2025 point because the shutdown halted that month’s survey. The yearly comparison in the headline uses the bureau’s yearly averages.
Between 2019 and 2025 Pennsylvania’s yearly rate ended where it started while the nation’s rose to meet it, so a rate that once ranked high among the states became an ordinary one (see how it ranks). In 2024 Pennsylvania’s yearly average, 3.8%, was below the nation’s 4.0%.
Unemployment is highest in Cameron County and lowest in Centre County
| County | Rate |
|---|---|
| Cameron (Emporium) | 5.8% |
| Forest (Tionesta) | 5.3% |
| Philadelphia | 5.2% |
| Fayette (Uniontown) | 5.2% |
| Luzerne (Wilkes-Barre) | 5.2% |
| Allegheny (Pittsburgh) | 3.8% |
| Centre (Bellefonte) | 3.0% |
Unemployment rate, August 2026, not adjusted for seasonal swings: the five highest of Pennsylvania’s 67 counties (Philadelphia, Fayette and Luzerne share a rate), Allegheny for the Pittsburgh area, and Centre, the lowest, with county seats in parentheses. Source: U.S. Bureau of Labor Statistics.
Pennsylvania’s minimum wage is lower than in every state on its borders
Pennsylvania’s minimum wage is $7.25 an hour, the federal minimum. Every neighboring state sets a higher one for most workers, the U.S. Department of Labor’s table shows. A bill to raise Pennsylvania’s to $15 by 2029 passed the state House in March 2026 and hasn’t come to a vote in the Senate (see what to watch).
| State | Minimum wage, an hour |
|---|---|
| New York | $16.00 to $17.00 |
| New Jersey | $15.92 |
| Maryland | $15.00 |
| Delaware | $15.00 |
| Ohio | $11.00 |
| West Virginia | $8.75 |
| Pennsylvania | $7.25 |
State minimum wages in effect July 1, 2026. New York’s higher rate is for New York City, Long Island and Westchester. Ohio’s applies to employers with yearly gross receipts of $405,000 or more (smaller ones pay $7.25), and West Virginia’s to employers with six or more workers at one place. Source: U.S. Department of Labor. The poorest and most distressed counties →
Which Pennsylvania counties are poorest, and which are most distressed?
Forest County, a small, wooded county in the northwest, is the poorest in Pennsylvania: in 2024, 22.8% of its people were below the poverty line, the highest rate of the state’s 67 counties, the Census Bureau estimates. Philadelphia County shares its borders and government with the City of Philadelphia. It has the second-highest poverty rate, 19.7%, and is the most distressed county on our County Distress Index. The index measures strained household budgets in every U.S. county; Philadelphia scores 91. No Pennsylvania county ranks among the 100 most distressed in the country (see the national list). Chester County, west of Philadelphia, is the least distressed, at 3.
Philadelphia, the northeast and the southwest corner are Pennsylvania’s most distressed areas; Chester County and the suburbs north of Philadelphia are among the least
County Distress Index scores, 0 to 100, for the 67 Pennsylvania counties; data runs through August 2026.
Loading the county map…
The county map could not be loaded. Every county is in the lists on this page.
Most distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 1 | Philadelphia | 91 | 19.7% |
| 2 | Fayette | 86 | 14.7% |
| 3 | Monroe | 79 | 10.8% |
| 4 | Luzerne | 72 | 13.4% |
| 5 | Greene | 66 | 17.7% |
| 6 | Carbon | 63 | 11.3% |
| 7 | Lackawanna | 63 | 14.9% |
| 8 | Pike | 60 | 9.9% |
| 9 | Lawrence | 59 | 14.3% |
| 10 | Lehigh | 58 | 11.1% |
Least distressed
| Rank | County | Score | Poverty |
|---|---|---|---|
| 63 | Bucks | 12 | 6.1% |
| 64 | Union | 11 | 10.8% |
| 65 | Montgomery | 9 | 6.2% |
| 66 | Butler | 9 | 7.9% |
| 67 | Chester | 3 | 6.4% |
Rank in Pennsylvania, 1 = most distressed. Ranks come from unrounded scores, so two counties that show the same score can rank apart. Poverty is each county’s 2024 Census Bureau rate.
Every county, by score
Only 2 of Pennsylvania’s 67 counties score 80 or more: Philadelphia and Fayette, which together are home to 12.9% of the state’s people. Most counties fall between 30 and 70. Of the 8 counties that score 60 or more, 5 are in the northeast.
2 score 80–100
18 score 50–69
Greene, Carbon, Lackawanna, Pike, Lawrence, Lehigh, Crawford, Dauphin, McKean, Mercer, Erie, Berks, Lycoming, Schuylkill, Cambria, Venango, Indiana, Cameron
27 score 30–49
Delaware, Wayne, Northumberland, Clearfield, Beaver, Forest, Clinton, Columbia, Potter, Blair, Susquehanna, Northampton, Armstrong, Bedford, Clarion, Bradford, Jefferson, Lebanon, Tioga, Allegheny, Mifflin, Westmoreland, Wyoming, Franklin, Somerset, Washington, Warren
In Pennsylvania, the poorest county is far from the most distressed
Our County Distress Index weighs five parts equally: late payments; collections and bankruptcy; jobs; renters’ housing costs; and a fifth built from the poverty rate, child poverty, median household income, disability and the share without health insurance. Poverty is one input among many, so the two lists split. Forest County, whose seat is Tionesta, has the state’s highest poverty rate and its lowest median household income, $55,213, yet ranks 28th of 67 on distress, with late-payment and collections scores among the lowest in the state. Centre County, home to Bellefonte and State College, has a poverty rate of 14.3%, tied for 13th highest in the state, but ranks 57th; its renters’ costs score high and its late payments and collections low. Monroe County, in the Poconos, runs the other way: its poverty rate, 10.8%, is tied for 24th lowest, yet it is the 3rd most distressed, with late-payment and collections scores among the highest in the state. Pike County, next door, is similar: 16th lowest on poverty, 8th on distress. Another site that uses a different Census survey or year may name a different poorest county; these rates are the Census Bureau’s 2024 Small Area Income and Poverty Estimates.
The five poorest counties
| County | Poverty | Distress rank |
|---|---|---|
| Forest | 22.8% | 28th |
| Philadelphia | 19.7% | 1st |
| Greene | 17.7% | 5th |
| Crawford | 16.8% | 11th |
| Indiana | 16.0% | 21st |
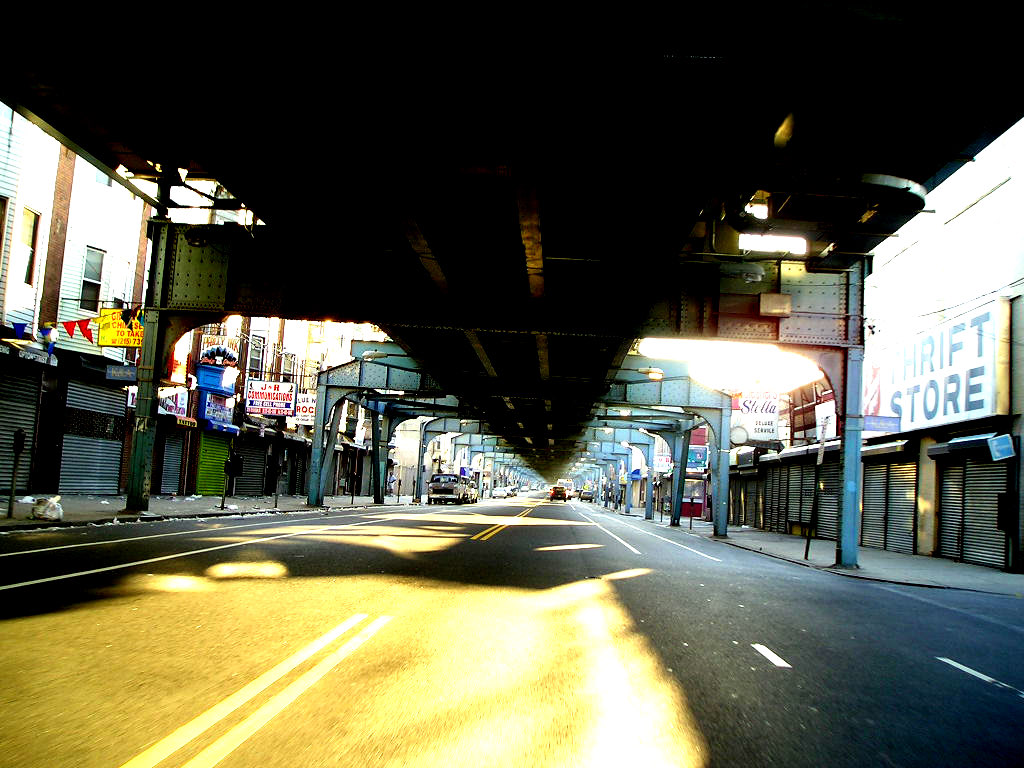
Kensington Avenue under the Market-Frankford elevated line in Philadelphia. Philadelphia County, the most distressed in Pennsylvania at 91, counted 1,603,797 residents in the 2020 Census, 77% of its 1950 peak of 2,071,605 (Census Bureau; the percentage is our calculation).
Source: U.S. Census Bureau. Photo: Dasprevailz, Wikimedia Commons, public domain.

Philadelphia, its suburbs, Pittsburgh and the northeast
We grouped the counties to show where strain sits once each county is weighted by its population, so a big county counts for more people than a small one. Philadelphia County, with 12.0% of the state’s residents, scores 91. Its four suburban counties, Bucks, Chester, Delaware and Montgomery, hold 20.4% of residents and average 17, the lowest of any group. The northeast, from the Lehigh Valley through the Poconos to Scranton and Wilkes-Barre, holds 12.7% and averages 59, second only to Philadelphia; 5 of its 10 counties score 60 or more. Allegheny County, home to Pittsburgh, scores 34, and the six counties around it, Armstrong, Beaver, Butler, Fayette, Washington and Westmoreland, average 36, with Fayette the only one above 60. South central Pennsylvania, from Harrisburg and Lancaster to York and Reading, averages 33, and the other 36 counties, across the center, the northern tier and the northwest, 43. The scores show where strain sits, not why.
American Default Research, County Distress Index; county populations from the index’s Census figures. The groups and their averages are ours.
Is Pennsylvania expensive to live in? Rent is below the U.S. median
For housing, less than the country as a whole. Half of Pennsylvania’s renters paid less than $1,209 a month in the Census Bureau’s 2020 to 2024 survey, 24th lowest among the 50 states and D.C., against a U.S. median of $1,413. A year of that rent came to 18.7% of the typical household’s income in 2024, against 20.8% for the U.S. (our calculation). We don’t hold prices for groceries, gas or power, and we have no city figures for Philadelphia or Pittsburgh, so this page can’t rank Pennsylvania’s full cost of living.
Median rent, a month
$1,209
U.S. $1,413
24th lowest of the states and D.C. for 2020 to 2024
Renters spending at least 30% of income on housing
44.6%
U.S. 47.6%
24th lowest of the states and D.C. for 2020 to 2024
Homeowners spending at least 30% of income on housing
19.6%
U.S. 22.5%
21st lowest of the states and D.C. for 2020 to 2024
Even so, renters’ housing costs are the part of our score where Pennsylvania ranks highest. In 2024, 26.0% of its renter households paid half or more of their income for rent and utilities. That was just below 26.1% nationally but tied for 14th highest among states, because most states have a smaller share than the nation as a whole. Pennsylvania’s share rose each year from 2019 to 2024 in the Census figures published.
The share of Pennsylvania renters spending half their income on housing has stayed within two points of the U.S. share since 2005
Share of renter households whose rent and utilities take half or more of their income, Pennsylvania and the U.S., from the Census Bureau’s one-year surveys, 2005 to 2024 (none was published for 2020).
What MIT estimates a bare-bones Pennsylvania budget costs
The MIT Living Wage Calculator puts yearly basic costs for one adult with no children in Pennsylvania at $48,515 before taxes. That is 25th lowest among the 50 states and D.C. For two working parents with two children, it estimates $123,964 (2025 dollars). These are MIT’s estimates of necessities, with no savings.
Electric bills for PPL’s customers rose from July 1, 2026 (see what changed). Older Pennsylvanians, widows and widowers, and people with disabilities with household income of $48,110 or less can claim a Property Tax/Rent Rebate of $380 to $1,000 from the state revenue department.
Rent costs less in Pennsylvania than in four of its six neighbors
Only Ohio and West Virginia have a lower median rent. Measured against income, rent takes a smaller share in Pennsylvania than in New York, New Jersey, Maryland or Delaware.
| State | Rent, a month | Median household income | Rent as share of income |
|---|---|---|---|
| New Jersey Rent as share of income 19.8% | $1,720 Median household income $104,202 | $104,202 | 19.8% |
| Maryland Rent as share of income 19.9% | $1,705 Median household income $102,835 | $102,835 | 19.9% |
| New York Rent as share of income 22.7% | $1,621 Median household income $85,768 | $85,768 | 22.7% |
| Delaware Rent as share of income 19.2% | $1,401 Median household income $87,510 | $87,510 | 19.2% |
| Pennsylvania Rent as share of income 18.7% | $1,209 Median household income $77,532 | $77,532 | 18.7% |
| Ohio Rent as share of income 17.2% | $1,034 Median household income $72,259 | $72,259 | 17.2% |
| West Virginia Rent as share of income 17.2% | $872 Median household income $60,662 | $60,662 | 17.2% |
Rent: median gross rent a month, 2020 to 2024 (Census Bureau, American Community Survey). Income: median household income, 2024 (Census Bureau, Small Area Income and Poverty Estimates). Rent as share of income is ours: twelve months of median rent over median household income. Rent and housing costs by state →
What changed in Pennsylvania in the past year
-
July 1, 2026
PPL Electric’s higher rates took effect
On June 4, Pennsylvania’s Public Utility Commission approved a settlement letting PPL Electric raise its yearly revenue by about $275 million, less than the company asked for. For a home using 918 kilowatt-hours a month, the commission projected the total bill would go from $177.01 to about $184.49 a month. PPL filed its new rates on June 30, and the commission confirmed on July 7 that they took effect on July 1. PPL serves eastern and central Pennsylvania.
Pennsylvania Public Utility Commission, June 4, 2026; Pennsylvania Public Utility Commission, July 7, 2026
-
March 24, 2026
The state House passed a higher minimum wage; the Senate hasn’t voted
House Bill 2189 would raise Pennsylvania’s minimum wage from $7.25 to $11 on Jan. 1, 2027, and in steps to $15 in 2029, with yearly adjustments after that. The House passed it on March 24 and the Senate sent it to its labor committee on March 30. A resolution to pull it out of committee was presented on Sept. 30, its latest action; the bill was still in committee as of Oct. 16 (see the minimum wage).
-
Feb. 9, 2026
Pennie customers faced much higher premiums, and many dropped coverage
Pennie, Pennsylvania’s health insurance marketplace, said about 486,000 people signed up for 2026. With the extra federal premium tax credits gone, people faced an average increase of 102% to keep the same plan, and Pennie estimated that about 85,000 dropped coverage. These are Pennie’s figures.
-
Nov. 14, 2025
November SNAP benefits went out in full after the federal shutdown
November’s SNAP payments, the federal food benefit, were delayed while the federal government was shut down. Once the shutdown ended, Pennsylvania’s human services department issued more than $276 million in benefits on Nov. 13 alone and said on Nov. 14 that full November payments had gone out.
-
Nov. 12, 2025
A state budget more than four months late, with a new tax credit for working families
On Nov. 12, the governor signed the budget for the year that began July 1, 2025. The governor’s office put it at $50.1 billion. It created the Working Pennsylvanians Tax Credit, worth 10% of the federal Earned Income Tax Credit and up to $805; anyone who qualifies for the federal credit qualifies, starting with the 2026 tax season, the state revenue department says.
Office of the Governor, Nov. 12, 2025; Pennsylvania Department of Revenue
-
Sept. 1 to Nov. 1, 2025
Federal SNAP rule changes reached Pennsylvania
Under the 2025 federal budget law, Pennsylvania’s waivers from SNAP’s work requirement ended on Sept. 1, which the human services department says affected about 132,000 people. From Oct. 27, only households with an older or disabled member could get the larger heating and utility allowance, which cut benefits for about 72,000 households. From Nov. 1, the work rule covered adults up to 64 and parents whose youngest child is 14 or older, and fewer noncitizens qualified (see SNAP).
Pennsylvania Department of Human Services, briefing, Aug. 26, 2026
Is Pennsylvania a poor state? It sits in the middle on poverty and income
No, but it isn’t rich either. In 2024, 11.6% of Pennsylvanians lived below the poverty line, 26th highest among the 50 states and D.C. and a little under the U.S. rate of 12.1%. The typical household earned $77,532, 23rd lowest, against $81,604 nationwide (Census Bureau, Small Area Income and Poverty Estimates). Income per person, every dollar residents received divided by the number of residents, was $70,678, 23rd highest (U.S. Bureau of Economic Analysis).
Residents in poverty
11.6%
U.S. 12.1%
26th highest of the states and D.C. for 2024
Children in poverty
15.3%
U.S. 15.5%
Tied for 22nd highest of the states and D.C. for 2024
Median household income
$77,532
U.S. $81,604
23rd lowest of the states and D.C. for 2024
Every Census estimate since 1989 puts Pennsylvania’s poverty rate under the U.S. rate
Pennsylvanians and Americans living below the poverty line, in percent, from 1989 to 2024. No state estimates exist for 1990 through 1992 or for 1994.
An older state, where deaths outnumber births
From 2020 to 2024, 19.5% of Pennsylvanians were 65 or older, 9th highest among the states, against 17.2% nationwide (Census Bureau, American Community Survey). Government benefits such as Social Security, Medicare and Medicaid made up 20.6% of the income residents received in 2024, 18th highest, against 18.3% for the U.S. (Bureau of Economic Analysis).
Deaths outnumbered births in Pennsylvania in every year from 2021 through 2025, by 81,866 in all, and more people moved out to other states than moved in from them, a net loss of 50,746. The state still grew, by 0.5% from 2020 to 2025, 10th lowest among the states, because 196,095 more people arrived from abroad than left (Census Bureau population estimates; the five-year totals are our sums). These figures describe who lives here; we found no source tying them to the state’s distress.
Why another site may show a different poverty rate
Some sites quote the Census Bureau’s American Community Survey, which gives Pennsylvania a slightly different poverty rate and income. We use the Small Area Income and Poverty Estimates, which the bureau makes each year for every state and county, so the state and county rates on this page share one source. Programs that check eligibility use a separate yardstick, the federal poverty guideline, covered in the questions below.
Chester is the richest county, and the least distressed
By median household income, Chester County was the richest in Pennsylvania in 2024, at $130,877, followed by Bucks, at $112,331, and Montgomery, at $111,915 (Census Bureau). All three are Philadelphia suburbs, and all three are among the five least distressed counties. Philadelphia County’s typical household earned $60,500. The poorest and most distressed counties →
SNAP in Pennsylvania: more residents get food help than in most states, and the count is falling
In June 2026, 1,714,398 Pennsylvanians got SNAP, the federal food benefit once called food stamps, the U.S. Department of Agriculture reports. That is 13.1% of the state’s 2025 population, tied for 8th highest among the 50 states and D.C., against 10.6% nationwide, a high share for a state in the middle on poverty. A year earlier, in June 2025, the count was 1,941,067, so it dropped by 226,669 in a year, or 11.7%.
To apply for SNAP or check on a case, use the state’s COMPASS site →
People getting SNAP
1,714,398
June 2026, U.S. Department of Agriculture
Share of residents getting SNAP
13.1%
U.S. 10.6%
Tied for 8th highest of the states and D.C. for June 2026 (2025 population)
Change from a year earlier
−11.7%
June 2025 to June 2026
The slide started before the new federal rules. Pennsylvania’s count peaked at 2,024,539 in August 2024 and had already fallen by 102,729 a year later, before the first rule change took effect on Sept. 1, 2025. It then fell another 207,412 by June 2026, below its average before the pandemic, 1,733,275 (U.S. Department of Agriculture; the differences are our calculation). Pennsylvania’s human services department counts about 89,000 people who lost SNAP because of the 2025 federal law between Sept. 1, 2025, and late August 2026. That is less than half of the drop since August 2025, and we found no source that explains the rest.
The rules behind Pennsylvania’s smaller SNAP count
The 2025 federal budget law ended Pennsylvania’s waivers from SNAP’s work requirement. It limited the larger heating and utility allowance to households with an older or disabled member. It also widened the work rule to adults up to 64 and parents of children 14 and older, and narrowed which noncitizens qualify. The dates are in what changed. A smaller count is not proof of less need: the latest Census poverty figures are for 2024, before the changes. Is Pennsylvania poor? →
Are Pennsylvanians behind on their bills? A little less often than Americans overall
Slightly less than the country. In early 2025, 16.2% of Pennsylvanians with a credit record had a debt 90 or more days late, 24th highest among the 50 states and D.C., against 17.2% nationally, our population-weighted average of the states (Federal Reserve Bank of Philadelphia). Mortgages are the exception: Pennsylvania homeowners are a little more likely than homeowners nationwide to be behind. All of this is household borrowing; the state government’s own debt isn’t part of it.
Ranked from the largest share among the 50 states and D.C., Pennsylvania is 22nd on cards, 25th on collections, tied for 26th on car loans and tied for 14th on mortgages. We built each U.S. bar from the states’ figures, with bigger states counting for more.
Falling far behind on cards is more common than it was. The share of Pennsylvania card borrowers 90 or more days late rose from 9.4% at the end of 2019 to 13.4% in early 2025. Collections fell over the same years, from 17.3% to a low of 10.7% in mid-2023, and have edged up since. Most of that fall came before 2022: the share was down to 13.6% by early that year. The rest came from early 2022 to mid-2023, while the three big credit bureaus were dropping many medical debts from credit reports, and a debt left off a report hasn’t necessarily been paid. Across the country, the share of people with a medical collection on their report went from about 14% in March 2022 to about 5% in June 2023 (Consumer Financial Protection Bureau).
Counted in dollars, Pennsylvania card balances are as far behind as the nation’s
The Federal Reserve Bank of New York counts the share of dollars owed that is 90 or more days late, not the share of people. At the end of 2025, 12.3% of Pennsylvania credit card balances were that far behind, 15th highest among the 50 states and D.C., about level with the U.S. share of 12.4% and up from 8.0% at the end of 2019. Mortgage dollars ran a little above the U.S. share.
| Loan type | Pennsylvania | U.S. | Pennsylvania 2019 | U.S. 2019 |
|---|---|---|---|---|
| Credit card | 12.3% End of 2025 U.S. 12.4% Pennsylvania 2019 8.0% · U.S. 2019 8.1% | 12.4% | 8.0% | 8.1% |
| Auto loan | 4.8% End of 2025 U.S. 5.2% Pennsylvania 2019 4.4% · U.S. 2019 4.9% | 5.2% | 4.4% | 4.9% |
| Mortgage | 1.1% End of 2025 U.S. 0.9% Pennsylvania 2019 1.1% · U.S. 2019 1.0% | 0.9% | 1.1% | 1.0% |
Share of balances 90 or more days past due, end of 2025 and end of 2019. Source: Federal Reserve Bank of New York, Consumer Credit Panel / Equifax. Because it counts dollars, not people, it can’t be set beside the Philadelphia Fed chart above, and it keeps old debts that lenders have written off but still report.
Early mortgage trouble is a little more common here
In September 2025, 1.9% of Pennsylvania mortgages were 30 to 89 days late, tied for 14th highest among the 50 states and D.C., against 1.6% nationwide (Consumer Financial Protection Bureau). Few owners are close to owing more than their home is worth: 2.6% of mortgages had less than 10% equity in the second quarter of 2026, against 4.7% for the U.S. (Federal Housing Finance Agency).
| Measure | Pennsylvania | U.S. | Rank |
|---|---|---|---|
| Household debt per person with a credit report, end of 2025 17th lowest | $50,360 U.S. $63,200 | $63,200 | 17th lowest |
| Card balances per person with a credit report, end of 2025 23rd lowest | $3,950 U.S. $4,350 | $4,350 | 23rd lowest |
Rank among the 50 states and D.C. Debt per person adds up every kind of household debt: Federal Reserve Bank of New York. Late payments in every state →
Bankruptcy in Pennsylvania: fewer filings per person than in most states in 2025, but more of them under Chapter 13
Pennsylvanians filed 13,965 bankruptcy cases in 2025, or 106.9 for every 100,000 residents (2025 population), 18th lowest among the 50 states and D.C., against 166.3 nationwide (Administrative Office of the U.S. Courts). Filings rose 10.3% from 2024, a little less than the 11.1% rise nationwide. They have risen every year since 2022, and 2025 brought the most since 2020, when Pennsylvanians filed 14,120.
Chapter 13 accounts for an unusually large share of Pennsylvania’s cases, 44.1% in 2025, 11th highest among the states, against 35.9% nationally. In a Chapter 13 case, filers usually keep their property and pay back part of their debts under a court-approved plan lasting three to five years. In Chapter 7, the more common kind, many debts are wiped out and property the law doesn’t protect can be sold.
| Year | Filings |
|---|---|
| 2005 | 78,943 |
| 2010 | 39,262 |
| 2019 | 21,220 |
| 2020 | 14,120 |
| 2021 | 10,382 |
| 2022 | 9,826 |
| 2023 | 11,027 |
| 2024 | 12,666 |
| 2025 | 13,965 |
Cases under every chapter filed in Pennsylvania’s three federal bankruptcy courts, the Eastern, Middle and Western districts, in selected years and every year since 2019. 2005 is the highest in the available series, which cover 2001 to 2025 except 2004; filings spiked that year before a stricter federal bankruptcy law took effect in October. Source: Administrative Office of the U.S. Courts, Table F-2. Bankruptcy filings in every state →
How foreclosure works in Pennsylvania
Every home foreclosure in Pennsylvania goes through a court, the county Court of Common Pleas, and ends, if the owner doesn’t catch up or settle, with a sheriff’s sale. At least 30 days before filing, the lender must mail a notice of intent to foreclose. For most owner-occupied one- and two-family homes, this is the Act 91 notice, which also tells the owner about state mortgage help. Otherwise, it is the Act 6 notice (41 P.S. § 403; 35 P.S. § 1680.403c). Once served with the complaint, the owner ordinarily has 20 days to respond (Pa. R.C.P. No. 1026), and notice of the sheriff’s sale must be served at least 30 days before it (Pa. R.C.P. No. 3129.2).
Up to one hour before bidding starts at the sheriff’s sale, the owner can stop the foreclosure by paying what is overdue plus allowed fees and costs. The owner need not pay the whole loan and can use this right as many as three times in a calendar year (41 P.S. § 404). After the sale there is no right to buy the home back. To collect any balance the sale didn’t cover, the lender must ask the court to set the home’s fair market value within six months after the sheriff’s deed is delivered (42 Pa.C.S. §§ 8103, 5522). Federal mortgage servicing rules generally bar a lender from starting foreclosure on a primary home before the loan is more than 120 days behind.
The state’s Homeowners’ Emergency Mortgage Assistance Program, run by the Pennsylvania Housing Finance Agency, lends qualifying owners up to $60,000 to cover missed and upcoming payments, a loan that must be repaid. In Philadelphia, owner-occupied foreclosure cases are scheduled for a conference with the lender under the court’s Residential Mortgage Foreclosure Diversion Program. In Allegheny County, owners facing a filed foreclosure can join the court’s Save Your Home program by calling its hotline, 866-298-8020. The statewide foreclosure rules have no mediation step, so help like this depends on the county.
- Goes through a court
- Always
- Notice before the case is filed
- 30 days
- Time to answer the complaint
- 20 days
- Notice before the sheriff’s sale
- 30 days
- Catch up and keep the home
- Until an hour before bidding
- Buy-back right after the sale
- None
These rules describe foreclosure for a home you live in. Sources include Act 6 of 1974 (41 P.S. §§ 403–404) and the Housing Finance Agency Law as amended by Act 91 of 1983 (35 P.S. § 1680.403c). Other sources are Pennsylvania Rules of Civil Procedure 1026 and 3129.2; 42 Pa.C.S. §§ 8103 and 5522; and federal rule 12 CFR 1024.41. How foreclosure works in Pennsylvania →
Pennsylvania was awarded $350.4 million from the federal Homeowner Assistance Fund and had helped 22,597 households with it through early 2026 (U.S. Treasury). The state’s program, the Pennsylvania Homeowner Assistance Fund, no longer takes new applications (Pennsylvania Housing Finance Agency).
Pennsylvania mortgage complaints: what homeowners report to the CFPB
Since 2012 the Consumer Financial Protection Bureau has logged 16,039 mortgage complaints from Pennsylvania. Problems with making payments top the list, at 4,279 complaints, followed by loan modifications, collection and foreclosure (3,253) and servicing, payment and escrow trouble (3,041).
- Oct. 3, 2026 PennyMac Struggling to pay: trouble reaching the company about a modification, forbearance or foreclosure Closed with explanation
- Oct. 3, 2026 Ocwen / Onity Group Payment process: fees charged Closed with explanation
- Oct. 2, 2026 Selene Finance Payment process: trouble reaching the company to fix a problem with the loan Closed with explanation
- Oct. 2, 2026 M&T Bank Payment process: fees charged Closed with explanation
- Oct. 2, 2026 Provident Funding Associates Payment process: trouble reaching the company to fix a problem with the loan Closed with explanation
- Oct. 2, 2026 PennyMac Payment process: escrow, taxes or insurance Closed with explanation
- Oct. 1, 2026 PennyMac Struggling to pay: trouble reaching the company about a modification, forbearance or foreclosure Closed with explanation
- Sept. 30, 2026 Northwest Bancshares Inc Struggling to pay: an existing modification, forbearance or other relief Closed with explanation
- Sept. 30, 2026 Ocwen / Onity Group Struggling to pay: trouble reaching the company about a modification, forbearance or foreclosure Closed with explanation
- Sept. 30, 2026 Northwest Bancshares Inc Struggling to pay: trouble reaching the company about a modification, forbearance or foreclosure Closed with explanation
The 10 newest Pennsylvania complaints about paying a mortgage or getting help with one, newest first, from the Consumer Financial Protection Bureau’s public complaint database as of Oct. 14, 2026. We leave out complaints about taking out a new loan and any that name a credit bureau. Each complaint is one person’s account, which the bureau doesn’t verify, and a complaint doesn’t show that the company did anything wrong. Every Pennsylvania mortgage complaint at the Consumer Financial Protection Bureau →
What to watch before the next edition
Four things to watch before the next edition are listed nearest first. They are a jobs report, the last day to apply for a property tax or rent rebate, the start of a Medicaid work rule and the first step for a stalled minimum wage bill.
-
Oct. 20, 2026
September unemployment rates for the states
The Bureau of Labor Statistics is scheduled to publish state unemployment rates for September. Pennsylvania’s August rate, 3.7%, was down from 4.4% a year earlier, a drop the bureau counts as statistically significant.
Bureau of Labor Statistics, State Employment and Unemployment, August 2026 release
-
Dec. 31, 2026
Last day to apply for a property tax or rent rebate
Older Pennsylvanians and people with disabilities whose incomes qualify have until Dec. 31 to apply for a rebate on the property taxes or rent they paid in 2025; the state revenue department extended the deadline in May.
-
Jan. 1, 2027
Medicaid work rule and six-month renewals for expansion adults
Adults 19 to 64 covered through Medicaid’s expansion will have to show 80 hours a month of work or other activity, or household income of at least $580 a month, unless exempt, and those renewing from February 2027 will renew every six months, Pennsylvania’s human services department says. It counts about 800,000 adults in the expansion group.
Pennsylvania Department of Human Services, briefing, Aug. 26, 2026
-
Jan. 1, 2027
The first step of the minimum wage bill, if it passes
House Bill 2189 would lift the minimum wage to $11 on this date only if the Senate passes it and the governor signs it before then. It was still in the Senate’s labor committee as of Oct. 16; the latest action, on Sept. 30, was a resolution to pull it out.
Where Pennsylvania ranks highest and lowest
| Measure | Pennsylvania | U.S. | Rank | Latest data |
|---|---|---|---|---|
| Residents getting SNAP food benefits (2025 population) Tied for 8th highest · June 2026 | 13.1% U.S. 10.6% | 10.6% | Tied for 8th highest | June 2026 |
| Residents 65 and older 9th highest · 2024* | 19.5% U.S. 17.2% | 17.2% | 9th highest | 2024* |
| Share of bankruptcy filings under Chapter 13 11th highest · 2025 | 44.1% U.S. 35.9% | 35.9% | 11th highest | 2025 |
| Renters spending at least half their income on housing Tied for 14th highest · 2024 | 26.0% U.S. 26.1% | 26.1% | Tied for 14th highest | 2024 |
| Mortgages 30 to 89 days late Tied for 14th highest · Sept. 2025 | 1.9% U.S. 1.6% | 1.6% | Tied for 14th highest | Sept. 2025 |
| Credit card dollars 90+ days late 15th highest · End of 2025 | 12.3% U.S. 12.4% | 12.4% | 15th highest | End of 2025 |
| Income from government benefits, share of all income 18th highest · 2024 | 20.6% U.S. 18.3% | 18.3% | 18th highest | 2024 |
| Card borrowers 90+ days late 22nd highest · Early 2025 | 13.4% U.S. 13.5% | 13.5% | 22nd highest | Early 2025 |
| Income per person 23rd highest · 2024 | $70,678 U.S. $73,204 | $73,204 | 23rd highest | 2024 |
| Residents in poverty 26th highest · 2024 | 11.6% U.S. 12.1% | 12.1% | 26th highest | 2024 |
| Unemployment rate, three-month average Tied for 24th lowest · June–August 2026 | 3.9% U.S. 4.1% | 4.1% | Tied for 24th lowest | June–August 2026 |
| Median household income 23rd lowest · 2024 | $77,532 U.S. $81,604 | $81,604 | 23rd lowest | 2024 |
| Bankruptcy filings per 100,000 residents (2025 population) 18th lowest · 2025 | 106.9 U.S. 166.3 | 166.3 | 18th lowest | 2025 |
| Household debt per person with a credit report 17th lowest · End of 2025 | $50,360 U.S. $63,200 | $63,200 | 17th lowest | End of 2025 |
| Residents without health insurance 13th lowest · 2024* | 5.6% U.S. 8.4% | 8.4% | 13th lowest | 2024* |
Ranks run across the 50 states and D.C., from the top or the bottom as each row says, and a printed value shared by two or more states shares its rank. * Census five-year survey, 2020 to 2024. Card borrowers count people with a credit record (Federal Reserve Bank of Philadelphia), with a U.S. figure that is our population-weighted average of the states. Card dollars late and debt per person: Federal Reserve Bank of New York. Sources and method names each row’s source. Download this table: CSV.
Questions about Pennsylvania
Does Pennsylvania have a good economy?
On jobs, it is about average now. Its unemployment rate was 3.7% in August 2026, against 4.1% for the U.S., and down from 4.4% a year earlier (U.S. Bureau of Labor Statistics). Its yearly rate matched the nation’s in 2025, after running above it every year from 2015 through 2023. On our State Distress Index it ranks 27th of the 50 states and D.C. Jobs and unemployment →
What is the poorest county in Pennsylvania?
Forest County, in the northwest, whose seat is Tionesta: 22.8% of its residents lived in poverty in 2024, the highest rate of Pennsylvania’s 67 counties. Its median household income, $55,213, was the lowest (U.S. Census Bureau, Small Area Income and Poverty Estimates). Philadelphia County has the second-highest poverty rate and is the most distressed on our County Distress Index. The poorest and most distressed counties →
Is Pennsylvania a cheap state to live in?
Housing costs less than in the country overall. The typical rent was $1,209 a month over 2020 to 2024, below the U.S. median of $1,413 (U.S. Census Bureau), and the MIT Living Wage Calculator puts a basic budget for one adult at $48,515 a year. We don’t hold prices for food, gas or electricity, so we can’t rank the full cost of living.
What is Pennsylvania’s minimum wage?
$7.25 an hour, the federal minimum; every neighboring state sets a higher one for most workers (U.S. Department of Labor). House Bill 2189, which would raise it in steps to $15 by 2029, passed the state House in March 2026 and was in a Senate committee as of Oct. 16. The minimum wage beside its neighbors →
What is the poverty line in Pennsylvania?
Pennsylvania programs use the federal poverty guideline, which is the same in D.C. and the 48 contiguous states. The 2026 guideline is $15,960 a year for a single person and $33,000 for a family of four (U.S. Department of Health and Human Services). The 11.6% poverty rate on this page comes from the Census Bureau’s poverty thresholds, a separate measure.
Is Pennsylvania a judicial foreclosure state?
Yes. Every home foreclosure goes through the county Court of Common Pleas and ends in a sheriff’s sale, and the lender must send a notice at least 30 days before filing (41 P.S. § 403). How foreclosure works in Pennsylvania →
Cite or reuse Pennsylvania’s data
Anyone may quote or reuse these figures with credit to American Default Research.
State Distress Index
Pennsylvania
27thmost distressed state
of the 50 states and D.C.
More distressed than 48% of the other states and D.C.
Pennsylvania is the 27th most distressed of the 50 states and D.C. on American Default Research’s State Distress Index, a measure of strain on household finances, down from 10th in the third quarter of 2019. Its unemployment rate averaged 4.3% in 2025, level with the nation’s, after running above it every year from 2015 through 2023 (U.S. Bureau of Labor Statistics). In 2024, the Census Bureau put its poverty rate at 11.6%, against 12.1% nationally. Philadelphia County is the state’s most distressed county, with a County Distress Index score of 91.
For an interview or a custom cut of the data, reporters can write to press@americandefault.org
Sources and method
We gather the data, run the numbers and research each state ourselves.
This edition: October 2026 · Next edition expected March 2027
- Jobless rates: monthly and yearly, for the state, its counties and the U.S.U.S. Bureau of Labor Statistics, Local Area Unemployment Statistics and Current Population SurveyJan. 1990 to Aug. 2026
- Poverty rates and median household income, statewide and by countyCensus Bureau, Small Area Income and Poverty Estimates1989 to 2024
- Renters whose rent and utilities take half their income or moreCensus Bureau, American Community Survey, one-year estimates2005 to 2024
- Rent, housing costs, age and health insuranceCensus Bureau, American Community Survey, five-year estimates2020 to 2024
- Population, births, deaths and movesCensus Bureau, population estimates, 2025 release2020 to 2025
- Philadelphia County population by censusCensus Bureau, decennial census1950 and 2020
- Income per person and benefit incomeU.S. Bureau of Economic Analysis2024
- Late payments and collectionsFederal Reserve Bank of Philadelphia, Consumer Credit Explorerend of 2019 to early 2025
- Household debt and dollars behindFederal Reserve Bank of New York, Consumer Credit Panel / Equifaxend of 2019 and end of 2025
- Mortgages with little equityFederal Housing Finance Agency, National Mortgage Databasesecond quarter of 2026
- Mortgages 30 to 89 days late; mortgage complaints; medical debts on credit reportsConsumer Financial Protection Bureau: Mortgage Performance Trends; complaint database; Recent changes in medical collections on consumer credit recordsSept. 2025; Oct. 14, 2026; March 2022 to June 2023
- Bankruptcy filingsAdministrative Office of the U.S. Courts, Table F-22001 to 2025
- SNAPU.S. Department of Agriculture Food and Nutrition Administration; Pennsylvania Department of Human Servicesthrough June 2026; Aug. 2026
- Cost of getting byMIT Living Wage Calculator2025 dollars
- Minimum wagesU.S. Department of Labor, state minimum wage laws; Pennsylvania General Assembly, House Bill 2189July 1, 2026; Sept. 30, 2026
- Mortgage help fundU.S. Treasury, Homeowner Assistance Fund; Pennsylvania Housing Finance Agencythrough early 2026
- Foreclosure lawAct 6 of 1974; Housing Finance Agency Law, as amended by Act 91 of 1983; Pennsylvania Rules of Civil Procedure; Pennsylvania Housing Finance Agency, HEMAP; Philadelphia Court of Common Pleas; Allegheny County courts; 12 CFR 1024.41as of 2026
- Poverty guidelineU.S. Department of Health and Human Services2026
- Housing counselorsU.S. Department of Housing and Urban DevelopmentOctober 2026
- What changed and what to watchPennsylvania Public Utility Commission, Pennsylvania Public Utility Commission, July 7, 2026, Pennsylvania General Assembly, Pennie, Pennsylvania Department of Human Services, Office of the Governor, Pennsylvania Department of Revenue, Bureau of Labor Statistics release. Each item links the page it was read on (see what changed)Sept. 2025 to Jan. 2027
- PhotoDasprevailz, via Wikimedia Commons, public domainundated
Jobs, late payments, collections and bankruptcy, and renters’ housing costs count equally. We average the four parts for every state, then score each state by the percentage of the other 49 states and D.C. with a lower average, so a state at 80 is more distressed than 80% of the rest. The full method →
We write with AI tools, and Ross Kilburn checks and reviews every page before it's published.
Get the next Pennsylvania edition by email
One email each time a new Pennsylvania edition is out; the next is expected in March 2027. Unsubscribe anytime.
Thanks, that helps.