Virginia lost 26,200 federal jobs from January 2025 to August 2026
Each state is shaded by how distressed its households are, from green (least) to red (most), with data through September 2026. Virginia scores 38 out of 100.
Virginia is less distressed than each of its six neighbors. Its households earn more than most, yet its 2025 bankruptcy rate, 179.7 filings per 100,000 residents, ran above the national rate. Petersburg, an independent city south of Richmond, is more distressed than 99% of U.S. counties and 14th most distressed in the nation. Northern Virginia, home to about a third of Virginians, is the least distressed part of the state.
- Score
- 38/100
- Data through
- September 2026
- Edition
- October 2026
Next edition expected March 2027
How Virginia ranks among the states
Virginia is richer than most states but only a little less distressed than the typical one. Its typical household earned $92,116 in 2024, 13th highest among the 50 states and D.C. overall. Yet its 2025 bankruptcy rate, 179.7 filings per 100,000 residents (2025 population), was above the national rate and 19th highest (Administrative Office of the U.S. Courts). The collections and bankruptcy part is the highest of its four parts, and the jobs part has risen from 21 to 42 since early 2025 (see the economy).
What drives the score
Every part below runs from 0 to 100, set by Virginia’s place among the 50 states and D.C. on the measures it holds. Averaged, Virginia’s four parts come to 45, but the State Distress Index score is a different number: the share of the other 49 states and D.C. that have a lower four-part average. That is 19 of the 50, or 38%, which makes the score 38. A state with a score of 80, by the same count, is more distressed than 80% of the rest.
- Collections and bankruptcy54Virginia’s 2025 bankruptcy rate was 179.7 filings per 100,000 residents (2025 population), against 166.3 for the U.S., but a smaller share of its people with a credit record, 10.9%, had a debt in collections in early 2025 than nationwide, 13.2%.
- Late payments44In early 2025, fewer Virginia borrowers were 90 days or more behind than borrowers across the country: 11.7% on cards, 7.8% on car loans and 0.9% on mortgages.
- Renters’ housing costs38Rent and utilities took at least half the income of 23.9% of Virginia’s renter households in 2024; across the U.S. the share was 26.1%.
- Jobs42Virginia’s unemployment rate averaged 3.7% from June through August 2026; the U.S. rate averaged 4.1%.
All six places that border Virginia score higher
Kentucky and Maryland are the most distressed of Virginia’s neighbors, then West Virginia, D.C. and Tennessee. North Carolina comes closest to Virginia’s score and is the only neighbor in the same shade on the map.
State Distress Index score, 0 to 100. Of the 50 states and D.C., Kentucky is 15th most distressed, D.C. 24th and North Carolina 29th. August 2026 unemployment ran highest among the neighbors in D.C., at 5.7%; only North Carolina, at 3.5%, and Tennessee, at 3.4%, came in under Virginia’s 3.6% (U.S. Bureau of Labor Statistics).
Virginia has ranked in the less distressed half of the states in every quarter since 2006
At its worst
Virginia’s highest score, 42, held from the third quarter of 2017 through the first quarter of 2018, when it was the 30th most distressed state, its closest approach to the middle. Its lowest, 16, came in the third quarter of 2006, the first quarter our index has all four parts, when it ranked 43rd.
What moved it
Two parts cause most of the jumps. The renters’ part changes once a year, when new Census figures come out: in the third quarter of 2017 it went from 42 to 56 and the score from 36 to 42. In the third quarter of 2022 it went from 36 to 52, lifting the score from 32 to 38. The jobs part rose from 19 to 46 between the first and third quarters of 2020, after unemployment spiked that spring, and was back below its starting point by mid-2022.
Since the chart ends
The quarterly history ends with the first quarter of 2025; Virginia then scored 32 and ranked 35th. Today it scores 38 and ranks 32nd. The jobs part made almost all of the move, rising from 21 to 42; the renters’ part slipped from 46 to 38, and late payments and collections barely changed.
Virginia’s distress score has stayed between 16 and 42 since 2006
Virginia’s State Distress Index score each quarter, 0 to 100, from the third quarter of 2006 (the first with all four parts) to the first quarter of 2025.
Which counties and cities in Virginia are the poorest and the most distressed?
Radford, a city in the New River Valley, is the poorest: 27.2% of its residents lived below the poverty line in 2024, the Census Bureau estimates, the highest rate of Virginia’s 133 localities. Virginia has 95 counties and 38 independent cities, and each city stands outside any county, so federal statistics count it as a county of its own and so do we. Petersburg, a city south of Richmond, scores 99 on our County Distress Index, which scores the strain on household budgets in every U.S. county: the most distressed in Virginia and 14th of all 3,144 nationwide. The cities of Hopewell, Franklin, Danville and Emporia are also among the 100 most distressed in the country (see the national list). Goochland County, west of Richmond, is the least distressed, at 1, with the 55th lowest score of all 3,144.
Distress runs highest in the far Southwest, Southside and a string of small cities; Northern Virginia has the least
County Distress Index scores, 0 to 100, for Virginia’s 95 counties and 38 independent cities, with data through August 2026.
Loading the locality map…
The locality map could not be loaded. Every locality is in the lists on this page.
Most distressed
| Rank | Locality | Score | Poverty |
|---|---|---|---|
| 1 | Petersburg city | 99 | 23.3% |
| 2 | Hopewell city | 99 | 17.1% |
| 3 | Franklin city | 98 | 19.7% |
| 4 | Danville city | 98 | 22.9% |
| 5 | Emporia city | 97 | 20.6% |
| 6 | Lee County | 96 | 26.0% |
| 7 | Buchanan County | 96 | 23.5% |
| 8 | Portsmouth city | 96 | 15.2% |
| 9 | Bristol city | 94 | 18.6% |
| 10 | Martinsville city | 93 | 18.8% |
Least distressed
| Rank | Locality | Score | Poverty |
|---|---|---|---|
| 129 | Falls Church city | 4 | 4.6% |
| 130 | Arlington County | 4 | 8.0% |
| 131 | Poquoson city | 4 | 5.8% |
| 132 | Loudoun County | 3 | 4.3% |
| 133 | Goochland County | 1 | 6.9% |
Rank among Virginia’s 133 counties and independent cities, 1 = most distressed. Ranks follow unrounded scores, so two places printing the same score can hold different ranks. Poverty is each place’s 2024 rate from the Census Bureau.
Every county and city, by score
Of Virginia’s 133 localities, 28 score 80 or more, home to 17.1% of its people; 10 of them are in Southside and around Lynchburg, 7 in the far Southwest and 5 on Hampton Roads, and none is in Northern Virginia. At the other end, 33 score under 30, and because they include the big Northern Virginia counties they hold 45.0% of Virginians, more than twice the share.
28 score 80–100
Petersburg city, Hopewell city, Franklin city, Danville city, Emporia city, Lee County, Buchanan County, Portsmouth city, Bristol city, Martinsville city, Norton city, Greensville County, Hampton city, Tazewell County, Norfolk city, Buckingham County, Sussex County, Halifax County, Covington city, Wise County, Richmond city, Newport News city, Henry County, Essex County, Nottoway County, Scott County, Roanoke city, Lynchburg city
12 score 70–79
Westmoreland County, Colonial Heights city, Brunswick County, Galax city, Prince Edward County, Smyth County, Radford city, Lunenburg County, Russell County, Dinwiddie County, Dickenson County, Charlotte County
28 score 50–69
Pulaski County, Buena Vista city, Charles City County, Wythe County, Northumberland County, Fredericksburg city, Williamsburg city, Grayson County, Richmond County, Winchester city, Carroll County, Accomack County, Pittsylvania County, Cumberland County, Amherst County, Mecklenburg County, Patrick County, Waynesboro city, Page County, King and Queen County, Amelia County, Suffolk city, Harrisonburg city, Lancaster County, Staunton city, Northampton County, Southampton County, Alleghany County
32 score 30–49
Chesapeake city, Henrico County, Caroline County, Spotsylvania County, Washington County, Mathews County, Giles County, Middlesex County, Manassas city, Louisa County, Prince George County, Bland County, Campbell County, Virginia Beach city, King William County, Surry County, Highland County, Salem city, Appomattox County, Franklin County, Lexington city, Manassas Park city, Nelson County, Montgomery County, Craig County, Chesterfield County, Gloucester County, Rappahannock County, Charlottesville city, Isle of Wight County, Culpeper County, Shenandoah County
33 score 0–29
Prince William County, Warren County, Orange County, Stafford County, Bedford County, Greene County, Fluvanna County, Alexandria city, Clarke County, King George County, Fairfax city, James City County, Bath County, Augusta County, Roanoke County, Floyd County, Frederick County, Rockingham County, York County, Rockbridge County, Powhatan County, Fauquier County, Albemarle County, Madison County, New Kent County, Hanover County, Fairfax County, Botetourt County, Falls Church city, Arlington County, Poquoson city, Loudoun County, Goochland County
Virginia’s poorest places are not always its most distressed
Poverty is only one input to the County Distress Index. It weighs five parts equally: late payments, collections and bankruptcy, jobs, renters’ housing costs, and a safety-net part built from poverty, child poverty, household income, disability and health insurance. Three of Virginia’s five poorest places, Greensville, Lee and Buchanan counties, rank 12th, 6th and 7th on distress. The other two do not: Radford, the poorest, ranks 35th, and Harrisonburg, a Shenandoah Valley city with the 2nd highest poverty rate, 26.4%, ranks 63rd. The gap runs the other way too. Hopewell is the 2nd most distressed place in Virginia, yet its poverty rate, 17.1%, is 31st highest; Portsmouth, 8th on distress, has a poverty rate of 15.2%, 43rd highest. All of these rates are the Census Bureau’s 2024 Small Area Income and Poverty Estimates; a site that uses a different survey or year may name a different poorest place.
The five poorest places
| Locality | Poverty | Distress rank |
|---|---|---|
| Radford city | 27.2% | 35th |
| Harrisonburg city | 26.4% | 63rd |
| Greensville County | 26.2% | 12th |
| Lee County | 26.0% | 6th |
| Buchanan County | 23.5% | 7th |
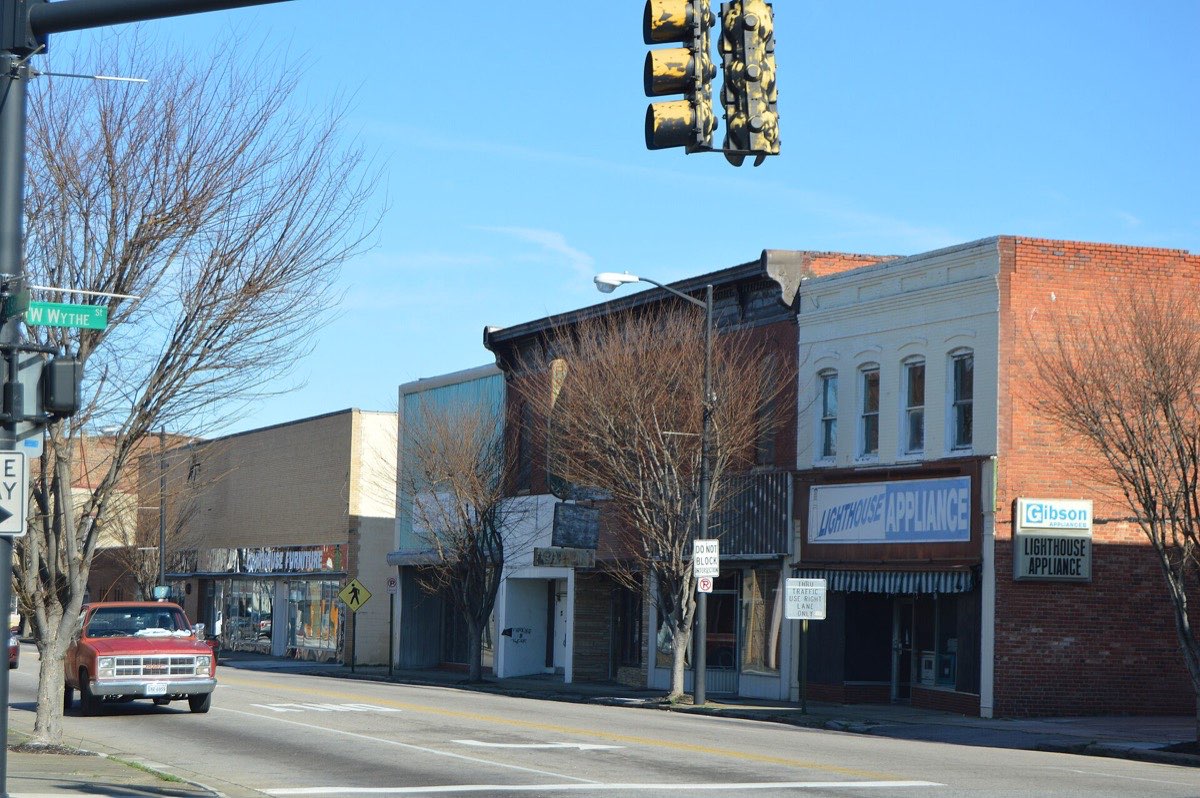
Sycamore Street in Petersburg, an independent city south of Richmond, in February 2020. Petersburg scores 99 on our County Distress Index, the most distressed of Virginia’s 133 localities and 14th of all 3,144 U.S. counties, and 23.3% of its residents were poor in 2024, tied for 6th highest in the state (Census Bureau).
Source: U.S. Census Bureau; American Default Research. Photo: Nyttend, public domain, via Wikimedia Commons.

Northern Virginia against the far Southwest and Southside
Virginians talk about their state in regions, Northern Virginia, Hampton Roads, Southside, but no law draws those lines, so the groups below are our own, and each place counts in proportion to its population. Northern Virginia, 10 counties and cities with 31.2% of the state’s residents, averages 12, and its highest-scoring place, the city of Manassas, scores 43. The far Southwest, 16 places, averages 74, and Southside with the Lynchburg area, 21 places, averages 73; they hold 4.2% and 6.2% of Virginians. Hampton Roads averages 58, and 5 of its 16 places score 80 or more, Portsmouth, Hampton, Norfolk and Newport News among them. The Richmond area averages 47, a figure that hides a split: Petersburg and Hopewell, the two most distressed places in Virginia, are in it, and so is Goochland, the least. Roanoke and the New River Valley average 40, and the rest of the state, from the Shenandoah Valley to the Eastern Shore, 34. These averages show where the strain sits; they don’t explain it.
County Distress Index (American Default Research), each place weighted by its Census population; the groupings and the averages are ours.
Is Virginia a poor state? No, it has less poverty and more income than most
No. In 2024, 9.8% of Virginians lived below the poverty line, tied for 8th lowest among the 50 states and D.C., against 12.1% nationwide. The typical household earned $92,116, 13th highest, against $81,604 for the U.S. (Census Bureau, Small Area Income and Poverty Estimates). Income per person, everything residents received divided by their number, came to $77,351, 12th highest (U.S. Bureau of Economic Analysis). Poverty is far from even across the state (see the poorest places).
Residents in poverty
9.8%
U.S. 12.1%
2024: tied for 8th lowest of the 50 states and D.C.
Children in poverty
11.8%
U.S. 15.5%
2024: tied for 15th lowest of the 50 states and D.C.
Median household income
$92,116
U.S. $81,604
2024: 13th highest of the 50 states and D.C.
Virginia’s poverty rate has been lower than the nation’s in every Census estimate since 1989
Share of people below the poverty line in Virginia and the U.S., 1989 to 2024. The Census Bureau made no state estimates for 1990 to 1992 or for 1994.
Virginia’s minimum wage is set to climb each January through 2028
Virginia’s minimum wage has been $12.77 an hour since Jan. 1, 2026, up from $12.41 in 2025 and well above the federal minimum of $7.25. State law sets the next steps: $13.75 on Jan. 1, 2027, and $15.00 on Jan. 1, 2028 (Code of Virginia § 40.1-28.10).
Virginia’s SNAP count is down from a year earlier
In June 2026, 750,364 Virginians got SNAP, the federal food benefit once called food stamps: 8.5% of the state’s 2025 population, 18th lowest among the 50 states and D.C., against 10.6% nationwide (U.S. Department of Agriculture). In June 2025 the count was 813,228, so it fell by 62,864, or 7.7%. The count was already falling in the months before Nov. 1, 2025, when Virginia ended several SNAP work-rule exemptions (see what changed). The monthly counts jump around from October to December 2025, so we leave those months out of any trend. Fewer people on SNAP doesn’t by itself mean less need. Apply for SNAP through Virginia’s social services department →
Why other sites show a slightly different Virginia poverty rate
Some sites quote the Census Bureau’s American Community Survey, whose figures for Virginia differ a little from the ones here. We use the bureau’s Small Area Income and Poverty Estimates, which it makes each year for the state and for every county and city, so all the poverty rates on this page share one source. Benefit programs decide who qualifies with the federal poverty guideline instead, a separate measure (see the questions below). Virginia’s poorest places →
How is Virginia’s economy doing? Unemployment has risen, and federal jobs have fallen
Unemployment is low by national standards, but higher than it was. In August 2026, 3.6% of Virginia’s labor force was out of work and looking for it, tied for 30th highest among the 50 states and D.C.; the U.S. rate was 4.1% (U.S. Bureau of Labor Statistics). For a single month, the bureau’s test doesn’t count the gap between Virginia and the U.S. as significant, but Virginia’s yearly average has come in under the nation’s in every year since 1990. Month by month, the state’s rate rose from 2.8% in January 2024 to 3.2% in January 2025 and 3.8% from February through June 2026, before easing to 3.6%.
Unemployment rate
3.6%
U.S. 4.1%
August 2026: tied for 30th highest of the 50 states and D.C.
Federal government jobs
169,500
August 2026 (preliminary): 3rd most of the 50 states and D.C.
Fall in federal jobs since January 2025
13.4%
To August 2026: the 4th steepest fall of the 50 states and D.C.
Virginia’s yearly unemployment rate has been below the U.S. rate in every year since 1990
Share of the labor force out of work and looking for work, Virginia and the U.S., each month, seasonally adjusted, January 1990 to August 2026. Our figures have no October 2025 value, so that month has no point. The headline uses yearly averages.
Federal jobs in Virginia have fallen steeply since January 2025
Virginia had 169,500 federal government jobs in August 2026, 3rd most of the 50 states and D.C. overall. They made up 4.0% of all its jobs, a share topped only by D.C., Hawaii and Maryland (U.S. Bureau of Labor Statistics; August figures are preliminary). That is 26,200 fewer than in January 2025, when the count stood at 195,700: a fall of 13.4%, the 4th steepest in the country after Maryland, D.C. and Alaska. The sharpest single month was October 2025, down 13,200.
Did the federal cuts push up Virginia’s unemployment? Our data can’t settle it. The timing lines up, and the federal loss is large next to the state’s whole job count, which fell 0.8% between January 2025 and August 2026. The federal jobs lost alone equal 0.6% of the jobs Virginia had in January 2025. But job counts are taken where people work. Meanwhile, the unemployment rate counts where they live, so a federal worker in D.C. who lives in Virginia is counted in D.C.’s jobs but in Virginia’s unemployment rate. Virginia’s rate rose 0.4 percentage points over those months. But unemployment also rose in 19 of the other 49 states and D.C., and our data has no count of federal contractors. What changed in the past year →
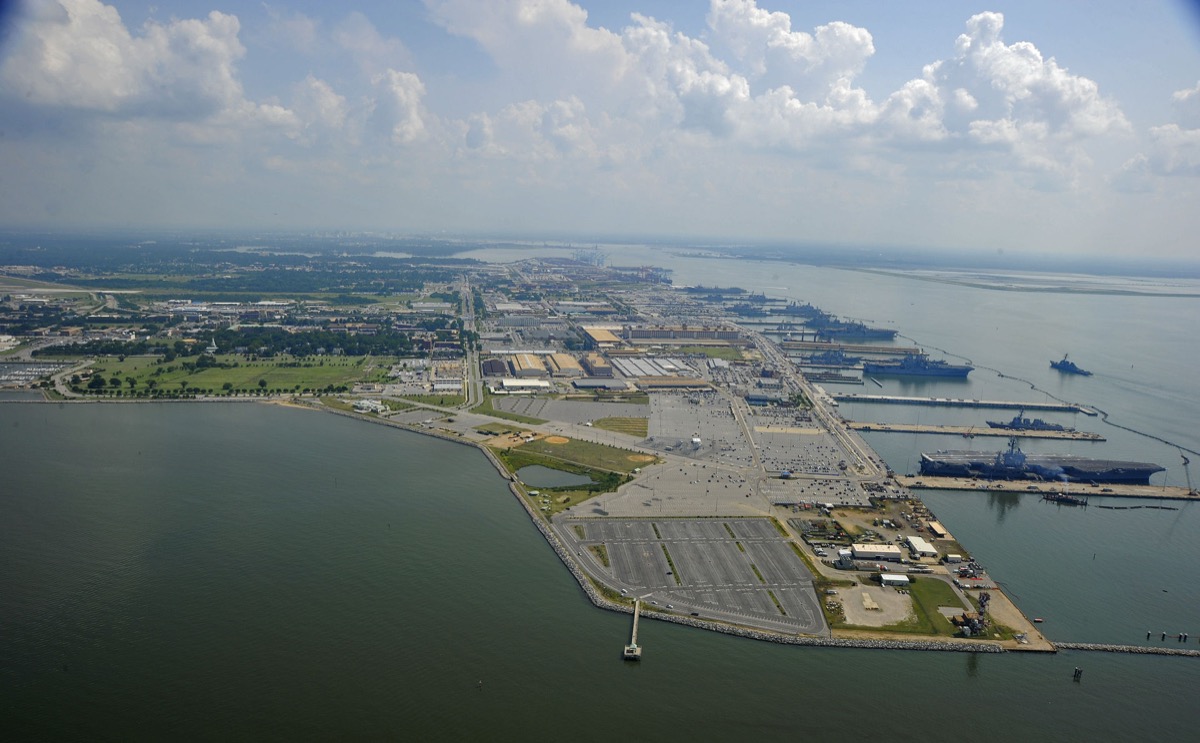
Naval Station Norfolk, on Hampton Roads, from the air in July 2011. Federal government jobs, which the U.S. Bureau of Labor Statistics counts without uniformed military personnel, made up 4.0% of Virginia’s jobs in August 2026, 4th highest among the 50 states and D.C.
Source: U.S. Bureau of Labor Statistics. Photo: U.S. Navy, Mass Communication Specialist 1st Class Christopher B. Stoltz, via Wikimedia Commons, public domain.

What changed in Virginia in the past year
-
Jan. 1, 2026
Virginia’s minimum wage went up
The state minimum wage rose to $12.77 an hour, from $12.41 in 2025, as the Virginia labor department announced in July 2025; the U.S. Department of Labor’s table of state rates, updated July 1, 2026, lists the new rate. State law already sets the next two increases (see what to watch).
Virginia labor department, July 28, 2025; U.S. Department of Labor, state minimum wages
-
Dec. 31, 2025
Extra federal help with marketplace health premiums ran out
Enhanced premium tax credits, extra federal help since 2021 with the cost of plans bought through Virginia’s Insurance Marketplace, expired at the end of 2025. The original Affordable Care Act credits are still there for people who qualify, and the marketplace told enrollees that some of them may pay higher monthly premiums in 2026. Neither marketplace page counts how many Virginians the change reaches.
Virginia’s Insurance Marketplace, federal changes; 2026 cost change notice
-
Nov. 25, 2025
Regulators approved higher Dominion Energy base rates for 2026 and 2027
The Virginia State Corporation Commission approved a base-rate increase of $565.7 million for Dominion Energy Virginia in 2026, less than the $822 million the utility had asked for, and a smaller one for 2027. For a typical residential customer, the commission said, the approved rates mean monthly increases of $11.24 in 2026 and $2.36 in 2027. The order covers Dominion’s customers only.
-
Nov. 1, 2025
SNAP work rules began to cover more adults
A federal law signed on July 4, 2025, widened SNAP’s work rule, Virginia’s social services department explains. The upper age limit went from 55 to 65, so adults up to 64 may now have to work or take part in a work activity to get benefits for more than three months in three years, and a parent whose dependent child is 14 or older may no longer be exempt. From Nov. 1, 2025, people experiencing homelessness, veterans, and young adults 18 to 24 who had left foster care no longer had an exemption of their own. The department gives no count of Virginians affected.
-
Oct. 2025
Federal jobs in Virginia took their biggest one-month fall
Federal employment in Virginia dropped by 13,200 from September to October 2025, the largest monthly fall since January 2025, where our figures from the U.S. Bureau of Labor Statistics begin. By August 2026 the state had 169,500 federal jobs, 26,200 fewer than in January 2025 (see federal jobs).
U.S. Bureau of Labor Statistics, State and Metro Area Employment
Is Virginia expensive to live in? Rent is high, and so is income
Rent runs above the national median, but income runs higher still. Half of Virginia renters paid less than $1,579 a month in the Census Bureau’s 2020 to 2024 survey, 12th highest among the 50 states and D.C., against a U.S. median of $1,413. Twelve months of that rent equal 20.6% of the typical Virginia household’s 2024 income, close to the U.S. figure of 20.8% (our calculation). We hold no prices for groceries, gas or electricity, so we can’t rank Virginia’s overall cost of living.
Median rent, a month
$1,579
U.S. $1,413
2020 to 2024: 12th highest of the 50 states and D.C.
Renters spending at least 30% of income on housing
45.3%
U.S. 47.6%
2020 to 2024: tied for 22nd highest of the 50 states and D.C.
Homeowners spending at least 30% of income on housing
20.3%
U.S. 22.5%
2020 to 2024: tied for 27th highest of the 50 states and D.C.
In every year since 2005, Virginia’s share of renters paying half their income for housing has been below the U.S. share
Renter households whose rent and utilities take half their income or more, Virginia and the U.S., Census Bureau one-year surveys, 2005 to 2024. No figures were published for 2020.
This share is the one measure in the renters’ part of our State Distress Index. New figures arrive once a year, which is why Virginia’s score can step up or down in a single quarter (see how it ranks).
What a basic Virginia budget costs, by MIT’s estimate
The MIT Living Wage Calculator puts yearly basic costs before taxes at $53,505 for one adult with no children in Virginia. That is 13th highest among the 50 states and D.C. For two working parents with two children, it estimates $121,475 (2025 dollars). Those budgets pay for necessities and leave nothing to save.
Among Virginia’s neighbors, only D.C. and Maryland have higher rent
Measured against income, rent takes a larger share in Virginia than in any neighbor except D.C.
| Place | Rent, a month | Median household income | Rent as share of income |
|---|---|---|---|
| D.C. Rent as share of income 21.5% | $1,954 Median household income $109,289 | $109,289 | 21.5% |
| Maryland Rent as share of income 19.9% | $1,705 Median household income $102,835 | $102,835 | 19.9% |
| Virginia Rent as share of income 20.6% | $1,579 Median household income $92,116 | $92,116 | 20.6% |
| North Carolina Rent as share of income 19.9% | $1,228 Median household income $74,055 | $74,055 | 19.9% |
| Tennessee Rent as share of income 19.8% | $1,189 Median household income $72,007 | $72,007 | 19.8% |
| Kentucky Rent as share of income 18.0% | $967 Median household income $64,481 | $64,481 | 18.0% |
| West Virginia Rent as share of income 17.2% | $872 Median household income $60,662 | $60,662 | 17.2% |
Rent: median gross rent a month, 2020 to 2024 (Census Bureau, American Community Survey). Income: median household income, 2024 (Census Bureau, Small Area Income and Poverty Estimates). The share is our calculation, a year of median rent over median household income. Rent and housing costs in every state →
Are Virginians behind on their bills? Less often than most Americans, though they owe more
Less often than Americans overall. In early 2025, 15.1% of Virginians with credit records had debt 90 or more days late, tied for 27th highest among the 50 states and D.C., against 17.2% nationally, our population-weighted average of the states (Federal Reserve Bank of Philadelphia). Yet Virginians carry more debt than most: $77,060 per person with a credit report at the end of 2025, 9th highest, against $63,200 nationwide (Federal Reserve Bank of New York). All of this is what households owe, not the state government’s debt.
Counting from the highest share among the 50 states and D.C., Virginia ranks 29th on collections, 30th on cards, 25th on car loans and tied for 31st on mortgages. The U.S. bars average the states, with bigger states counting for more.
More Virginia card borrowers are seriously behind than before the pandemic: 9.1% were 90 or more days late at the end of 2019, against 11.7% in early 2025. Collections moved the other way, from 20.8% to 10.9%, over the years when the three big credit bureaus dropped many medical debts from credit reports. A debt removed from a report isn’t necessarily paid. Across the country, people with a medical collection on their report went from about 14% in March 2022 to about 5% in June 2023 (Consumer Financial Protection Bureau). The Urban Institute, a research group, publishes a separate measure. In 2025, 0.8% of Virginians with a credit record had medical debt in collections, 2nd lowest of the 44 places with a published figure, including D.C. The national share was 3.2%.
Counted in dollars, less of Virginia’s card debt is far behind than the nation’s
The Federal Reserve Bank of New York measures dollars instead of people: what share of balances is 90 days or more overdue. At the end of 2025, 9.9% of Virginia credit card balances were that far behind, 15th lowest among the 50 states and D.C. and under the U.S. share of 12.4%, though up from 6.6% at the end of 2019. Car-loan and mortgage dollars were also less often far behind than nationwide.
| Loan type | Virginia | U.S. | Virginia 2019 | U.S. 2019 |
|---|---|---|---|---|
| Credit card | 9.9% End of 2025 U.S. 12.4% Virginia 2019 6.6% · U.S. 2019 8.1% | 12.4% | 6.6% | 8.1% |
| Auto loan | 4.6% End of 2025 U.S. 5.2% Virginia 2019 3.9% · U.S. 2019 4.9% | 5.2% | 3.9% | 4.9% |
| Mortgage | 0.7% End of 2025 U.S. 0.9% Virginia 2019 0.7% · U.S. 2019 1.0% | 0.9% | 0.7% | 1.0% |
Share of balances 90 or more days past due, end of 2025 and end of 2019 (Federal Reserve Bank of New York, Consumer Credit Panel / Equifax). Because it counts dollars rather than people, it doesn’t line up directly with the Philadelphia Fed chart above, and it keeps old debts lenders have written off but still report.
Virginians owe more than most Americans, but their mortgages are mostly current
Virginians with a credit report owed $77,060 each in household debt at the end of 2025, 9th highest among the 50 states and D.C. (Federal Reserve Bank of New York). Yet their mortgages are mostly current. In September 2025, 1.4% of Virginia mortgages were 30 to 89 days late, against 1.6% nationwide (Consumer Financial Protection Bureau). In the second quarter of 2026, 4.2% had less than 10% equity, against 4.7% nationally (Federal Housing Finance Agency).
| Measure | Virginia | U.S. | Rank |
|---|---|---|---|
| Household debt per person with a credit report, end of 2025 9th highest | $77,060 U.S. $63,200 | $63,200 | 9th highest |
| Card balances per person with a credit report, end of 2025 12th highest | $4,770 U.S. $4,350 | $4,350 | 12th highest |
Rank among the 50 states and D.C. Debt per person adds up every kind of household debt (Federal Reserve Bank of New York). Household debt in every state →
Bankruptcy in Virginia: filings are rising, and the rate is above the nation’s
Virginians filed 15,959 bankruptcy cases in 2025, the most since 2020: 179.7 for every 100,000 residents (2025 population), 19th highest among the 50 states and D.C., against 166.3 nationwide (Administrative Office of the U.S. Courts). Filings rose 9.9% from 2024, a little less than the 11.1% rise across the country, and have gone up every year since 2022, the year with the fewest in the available series. They are still 31.5% below 2019, when Virginians filed 23,297 cases (our calculation).
Chapter 13 made up 39.5% of Virginia’s 2025 cases, against 35.9% nationwide, 16th highest among the 50 states and D.C. overall. Under Chapter 13 a filer pays creditors part of what is owed over three to five years, on a plan the court approves, rather than having property sold. Chapter 7, the more common choice nationwide, wipes out many debts but can mean giving up property the law doesn’t shield.
| Year | Filings |
|---|---|
| 2005 | 45,097 |
| 2009 | 36,531 |
| 2019 | 23,297 |
| 2020 | 16,517 |
| 2021 | 12,448 |
| 2022 | 11,374 |
| 2023 | 13,004 |
| 2024 | 14,524 |
| 2025 | 15,959 |
Cases under every chapter in Virginia’s two federal bankruptcy courts, the Eastern and Western districts, in selected years and each year since 2019. The available series cover 2001 to 2025 except 2004; of those years, 2005 had the most filings and 2022 the fewest. Source: Administrative Office of the U.S. Courts, Table F-2. Bankruptcy filings in every state →
Foreclosure in Virginia: a home can be sold without a court case
Most Virginia foreclosures never go before a judge. Home loans here are usually secured by a deed of trust, and when a borrower falls behind, the trustee named in it can sell the home at a public sale. For a home the owner lives in, notice of the sale has to be mailed by certified or registered mail at least 60 days ahead (Va. Code § 55.1-321), and the sale has to be advertised in a newspaper; it can take place no sooner than eight days after the first ad and no later than 30 days after the last (Va. Code § 55.1-322).
Once the sale is over, Virginia law gives the former owner no right to buy the home back, and the lender can sue for any balance the sale didn’t cover. Federal mortgage servicing rules generally bar a servicer from starting a foreclosure on a primary home before the loan is more than 120 days behind.
- Goes through a court
- Usually not
- Mailed notice before the sale
- 60 days
- Buy-back right after the sale
- None
- Suit for the unpaid balance
- Allowed
- Federal wait before starting
- Over 120 days behind
What the law says for a home you live in. Sources: Va. Code §§ 55.1-321 and 55.1-322; federal rule 12 CFR 1024.41. How foreclosure works in Virginia →
Virginia was awarded $258.4 million from the federal Homeowner Assistance Fund and had used it to help 12,612 households through early 2026 (U.S. Treasury). Our Virginia foreclosure guide lists the help on offer now.
Virginia mortgage complaints: what borrowers tell the CFPB
Since 2012, the Consumer Financial Protection Bureau has logged 14,635 mortgage complaints from Virginia. Trouble during the payment process, such as how payments, fees and escrow are handled, leads with 3,731; loan modifications, collection and foreclosure come next, with 3,214.
- Oct. 7, 2026 Glasser and Glasser, PLC Payment process Closed with explanation
- Oct. 5, 2026 Glasser and Glasser, PLC Struggling to pay: foreclosure Closed with explanation
- Oct. 1, 2026 Select Portfolio Servicing Struggling to pay: applying for a modification, forbearance, short sale or deed-in-lieu Closed with explanation
- Sept. 30, 2026 PennyMac Payment process: escrow, taxes or insurance Closed with explanation
- Sept. 30, 2026 Bank of America Payment process In progress
- Sept. 30, 2026 Virginia Housing Development Authority Payment process: trouble reaching the company to fix a problem with the loan Closed with explanation
- Sept. 29, 2026 M&T Bank Struggling to pay: an existing modification, forbearance or other relief Closed with explanation
- Sept. 29, 2026 Selene Finance Struggling to pay: foreclosure Closed with explanation
- Sept. 28, 2026 Movement Mortgage LLC Struggling to pay: trouble reaching the company about a modification, forbearance or foreclosure Closed with explanation
- Sept. 28, 2026 Carrington Mortgage Struggling to pay: an existing modification, forbearance or other relief In progress
The latest 10 Virginia complaints about paying a mortgage or getting help with one, newest first, from the Consumer Financial Protection Bureau’s public database as we pulled it in October 2026. Complaints about getting a new loan, and any naming a credit bureau, are left out. Each is one borrower’s account. The bureau doesn’t verify it, and a complaint isn’t proof that a company did anything wrong. Every Virginia mortgage complaint at the Consumer Financial Protection Bureau →
What to watch before the next edition
Five scheduled changes fall before the next edition, listed nearest first, each from the office that set it.
-
Nov. 1, 2026
Soda comes off the SNAP shopping list
Starting Nov. 1, SNAP benefits can no longer pay for sweetened carbonated drinks in Virginia, the state’s social services department says; benefit amounts stay the same.
-
Nov. 1, 2026
Marketplace open enrollment starts, with new state help
Open enrollment on Virginia’s Insurance Marketplace runs from Nov. 1, 2026, to Jan. 29, 2027. For 2027 plans, a state fund the General Assembly created in a 2026 special session will offer Virginia Premium Savings to people with incomes from 138% to 250% of the federal poverty level.
-
Nov. 20, 2026
Virginia’s October unemployment rate
The U.S. Bureau of Labor Statistics is scheduled to publish state unemployment rates for October 2026 on Nov. 20 and for November 2026 on Dec. 18.
-
Jan. 1, 2027
The minimum wage is set to take its next step
Under Code of Virginia § 40.1-28.10, the minimum wage is set to rise to $13.75 an hour on Jan. 1, 2027, and to $15.00 on Jan. 1, 2028.
-
Jan. 1, 2027
Dominion’s second-year rate step
The second year of Dominion Energy Virginia’s approved base-rate increase, $2.36 a month for a typical residential customer, is set to begin, along with a new rate class for customers using 25 megawatts or more.
Where Virginia ranks highest and lowest
| Measure | Virginia | U.S. | Rank | Latest data |
|---|---|---|---|---|
| Federal government jobs, share of all jobs 4th highest · Aug. 2026 | 4.0% U.S. 1.7% | 1.7% | 4th highest | Aug. 2026 |
| Household debt per person with a credit report 9th highest · End of 2025 | $77,060 U.S. $63,200 | $63,200 | 9th highest | End of 2025 |
| Median rent, a month 12th highest · 2020 to 2024* | $1,579 U.S. $1,413 | $1,413 | 12th highest | 2020 to 2024* |
| Card balances per person with a credit report 12th highest · End of 2025 | $4,770 U.S. $4,350 | $4,350 | 12th highest | End of 2025 |
| Median household income 13th highest · 2024 | $92,116 U.S. $81,604 | $81,604 | 13th highest | 2024 |
| Share of bankruptcy filings under Chapter 13 16th highest · 2025 | 39.5% U.S. 35.9% | 35.9% | 16th highest | 2025 |
| Bankruptcy filings per 100,000 residents (2025 population) 19th highest · 2025 | 179.7 U.S. 166.3 | 166.3 | 19th highest | 2025 |
| Unemployment rate, three-month average 30th highest · June–August 2026 | 3.7% U.S. 4.1% | 4.1% | 30th highest | June–August 2026 |
| Card borrowers 90+ days late 22nd lowest · Early 2025 | 11.7% U.S. 13.5% | 13.5% | 22nd lowest | Early 2025 |
| Mortgages 30 to 89 days late Tied for 20th lowest · Sept. 2025 | 1.4% U.S. 1.6% | 1.6% | Tied for 20th lowest | Sept. 2025 |
| Renters spending at least half their income on housing 22nd lowest · 2024 | 23.9% U.S. 26.1% | 26.1% | 22nd lowest | 2024 |
| People with a debt in collections 23rd lowest · Early 2025 | 10.9% U.S. 13.2% | 13.2% | 23rd lowest | Early 2025 |
| Residents getting SNAP food benefits (2025 population) 18th lowest · June 2026 | 8.5% U.S. 10.6% | 10.6% | 18th lowest | June 2026 |
| Children in poverty Tied for 15th lowest · 2024 | 11.8% U.S. 15.5% | 15.5% | Tied for 15th lowest | 2024 |
| Residents in poverty Tied for 8th lowest · 2024 | 9.8% U.S. 12.1% | 12.1% | Tied for 8th lowest | 2024 |
Each rank places Virginia among the 50 states and D.C., counted from the top or from the bottom as the cell says. Places printing the same value share a rank. * Census Bureau five-year survey, 2020 to 2024. Federal jobs: U.S. Bureau of Labor Statistics, preliminary for August; the U.S. share is our sum of the 50 states and D.C. combined. Collections and card borrowers count people with a credit record (Federal Reserve Bank of Philadelphia), and their U.S. figures are our population-weighted average of the states. Debt and card balances per person: Federal Reserve Bank of New York. Sources and method names the source of every row. Download this table: CSV.
Questions about Virginia
Is Virginia a poor state?
No. In 2024, 9.8% of Virginians lived below the poverty line, against 12.1% for the U.S., and the typical household earned $92,116, against $81,604 (U.S. Census Bureau, Small Area Income and Poverty Estimates). On our State Distress Index, which also weighs debts, jobs and rent, Virginia ranks 32nd of the 50 states and D.C. Is Virginia poor? →
What is the poorest county in Virginia?
Counting its independent cities, which federal statistics treat as counties, the poorest is Radford, a city in the New River Valley: 27.2% of its residents were poor in 2024 (U.S. Census Bureau, Small Area Income and Poverty Estimates). Among counties alone, Greensville County, on the North Carolina line, has the highest rate, 26.2%. The most distressed place on our County Distress Index is Petersburg, also a city. Virginia’s poorest places →
What is the unemployment rate in Virginia?
3.6% in August 2026, against 4.1% for the U.S., seasonally adjusted (U.S. Bureau of Labor Statistics). For all of 2025 it averaged 3.4%, against 4.3% nationwide. The next state figures, for October, are scheduled for Nov. 20, 2026. Virginia’s economy →
What is the minimum wage in Virginia in 2026?
$12.77 an hour since Jan. 1, 2026. State law sets it at $13.75 from Jan. 1, 2027, and $15.00 from Jan. 1, 2028 (Code of Virginia § 40.1-28.10). Virginia’s minimum wage →
How does foreclosure work in Virginia?
Usually without a court. Under a deed of trust, a trustee sells the home at a public sale after mailing notice at least 60 days ahead for a home the owner lives in and advertising the sale in a newspaper (Va. Code §§ 55.1-321 and 55.1-322). There is no right to buy the home back after the sale. How foreclosure works in Virginia →
What is the poverty line in Virginia?
Virginia programs use the federal poverty guideline for D.C. and the 48 contiguous states. In 2026, it is $15,960 a year for a single person and $33,000 for a household of four (U.S. Department of Health and Human Services). The 9.8% poverty rate on this page uses the Census Bureau’s poverty thresholds, a separate measure.
Cite or reuse Virginia’s data
Quote or reuse any figure here, with credit to American Default Research.
State Distress Index
Virginia
32ndmost distressed state
of the 50 states and D.C.
More distressed than 38% of the other states and D.C.
On American Default Research’s State Distress Index, a measure of strain on household finances, Virginia ranks 32nd of the 50 states and D.C., less distressed than each of its six neighbors. Its 2024 poverty rate was 9.8%, against 12.1% for the U.S. (Census Bureau), yet Petersburg, an independent city, scores 99 on the County Distress Index, 14th of 3,144 U.S. counties.
Reporters who want an interview or a custom cut of the data can email press@americandefault.org
Sources and method
We gather the data, run the numbers and research each state ourselves.
This edition: October 2026 · Next edition expected March 2027
- Unemployment rates for Virginia, its counties and cities, and the U.S., by month and by yearU.S. Bureau of Labor Statistics, Local Area Unemployment Statistics and Current Population SurveyJan. 1990 to Aug. 2026
- Federal government jobs and all jobsU.S. Bureau of Labor Statistics, Current Employment Statistics (State and Area), seasonally adjustedJan. 2025 to Aug. 2026
- Poverty rates and typical household income, Virginia and each county and cityCensus Bureau, Small Area Income and Poverty Estimates1989 to 2024
- Renter households spending half or more of income on rent and utilitiesCensus Bureau, American Community Survey, one-year estimates2005 to 2024
- Rent and housing costsCensus Bureau, American Community Survey, five-year estimates2020 to 2024
- PopulationCensus Bureau, population estimates, 2025 release2025
- Income per personU.S. Bureau of Economic Analysis2024
- Bankruptcy filingsAdministrative Office of the U.S. Courts, Table F-22001 to 2025
- Late payments and collectionsFederal Reserve Bank of Philadelphia, Consumer Credit Explorerend of 2019 to early 2025
- Household debt and dollars behindFederal Reserve Bank of New York, Consumer Credit Panel / Equifaxend of 2019 and end of 2025
- Medical debt in collectionsUrban Institute, Debt in America2025
- Mortgages with little equityFederal Housing Finance Agency, National Mortgage Databasesecond quarter of 2026
- Mortgages 30 to 89 days late; mortgage complaints; medical debts on credit reportsConsumer Financial Protection Bureau: Mortgage Performance Trends; complaint database; Recent changes in medical collections on consumer credit recordsSept. 2025; October 2026; March 2022 to June 2023
- SNAPU.S. Department of Agriculture Food and Nutrition Administrationthrough June 2026
- Cost of getting byMIT Living Wage Calculator2025 dollars
- Minimum wageCode of Virginia § 40.1-28.10; Virginia labor department; U.S. Department of Labor, minimum wage laws in the statesJuly 28, 2025; July 1, 2026; read Oct. 17, 2026
- Mortgage help fundU.S. Treasury, Homeowner Assistance Fundthrough early 2026
- Foreclosure lawVa. Code §§ 55.1-321 and 55.1-322; 12 CFR 1024.41as of 2026
- Poverty guidelineU.S. Department of Health and Human Services2026
- Housing counselorsU.S. Department of Housing and Urban DevelopmentOctober 2026
- What changed and what to watchVirginia State Corporation Commission, Virginia’s Insurance Marketplace, Virginia Department of Social Services, U.S. Bureau of Labor Statistics release schedule. Each item links the page it was read on (see what changed)Oct. 2025 to Jan. 2027
- PhotosNyttend, via Wikimedia Commons, public domain; U.S. Navy, via Wikimedia Commons, public domainFeb. 8, 2020; July 7, 2011
Urban Institute data: Breno Braga, Signe-Mary McKernan, Samantha Atherton, and Kassandra Martinchek, "Debt in America," last updated November 20, 2025, https://datacatalog.urban.org/dataset/debt-america-2025. Licensed under ODC-By 1.0.
The score has four equal parts: renters’ housing costs, jobs, late payments, and collections and bankruptcy. We average them for each state, then score each state by the percentage of the other 49 states and D.C. with a lower average, so a score of 80 means more distressed than 80% of them. The full method →
We write with AI tools, and Ross Kilburn checks and reviews every page before it's published.
Get the next Virginia edition by email
One email each time a new Virginia edition is out; the next is expected in March 2027. Unsubscribe anytime.
Thanks, that helps.