21st Mortgage hardship complaints: 45.1%, twice the typical rate
Complaints about struggling to pay make up 45.1% of 21st Mortgage’s CFPB mortgage record, twice the typical rate. 21st Mortgage is a Clayton Homes subsidiary focused on manufactured-home loans. Its customer service number is 800-955-0021. Mail payments to the address on your current statement.

Next edition expected January 2027
21st Mortgage phone, hours and written-request routes
21st Mortgage prints a service number and a written route limited to real-property loans. American Default is independent of 21st Mortgage.
21st Mortgage customer service and financial hardship
800-955-0021The borrower-services page tells people facing payment trouble to call this line.
Listed on 21stmortgage.com · checked Oct 23, 2026
Error notices and information requests for loans secured by real property
21st Mortgage Corporation
Customer Inquiries
620 Market Street, Suite 100
Knoxville, TN 37902
21st says this address is for loans secured by real property. If your home is titled as personal property, ask 21st which address to use.
Listed on 21stmortgage.com · checked Oct 23, 2026
For payments, 21st’s borrower-services page lists online checking or savings account payments and an automated line, 888-598-6121. It says credit cards are not accepted. Checks or money orders go to the Payment Processing Center, P.O. Box 148, Memphis, TN 38101.
21st Mortgage lends on manufactured homes
21st Mortgage is a Clayton Homes subsidiary that markets loans for manufactured and mobile homes. Its borrower-services page describes repayment plans, payment assistance and limited short-sale options for borrowers in hardship.
Struggling to pay is 21st Mortgage’s leading complaint issue
From May 1, 2017, 45.1% of 21st Mortgage mortgage complaints in the CFPB database were labeled “Struggling to pay mortgage.” The median was 23.1%. The 74 peers come from American Default’s servicer directory and Valon. Each had at least 200 mortgage complaints.
21st specializes in manufactured-home lending, while the peer set contains other kinds of mortgage companies. The CFPB complaint categories do not show whether that loan mix explains the higher hardship share. Application complaints, at 9.8% of its record, are close to the 9.9% peer median.
Payment-process issues account for 34.1% of the CFPB record.
Among 149 hardship complaints with a subissue, 58.4% described trouble communicating about modification, forbearance, a short sale or foreclosure. Foreclosure itself accounted for 20.1% of that subset.
Hardship accounts for 45.1% of 21st Mortgage complaints
This company Median of other companies
Struggling to pay mortgage
Trouble during payment process
Applying for a mortgage or refinancing an existing mortgage
Closing on a mortgage
Incorrect information on your report
Problem with a credit reporting company's investigation into an existing problem
The latest 21st Mortgage count rose from 105 to 152
The current CFPB window runs October 21, 2025, through October 20, 2026, with 152 complaints. The preceding equal-length window had 105. Both use “21ST MORTGAGE CORP.”
21st Mortgage: 105 before, 152 now
The 21st Mortgage annual record has a partial final year
The annual series for 21st Mortgage counted 69 complaints in 2024 and 121 in 2025. The 2025 total is its highest complete year in the series. The 2026 bar counts 118 only through October 20. The 2019 count was 28, the lowest complete year in this series.
21st Mortgage: 121 in 2025 and 118 through October 20, 2026
How many 21st Mortgage complaints were timely?
The CFPB marked 149 of 152 complaints received in the latest 12 months timely, or 98.0%. Among 33 other mortgage companies with at least 200 complaints in that window, the typical company answered every complaint on time.
Since January 2025, every 21st Mortgage complaint closed with an explanation; none closed with monetary or nonmonetary relief.
What does 21st Mortgage say about payment trouble?
21st Mortgage’s borrower-services page tells borrowers worried about scheduled payments to call a financial counselor at 800-955-0021. It lists repayment plans and other possible alternatives.
21st prints 800-569-4287 for a list of HUD-certified counseling agencies and links to a state-by-state directory. A free housing counselor can help a borrower compare the company’s options with the household’s situation.
Before discussing assistance, 21st asks borrowers to have tax returns, recent pay stubs, bank statements and monthly bills available. Its borrower-services page also mentions medical or other unexpected bills when relevant.
-
Ask a financial counselor about available options
21st Mortgage names 800-955-0021 for people facing financial hardship. It says the options vary with a borrower’s circumstances.
Source: 21st Mortgage borrower services
Where can a 21st Mortgage borrower complain?
The CFPB form accepts mortgage-servicing complaints involving 21st Mortgage. New York’s Department of Financial Services handled the 2018 branch matter described below. The CFPB state directory identifies the regulator for a current complaint in the borrower’s state.
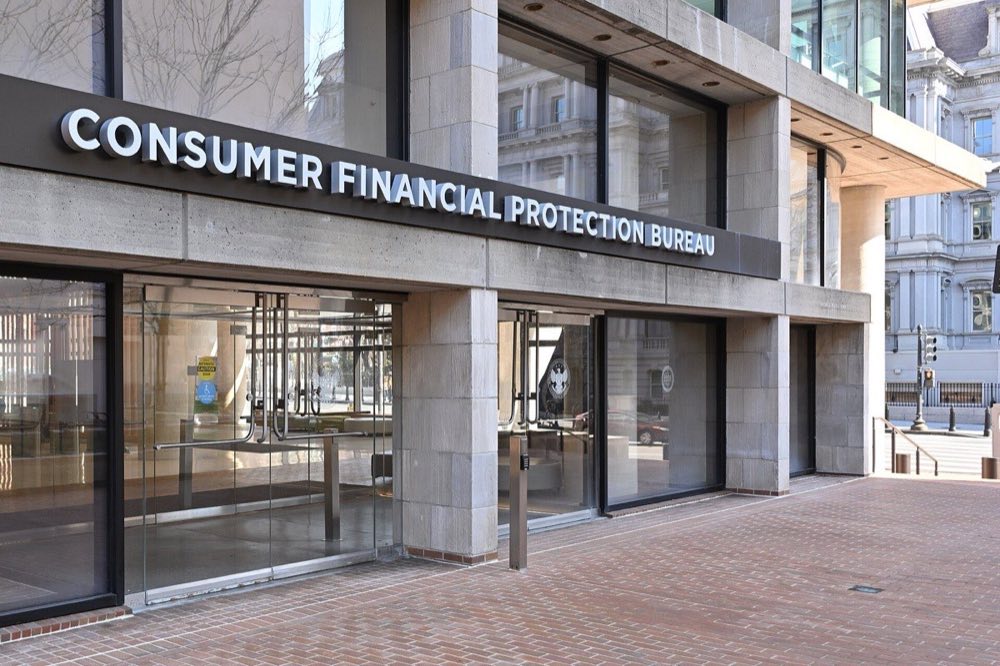
The Consumer Financial Protection Bureau accepts mortgage complaints from borrowers. CFPB contact page

21st Mortgage regulator and court record
New York’s 2018 settlement concerned a branch authorization. A 2025 federal appeal addressed the security interest in a California mobile home. New York imposed a $5,000 fine. The Ninth Circuit later affirmed a ruling about collateral value in one bankruptcy appeal.
-
Aug 11, 2025
U.S. Court of Appeals for the Ninth Circuit Unpublished appellate memorandum
In 21st Mortgage Corp. v. Hayes, the Ninth Circuit affirmed a bankruptcy ruling that limited 21st Mortgage’s security interest to the physical California mobile home. The unpublished memorandum applied California law to that transaction.
Admitted wrongdoing? No admission; this was a contested court appeal.
No government penalty or borrower redress awarded in the appellate decision.
Status: Unpublished appellate memorandum filed August 11, 2025. · Ninth Circuit opinion, docket 24-3600
-
Jan 24, 2018
New York Department of Financial Services Settlement agreement
The state found that 21st Mortgage maintained a New York mortgage-business branch without the required authorization. The agreement required continuing compliance steps.
Admitted wrongdoing? 21st Mortgage agreed to resolve the cited violation and waived a hearing; the agreement does not use an express neither-admit-nor-deny clause.
$5,000 fine to New York. The signed agreement states no borrower restitution.
Status: Settlement agreement signed January 24, 2018. · New York DFS signed settlement
What do the federal written-request rules say?
These deadlines describe ordinary cases; exceptions and extensions apply.
-
Written requests: route and response times
21st limits its printed Customer Inquiries address to loans secured by real property. Regulation X section 35 gives five business days to acknowledge an error notice and 30 for a substantive response. Section 36 sets 30 business days for information requests and 10 for the loan owner’s identity.
Source: Consumer Financial Protection Bureau Regulation X, sections 35 and 36
Get the next edition of this page by email
One email when the next edition is out, expected in January 2027. Unsubscribe anytime.
Thanks, that helps.
Questions about 21st Mortgage
Which 21st Mortgage number handles hardship questions?
The borrower-services page tells borrowers worried about a scheduled payment to call 800-955-0021. It lists weekday hours of 9 a.m. to 6 p.m. Eastern.
How can a 21st Mortgage borrower request a payoff quote?
The borrower-services page directs customers to Online Account Access to generate a payoff quote. It also lists 800-955-0021 extension 2900 and fax 877-830-3100 for payoff information.
What did the 2025 Hayes appeal decide?
The Ninth Circuit affirmed a ruling that valued 21st Mortgage’s security interest in a California mobile home as the physical home alone. The appeal did not impose a government fine.
What did New York’s 2018 agreement require 21st Mortgage to pay?
The signed branch-authorization agreement imposed a $5,000 fine to New York. It did not order a borrower payment.
Protect yourself from scams
The FTC and CFPB describe these warning signs and the rules behind them:
- Upfront fees for promised relief are a warning sign. Under FTC mortgage-assistance rules, most companies that sell mortgage help cannot charge until a homeowner accepts a written offer from the mortgage company or lender. A separate FTC rule covers debt-relief companies that sell by phone and ties fees to a completed debt arrangement. It bars a fee until at least one debt has been settled or changed, the customer agrees to the arrangement, and the customer has made a payment under it. The FTC describes a narrow exception for lawyers who give help as part of the practice of law and are licensed in the state where the client or dwelling is. The lawyer follows that state's rules for attorneys, and advance fees are placed in a client trust account before services begin under state trust-account rules.
- HUD-approved foreclosure-prevention counseling is free. HUD’s national counselor line is 800-569-4287. The CFPB counselor finder lists agencies and their services. If an organization charges for help described as free HUD counseling, the CFPB finder can verify the agency and its listed services before any payment.
- A request to sign over a deed is a warning sign. The CFPB identifies title-transfer schemes among foreclosure-relief scams. Signing over title can mean losing ownership of the home; a lawyer can explain what a proposed document would do.
- Foreclosure protections depend on timing and the loan. Regulation X generally bars the first foreclosure notice or filing on a principal-residence loan until the borrower is more than 120 days behind, subject to exceptions. A complete assistance application can delay some foreclosure steps, but that depends on when it arrives; it does not necessarily stop every step. The CFPB warns about promises to “save” a home.
Free help if you're behind
Housing counselors approved by the U.S. Department of Housing and Urban Development work at nonprofit agencies. The Consumer Financial Protection Bureau describes free foreclosure-avoidance counseling, including help with mortgage-company conversations and available options Source CFPB.
-
HUD-approved housing counselors
Our help directory lists 1,010 agencies approved for foreclosure counseling, by state.
-
Legal aid
Nonprofit law offices give free civil legal help to people with low incomes. Our help directory lists the 120 offices the Legal Services Corporation funds.
Every figure on this page, with its period and the CFPB filter behind it, in one file. Free to use with credit to American Default Research.
Sources and method
We gather the data, run the numbers and research each company ourselves. The CFPB publishes complaints without verifying every borrower account. Counts use the CFPB company name “21ST MORTGAGE CORP.” and the dates printed beside each chart. Peer medians use company labels drawn from American Default’s servicer directory and Valon. Each peer has at least 200 mortgage complaints in the period measured by its chart. Updated: October 2026 · Next review expected: January 2027.
- Consumer Financial Protection Bureau, Consumer Complaint Database Mortgage complaints about the company, received through Oct 20, 2026. Our counts from the CFPB's complaint records.
- Clayton Homes subsidiaries
- Financial-hardship line and options
- Customer-service hours and real-property written route
- 2018 New York settlement
- 2025 mobile-home security-interest appeal
- CFPB mortgage complaint data
- State regulator complaint directory
- Free housing counseling
We write with assistance from AI tools. Figures come from the data and sources named on this page.