What would you walk away with if you sold?
If you're behind, what matters is what's left after the loan is paid off, not just what the house is worth. Put in your own rough numbers and see a range.
Your figures stay in this browser. Only whether the range is above zero, below zero or crosses zero is counted. No address, no name, no phone number.
Your range shows here
A rough estimate from your numbers, not an offer or an appraisal.
What the house is worth, minus what you owe, minus selling costs of 5% to 12% of the price. That's Freddie Mac's range for the agent's commission (3% to 8%) plus fees and taxes (2% to 4%). Being behind adds missed payments, interest and fees to what you owe, so put those in if you know them. Source: Freddie Mac, Understanding the costs of selling your home.
Want a closer number for your house?
Tell me where it is and where things stand. I'll call and go over what selling could look like, and what else is open to you.
I can't help with homes in Washington.
A HUD-approved housing counselor can, for free. Counselors are advisers approved by the government who can go over your options with your mortgage company. Call 800-569-4287.
I didn't save anything you typed.
Got it, thanks. I have your request.
What happens next
I'll read what you sent, then call you. You said any time works. I'll go over your options with you, and you decide what to do. There's no obligation.
Thanks, that helps.
Free help, whatever you decide
A HUD-approved housing counselor is a free adviser, approved by the government, who can go over your options with your mortgage company. You can reach one at 800-569-4287.
Read the free foreclosure guides →What changes the number?
The payoff, not the balance
Your lender's payoff figure adds missed payments, interest and fees to the balance. The further behind you are, the more comes off the top.
Selling costs
Agent commission and closing costs come out of the sale price, not out of your pocket up front.
What buyers will pay
Your guess is a starting point. A real price comes from recent sales near you and the condition of the house.
What if the range is below zero?
Then the sale price would not cover the loan payoff and selling costs. Selling costs can make the result negative even when the house is worth more than you owe. A short sale is one path: the lender agrees to take less than the payoff. A deed in lieu is another: you hand the house back. In both, the lender decides.
If you'd rather try to stay, a HUD-approved housing counselor, a free adviser approved by the government, can go over your options with your mortgage company. Call 800-569-4287.
General information, not legal or financial advice. Rules and deadlines differ by state.
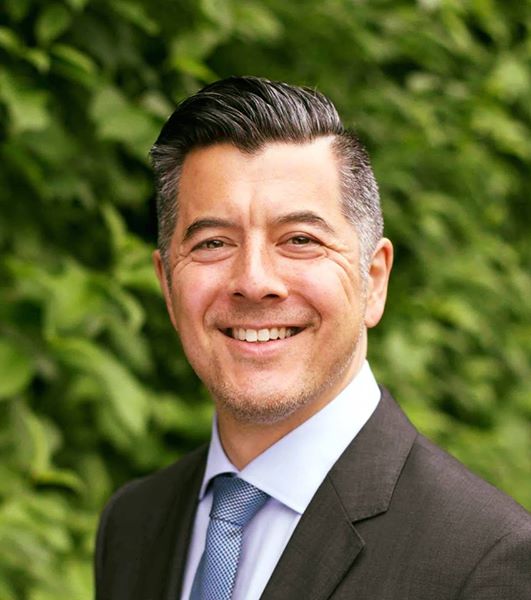
Who you'd be talking to
I'm Ross Kilburn. I've worked with homeowners in trouble for more than 20 years. I was COO of Ark Law Group, PLLC, a foreclosure defense firm. I founded Seattle Short Sales, Inc. and co-authored The Ark Law Group Complete Guide to Short Sales.
I also run American Default, which publishes the American Distress Index: a quarterly score of how U.S. households are keeping up with their bills.
The latest score is 47.0 for Q2 2026, in its typical range.
American Distress Index →Questions about selling your home
Is this range what I'd get?
No. It's arithmetic on the numbers you typed. It isn't an offer, an appraisal or a promise. A real figure needs your lender's payoff and a look at the house.
What does it cost to talk to you?
Nothing. I'm not paid for connecting you with an agent, and the agent doesn't pay me.
Are you with the government or my lender?
No. I'm not with any government agency or lender, and neither is American Default.
Free help, separate from selling
A HUD-approved housing counselor is a free adviser, approved by the government, who can go over your options with your mortgage company. They help whether or not you ever sell. Call 800-569-4287.
Opportunity
American Default is not affiliated with any government agency or lender. Ross Kilburn is not paid for referrals. He keeps your information private and never sells it.