Sell, short sale, or something else? See them side by side.
If you're behind on the mortgage, you have more than one option. Here's what each costs, what it does to your credit, and who it suits.
See the comparison →I can't help with homes in Washington.
A HUD-approved housing counselor can, for free. Counselors are advisers approved by the government who can go over your options with your mortgage company. Call 800-569-4287.
I didn't save anything you typed.
Got it, thanks. I have your request.
What happens next
I'll read what you sent, then call you. You said any time works. I'll go over your options with you, and you decide what to do. There's no obligation.
Thanks, that helps.
Free help, whatever you decide
A HUD-approved housing counselor is a free adviser, approved by the government, who can go over your options with your mortgage company. You can reach one at 800-569-4287.
Read the free foreclosure guides →How do the ways to sell compare?
Here are five ways to go, including staying in the home. Each one suits a different situation.
Swipe the table sideways to see every path.
| Path | List with an agent | Short sale | Sell to a cash buyer | Deed in lieu | Keep the home, with a free housing counselor |
|---|---|---|---|---|---|
| Time | Listing, showings, then closing. Depends on your market. | Longer than a regular sale, because the lender must approve the price. | Often the fastest. | Depends on the lender's review. | Depends on your lender and the program. |
| Cost | Commission and closing costs, paid from the sale. | Costs are paid from the sale with the lender's OK. Whether any debt remains depends on the mortgage company's written agreement. | Usually a lower price than the open market would pay. | You leave with no sale money. Whether any debt remains depends on the mortgage company's written agreement. | The counseling is free. Catch-up terms depend on your lender. |
| Credit | A sale that pays the loan in full adds no new negative mark. Late payments already reported can stay up to seven years. | Can delay a new mortgage. Fannie Mae's waiting period is four years, or two if the hardship was caused by something outside your control. | Same as a regular sale if the price covers the payoff. | Can delay a new mortgage. Fannie Mae's waiting period is four years, or two if the hardship was caused by something outside your control. | Depends on what you and your lender agree to. |
| Who it suits | You have equity and time before any sale date. | You owe more than the house would sell for. | You need speed, or the house needs big repairs, and you'll accept less. | The house won't sell and the lender agrees to take it back. | You want to stay and can afford a payment going forward. Call 800-569-4287. |
General information, not legal or financial advice. Credit row: CFPB on how long negative information stays on a credit report; Fannie Mae Selling Guide B3-5.3-07 on waiting periods. Rules and deadlines differ by state.
The cash-buyer column is here because it's a real option. I don't send homeowners to cash buyers, and no cash buyer pays me.
Not sure which fits? Tell me about the house.
Five short questions, starting with the address. I'll call and walk you through the table for your house.
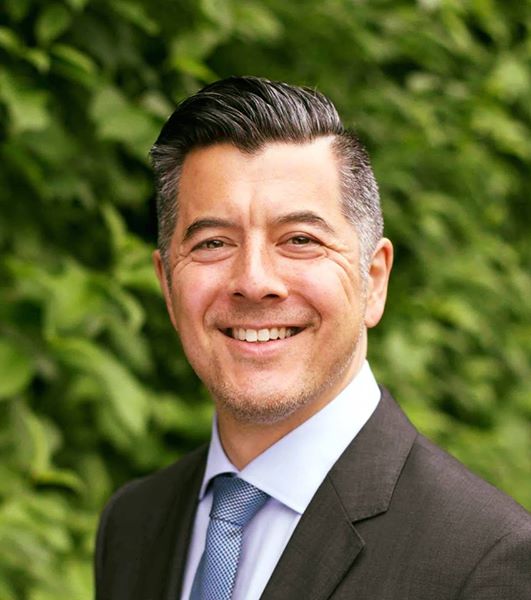
Who you'd be talking to
I'm Ross Kilburn. I've worked with homeowners in trouble for more than 20 years. I was COO of Ark Law Group, PLLC, a foreclosure defense firm. I founded Seattle Short Sales, Inc. and co-authored The Ark Law Group Complete Guide to Short Sales.
I also run American Default, which publishes the American Distress Index: a quarterly score of how U.S. households are keeping up with their bills.
The latest score is 47.0 for Q2 2026, in its typical range.
American Distress Index →Questions about selling your home
What's the difference between a short sale and a foreclosure?
In a short sale you sell the house, with the lender's approval, for less than you owe. In a foreclosure the lender takes the house and sells it. A short sale leaves you more say in the timing of your move.
What does it cost to talk to you?
Nothing. I'm not paid for connecting you with an agent, and the agent doesn't pay me.
Are you with the government or my lender?
No. I'm not with any government agency or lender, and neither is American Default.
Free help, separate from selling
A HUD-approved housing counselor is a free adviser, approved by the government, who can go over your options with your mortgage company. They help whether or not you ever sell. Call 800-569-4287.
Opportunity
American Default is not affiliated with any government agency or lender. Ross Kilburn is not paid for referrals. He keeps your information private and never sells it.